
폴리올레핀 엘라스토머 시장: 잠재력, 성장 및 동향 (2034년까지)
폴리올레핀 엘라스토머 시장 규모 및 전망(2021~2034), 글로벌 및 지역별 점유율, 트렌드 및 성장 기회 분석 보고서 내용: 유형별(폴리에틸렌, 폴리프로필렌, 기타), 응용 분야별(접착제, 전선 및 케이블, 필름, 기타), 최종 용도별(자동차, 의료, 포장, 기타), 지역별(북미, 유럽, 아시아 태평양, 남미 및 중미)
- 상태 : 데이터 공개
- 보고서 코드 : TIPRE00028419
- 범주 : 화학 및 재료
- 페이지 수 : 150
- 사용 가능한 보고서 형식 :


- 최종 업데이트 일자 : July 03, 2026


2025년 시장 규모
33 억 8 천만 달러
기준연도 값
2034년 전망
57 억 8 천만 달러
2034년까지 예상됨
2026-2034년 연평균 성장률
6.14 %
성장률
공략 가능 시장
414 억 7천만 달러
(2026-2034)
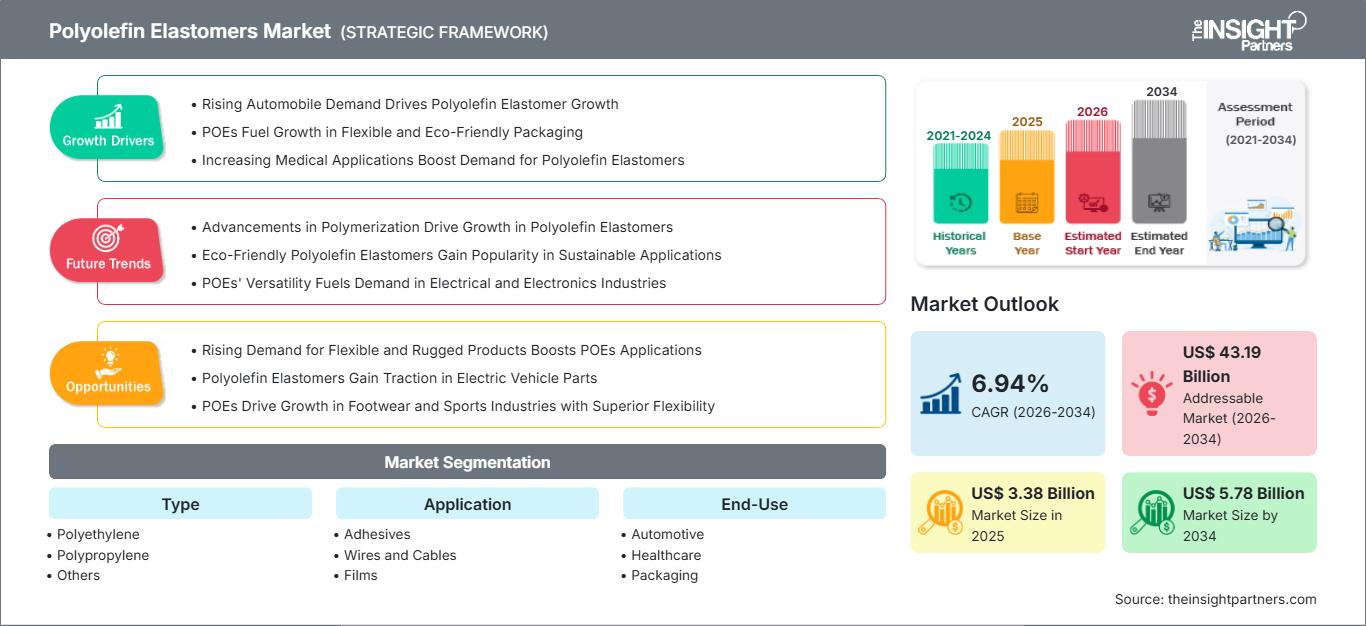
폴리올레핀 엘라스토머 시장은 2025년 33억 8천만 달러 규모였으며, 2034년에는 57억 8천만 달러에 이를 것으로 예상됩니다. 2026년부터 2034년까지 연평균 성장률(CAGR)은 6.14%로 추정됩니다.
폴리올레핀 엘라스토머 시장 평가 및 분석
- 북미: 북미는 2025년 시장 점유율 31~35% 를 차지했으며, 2026년부터 2034년까지 연평균 5.8~6.4%의 성장률을 보일 것으로 예상됩니다 . 강력한 자동차 제조 산업, 첨단 고분자 가공 기술, 그리고 지속 가능한 포장재에 대한 투자 증가가 이 지역 시장의 꾸준한 성장을 뒷받침하고 있습니다.
- 미국: 미국 은 2025년 북미 시장의 82~86%를 차지했으며 , 자동차, 포장 및 산업 제조 부문의 견조한 수요와 첨단 고분자 소재의 지속적인 도입에 힘입어 2026년부터 2034년까지 연평균 5.9~6.5%의 성장률을 기록할 것으로 예상됩니다.
- 유럽: 유럽은 2025년 에 24~28%의 시장 점유율을 차지했으며, 2026년부터 2034년까지 연평균 5.5~6.1%의 성장률을 보일 것으로 예상됩니다 . 독일, 프랑스, 영국은 첨단 자동차 생산, 강력한 산업 제조업, 그리고 지속 가능한 소재 솔루션의 도입 증가에 힘입어 주요 시장으로 남아 있습니다.
- 아시아 태평양 지역: 아시아 태평양 지역은 2025년 시장 점유율 34~38% 를 차지했으며 , 2026년부터 2034년까지 연평균 7.8~8.4%의 성장률 을 보일 것으로 예상됩니다 . 중국, 일본, 인도는 제조 역량 확대, 급속한 산업화, 인프라 구축에 따른 고분자 소비 증가에 힘입어 지역 수요를 주도하고 있습니다.
- 가장 큰 시장 부문: 포장(최종 용도) 은 가장 큰 시장 부문으로, 2026년부터 2034년까지 연평균 6.6~7.2%의 성장률을 기록할 것으로 예상됩니다 . 이는 식품, 소비재 및 산업 분야 전반에 걸쳐 경량, 유연성 및 재활용 가능한 포장재에 대한 수요 증가를 반영합니다.
- 고성장 부문: 의료(최종 사용) 부문은 의료용 엘라스토머에 대한 수요 증가, 의료 분야 응용 확대, 라텍스 프리 소재에 대한 규제 선호도 증가에 힘입어 2026년부터 2034년까지 연평균 7.7~8.3%의 성장률을 기록할 것으로 예상됩니다.
- Key companies analyzed in detail: Dow Inc.; Exxon Mobil Corporation; LG Chem Ltd.; LyondellBasell Industries N.V.; Mitsubishi Chemical Group Corporation; Mitsui Chemicals, Inc.; PolyOne Corporation (Avient Corporation); RTP Company; SABIC; Borealis AG.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
Polyolefin elastomers have evolved from specialty polymer modifiers into essential materials for high-performance industrial applications because of advances in catalyst technologies, resin engineering, and process optimization. Improvements in molecular structure control have enhanced elasticity, impact resistance, transparency, and sealing performance while enabling efficient large-scale production. Manufacturers increasingly integrate advanced polymerization techniques with sustainable manufacturing practices to improve product consistency, operational efficiency, and supply chain resilience across diverse end-use industries.
The market outlook remains favorable as investments expand across Asia Pacific, the Middle East, and selected Latin American manufacturing hubs, supported by industrial diversification and downstream polymer processing capacity. Regulatory emphasis on recyclable materials, lightweight product design, and reduced environmental impact encourages innovation in polyolefin elastomer formulations. Continued collaboration between material suppliers, converters, and end-use manufacturers is expected to accelerate commercialization of next-generation applications while strengthening long-term global market competitiveness.
Polyolefin Elastomers Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 3.38 Billion |
| Market Size by 2034 | US$ 5.78 Billion |
| Global CAGR (2026 - 2034) | 6.14% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Polyolefin Elastomers Market Analysis
The increasing need for light, tough, and flexible materials drives the market for polyolefin elastomers in several industrial applications. In the automotive industry, polyolefin elastomers are increasingly being used in order to reduce the weight of automobiles and make them more robust. Polyolefin elastomers are also gaining popularity in the packaging industry because of their flexibility and puncture resistance properties. Increased usage of polyolefin elastomers is expected in the healthcare industry because of their chemical resistance and sterilizability.
The value chain consists of suppliers of raw materials, catalyst suppliers, polymer producers, compounders, converters, distributors, and consumers. Stable sources of ethylene and propylene raw material help in the production process irrespective of price fluctuations within the petrochemical industry during manufacturing. Effective supply chain has been ensured through localized manufacturing facilities, long-term feedstock contracts, and digitized manufacturing processes.
Competitive environment is described by constant innovation, portfolio diversification, and investments in sustainable materials technologies. Dow Inc., Exxon Mobil Corporation, LG Chem Ltd., LyondellBasell Industries N.V., and SABIC further increase their advanced elastomers range intended for use in automotive, packaging, and industrial industries. The differentiation of products is more and more dependent on processability, mechanical characteristics, recyclability, and ability to be processed using existing machinery, giving manufacturers an opportunity to improve customer relations.
In addition, companies increasingly invest in increasing the polymer production, special grade polymers development, and regional supply abilities. Mitsubishi Chemical Group Corporation, Mitsui Chemicals, Inc., Avient Corporation, RTP Company, and Borealis AG further enhance their competitiveness through research partnerships, custom compounds, and sustainable products developments.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Polyolefin Elastomers Market:
요구 사항에 맞게 이 보고서를 사용자 정의하십시오.
이 보고서의 일부, 국가 수준 분석, Excel 데이터 팩을 포함하여 모든 보고서에 대한 사용자 정의를 무료로 받을 수 있을 뿐만 아니라 스타트업 및 대학을 위한 훌륭한 제안 및 할인을 이용할 수 있습니다
폴리올레핀 엘라스토머 시장: 전략적 통찰력
-
이 보고서의 주요 주요 시장 동향을 확인하세요.이 무료 샘플에는 시장 동향부터 추정 및 예측에 이르기까지 데이터 분석이 포함됩니다.
Regional Insights
North America Polyolefin Elastomers Market
North America accounted for 31–35% of the global polyolefin elastomers market in 2025 and is projected to register a CAGR of 5.8–6.4% during 2026–2034. Strong manufacturing infrastructure and advanced polymer processing capabilities continue to support steady regional demand.
Growth is driven by expanding automotive lightweighting initiatives, increasing demand for sustainable packaging, and continued investment in wire and cable infrastructure. High research intensity and established supply chains enable rapid commercialization of advanced polyolefin elastomer grades across industrial applications.
U.S. Polyolefin Elastomers Market
The United States represented 82–86% of the North American market in 2025 and is anticipated to grow at a CAGR of 5.9–6.5% through 2034. The country's integrated petrochemical industry provides a strong foundation for elastomer production and downstream processing.
Leading manufacturers maintain extensive production, research, and technical service operations throughout the country. Demand continues to increase across automotive components, flexible packaging, medical products, and electrical insulation, supported by continuous material innovation and high-value industrial manufacturing.
Europe Polyolefin Elastomers Market
Europe accounted for 24–28% of global revenue in 2025 and is expected to expand at a CAGR of 5.5–6.1% during the forecast period. Sustainability regulations and advanced manufacturing capabilities continue to encourage adoption of recyclable and lightweight polymer materials.
The United Kingdom is experiencing stable demand from healthcare packaging, specialty films, and infrastructure modernization projects. Continuous investment in sustainable manufacturing and polymer innovation supports gradual expansion across domestic converting industries.
Germany remains the leading European market because of its strong automotive manufacturing base, engineering expertise, and advanced polymer processing sector. France, Italy, and Spain continue to strengthen regional demand through packaging modernization, industrial manufacturing, and growing use of flexible polymer materials in consumer and medical applications.
APAC Polyolefin Elastomers Market
Asia Pacific represented 34–38% of global demand in 2025 and is forecast to record the fastest regional expansion with a CAGR of 7.8–8.4%. Rapid industrialization, rising polymer consumption, and expanding manufacturing investments continue to strengthen regional market fundamentals.
China leads regional consumption owing to its large packaging, automotive, and electronics manufacturing sectors. Government support for advanced materials and domestic production capacity expansion further reinforces long-term market development.
Japan, South Korea, India, and Australia contribute through technological innovation, healthcare manufacturing, automotive production, and infrastructure development. Increasing investment in sustainable materials and high-performance polymers is expected to create additional opportunities throughout the forecast period.
Middle East & Africa Polyolefin Elastomers Market
The Middle East and Africa market is projected to grow at a CAGR of 6.3–6.9% during 2026–2034. Expanding petrochemical investments and industrial diversification initiatives are strengthening regional demand for advanced polymer materials.
Saudi Arabia leads regional production through its integrated petrochemical industry, while the United Arab Emirates continues investing in downstream manufacturing and logistics infrastructure. These developments support increasing regional availability of specialty polymer products.
South Africa remains an important consumer market supported by automotive manufacturing and packaging demand, while the rest of the Middle East and Africa benefits from expanding infrastructure projects, industrial development, and rising investment in value-added polymer processing.
Segmentation Analysis
Type
The Polyethylene segment is expected to remain the leading product category, registering a CAGR of 6.8–7.4% during 2026–2034. High flexibility, excellent impact resistance, superior processability, and broad compatibility with packaging, automotive, and consumer applications continue to strengthen its market position across both mature and emerging manufacturing economies.
- Polyethylene: Widely utilized in flexible packaging, automotive components, and industrial applications because of its balance of elasticity, durability, process efficiency, and compatibility with advanced polymer processing technologies.
- Polypropylene: Increasing adoption in lightweight automotive parts, consumer products, and industrial components is supported by improved stiffness, thermal stability, and enhanced mechanical performance in demanding operating environments.
Application
The Adhesives segment is anticipated to record a CAGR of 7.0–7.6% during the forecast period, supported by rising demand for high-performance hot-melt adhesives in packaging, hygiene products, construction materials, and consumer goods manufacturing.
- Adhesives: Polyolefin elastomers improve flexibility, bonding performance, impact resistance, and thermal stability, making them suitable for packaging, hygiene products, industrial assembly, and construction adhesive formulations.
- Wires and Cables: Demand is increasing because these materials provide excellent insulation, flexibility, weather resistance, and long-term durability in power distribution, telecommunications, and industrial electrical infrastructure.
- Films: Growing use in food packaging, industrial wrapping, and specialty films is driven by improved sealability, puncture resistance, optical clarity, and enhanced mechanical performance under demanding operating conditions.
End-Use
The Packaging segment is projected to remain the largest end-use category, expanding at a CAGR of 6.6–7.2% during 2026–2034. Increasing preference for lightweight, recyclable, and durable packaging materials across food, pharmaceutical, personal care, and consumer goods industries continues to drive sustained demand globally.
- Automotive: Manufacturers increasingly adopt polyolefin elastomers to reduce vehicle weight while improving durability, impact resistance, vibration control, and component design flexibility in conventional and electric vehicles.
- Healthcare: Rising production of medical devices, pharmaceutical packaging, and latex-free healthcare products supports increasing consumption of high-purity polyolefin elastomer formulations with reliable sterilization performance.
- Packaging: Strong demand originates from flexible packaging, food preservation solutions, industrial films, and consumer goods applications requiring excellent sealing performance, durability, and recyclability.
Opportunity Snapshot
|
Application Segment |
Revenue Contribution |
Trend Tag |
Adoption Stage |
|
Adhesives |
High |
Hot-Melt |
Mature |
|
Wires and Cables |
Medium |
Grid Modernization |
Scaling |
|
Films |
High |
Barrier Films |
Mature |
|
Others |
Low |
Industrial Blends |
Emerging |
Polyolefin Elastomers Market Growth Drivers and Impact Analysis
Expanding Demand for Lightweight Automotive Components
Automotive manufacturers are increasingly using polymers in lieu of conventional materials to improve fuel efficiency, mileage per charge, and minimize vehicle emissions. Polyolefin elastomers have excellent flexibility, toughness, vibration-damping capabilities, and design possibilities for use in interior, exterior, and under-hood components. They are compatible with advanced molding techniques, which makes them even more desirable. As automotive platforms evolve and adopt lighter-weight designs, there will be growing demand for high-performance elastomer materials, spurring polymer producers to develop grades that meet the required specifications.
Growing Adoption of Flexible and Sustainable Packaging Solutions
The growing consumer preference for ease of handling, improved shelf life, and recyclable products has increased demand for advanced polymers. The use of polyolefin elastomers increases film flexibility, sealability, tear resistance, and durability without any decrease in processability in packaging. Manufacturers of packaging products across industries such as food, pharmaceuticals, personal care, and industrial goods are increasingly using these polymers as part of multilayer systems to improve performance. Legislation requiring packaging waste reduction and improved recyclability of packaging materials increases efforts to design elastomer systems that help produce eco-friendly packaging products without affecting performance and processability.
Increasing Investments in Electrical Infrastructure and Cable Systems
The modernization of power transmission grids, renewable energy installations, telecom grids, and industrial electrical systems continues to generate sustained demand for insulation materials. The polyolefin elastomers provide exceptional electrical insulation, flexibility, weather resistance, and longevity in the face of harsh conditions. These materials have become the materials of choice for medium- and high-performance cables due to their outstanding physical properties. Increased investment in smart grids, industrial automation, and renewable energy developments is likely to further boost their consumption in the wire and cable manufacturing industry.
Polyolefin Elastomers Market Future Trends
Development of Circular Polymer Solutions Through Advanced Recycling
The shift toward circular manufacturing is affecting product development strategies in the polymer industry. Manufacturers are investing in recycling technologies and circular feedstocks that will not only enable them to ensure their products are easily recyclable but also maintain their elastomer performance. There has been a trend in the design of polyolefin elastomers to make them compatible with mechanical and chemical recycling processes. The future product range will include enhanced mechanical performance and recyclability.
Expansion of Customized Elastomer Grades for Specialized Applications
Materials with unique properties in terms of mechanics, temperature, and processability are increasingly needed in end-user applications. To meet this challenge, manufacturers are introducing custom-designed polyolefin elastomers for use in medical devices, specialty films, automotive sealing, consumer goods, and industrial compounds. New developments in material design software, innovative catalyst technology, and joint product development are contributing to faster time-to-market and consistent product performance. This will foster new relationships between material providers and manufacturers, leading to high-value-added products.
Polyolefin Elastomers Market Opportunities
Capacity Expansion in Emerging Manufacturing Economies
Industrialization in Asia, the Middle East, and Latin America offers opportunities for manufacturers seeking to enhance their regional production capabilities. Setting up local production facilities will help reduce transport costs, increase delivery reliability, and enable quicker responses to customer needs. Governments continue to encourage downstream petrochemical development through various measures, such as industrial incentives, infrastructure investments, and export-oriented manufacturing. Firms that can boost their regional manufacturing activities and provide local technical support, as well as application development, are expected to gain market share and retain customers.
Innovation in High-Performance Medical and Specialty Polymer Applications
Healthcare and specialty industrial applications present attractive long-term investment opportunities because they require materials with stringent performance, purity, and regulatory compliance characteristics. Manufacturers can differentiate their product portfolios by developing advanced elastomer formulations suitable for pharmaceutical packaging, medical devices, diagnostic equipment, and specialized industrial components. Collaboration with healthcare manufacturers and research organizations can accelerate commercialization while supporting regulatory approvals. Continued innovation in sterilization-compatible, latex-free, and chemically resistant elastomer technologies is expected to create premium market segments with higher value realization and stronger long-term profitability.
Recent Developments
- In December 2025: Dow expanded the cross-industry application of its specialty polyolefins by partnering with seating manufacturer Lear and luxury carmaker Jaguar Land Rover. The companies co-developed a new, lightweight automotive seat cushion engineered using advanced polyolefins. The objective of this development is to ensure full end-of-life circularity and recyclability for vehicle interiors.
- In June 2024, LG Chem finalized the fund allocation from its international Green Bond framework to scale up production capacity specifically for eco-friendly and renewable polymers. A major portion of these proceeds was deployed directly to secure and run an annual capacity of 100,000 tons of Polyolefin Elastomers (POE). This forms part of the company's broader KRW 10 trillion investment strategy targeting green materials, including solar panel encapsulants and automotive-grade impact modifiers.
- 2023년 5월, 다우는 자동차 산업의 탄소 발자국 감소를 지원하기 위해 바이오 순환형 ENGAGE™ REN 폴리올레핀 엘라스토머(POE)의 글로벌 출시를 최초로 상용화하고 강조했습니다. 이 고성능 폴리올레핀 엘라스토머 제품군은 ISCC+ 물질수지 시스템을 통해 바이오 순환형 원료(예: 폐식용유)를 사용하여 생산됩니다. 이 개발은 기존 화석 연료 원료와 동일한 성능 특성을 가진 제품을 찾고자 하는 전 세계 자동차 및 내구 소비재 시장을 겨냥하고 있습니다.
자주 묻는 질문

Vrushali는 8년 이상의 경력을 보유한 수석 컨설턴트(Senior Consultant)로, 특히 특수화학제품(Specialty Chemicals)을 중심으로 화학 및 소재(Chemicals & Materials) 산업 분야에서 깊이 있는 전문 지식과 풍부한 실무 경험을 갖추고 있습니다. 지금까지 화학 및 소재, 식품 및 음료(Food & Beverage), 소비재(Consumer Goods) 등 다양한 산업 분야에서 50건 이상의 컨설팅 프로젝트를 성공적으로 수행해 왔습니다. 주요 전문 분야는 기능성 원료(Functional Ingredients), 재생 가능한 원료 기반 화학제품(Renewable Chemicals), 동물 사료(Animal Feed), 농업용 화학제품(Agrochemicals) 등으로 폭넓게 구성되어 있습니다. 이러한 산업별 전문성과 분석 역량을 바탕으로 기업이 새로운 시장 기회를 발굴하고 효과적인 성장 전략을 수립할 수 있도록 지원하고 있습니다.
Vrushali는 화학 학사 학위와 경영학 석사 학위를 보유하고 있으며, 탄탄한 기술적 전문 지식과 비즈니스 전략에 대한 깊이 있는 이해를 겸비하고 있습니다. 다양한 고객사를 대상으로 시장 확대 기회 평가, 사업 성장 전략 수립, 운영 혁신(Operational Transformation) 이니셔티브의 실행을 지원해 왔습니다. 또한 기술적 전문성과 경영 전략에 대한 통합적인 이해를 바탕으로 복잡한 시장 환경과 산업별 요구사항을 분석하고, 고객의 비즈니스 목표에 부합하는 실질적인 전략적 해결책을 제시하고 있습니다.
Vrushali의 핵심 역량에는 신규 고객 확보(Client Acquisition), 이해관계자 관리(Stakeholder Management), 팀 리더십(Team Leadership)이 포함됩니다. 체계적이고 구조화된 프로젝트 관리 및 수행 방식을 통해 고객사의 운영 효율성과 생산성 향상에 기여해 왔습니다. 특히 기술적 전문 지식과 상업적 우선순위 및 비즈니스 목표를 효과적으로 연계하는 능력을 바탕으로, 고객의 개별적인 사업 요구사항에 최적화된 실용적이고 실행 가능한 전략적 권고안과 맞춤형 솔루션을 제공합니다. 이를 통해 고객사가 경쟁력을 강화하고 지속 가능한 사업 성장과 장기적인 전략적 목표를 달성할 수 있도록 지원하고 있습니다.
- 포괄적인 시장 규모 산정 및 전망 분석
- 상세 시장 세분화 분석
- 심층적인 시장 동향 및 요인 분석
- 지역 및 국가별 인사이트
- 경쟁 구도 및 기업 벤치마킹
- 전략적 비즈니스 인텔리전스
사용 후기

The Insight Partners는 당사의 글로벌 시장 진출 전략을 뒷받침하는 가치 있는 시장 정보를 제공했습니다. 담당 팀은 전문적이고 신속하게 대응했으며 당사의 의견을 세심하게 반영했습니다. 또한 프로젝트 전반에 걸쳐 깊이 있는 분석과 유용한 방법론적 설명을 제공했습니다.
Junmo Kim 최고재무책임자(CFO), Enertech Co., Ltd.
Insight Partners의 SCADA 시스템 시장 보고서는 포괄적이며, 현재 동향과 미래 전망에 대한 귀중한 통찰력을 제공합니다. 팀은 매우 전문적이고, 신속하게 대응하며, 처음부터 끝까지 지원해 주었습니다. 저희는 매우 만족하며 Insight Partners의 서비스를 적극 추천합니다.
란 케뎀 파트너, Reali Technologies LTDs
아주 구체적인 소프트웨어 시장에 대한 보고서를 요청했는데, 팀에서 며칠 만에 보고서를 작성해 주셨습니다. 정보는 매우 관련성이 높고 잘 정리되어 있었습니다. 그 후 보고서에 몇 가지 수정과 추가 사항을 요청했습니다. 팀원들의 응답도 매우 빨랐고, 일주일도 채 되지 않아 최종 보고서를 받았습니다.
장-에르브 젠 의장, 퓨처 애널리티카
The Insight Partners와 함께 중요한 시장 조사 및 예측 작업을 진행했습니다. Insight Partners는 기회와 위험에 대한 명확한 통찰력을 제공하여 계획을 세우는 데 큰 도움이 되었습니다. The Insight Partners의 조사는 사용하기 쉬웠고, 탄탄한 데이터를 기반으로 했습니다. 덕분에 현명하고 자신 있는 결정을 내릴 수 있었습니다. The Insight Partners를 강력 추천합니다.
피유시 나그팔 수석 부사장, 하이빔 글로벌
Insight Partners는 탄탄한 분야 전문성을 바탕으로 통찰력 있고 체계적인 시장 조사를 제공했습니다. Insight Partners 팀은 처음부터 끝까지 전문적이고 신속하게 대응했습니다. 사용자 친화적인 웹사이트 덕분에 업계 보고서에 쉽게 접근할 수 있었습니다. 신뢰할 수 있고 고품질의 조사 서비스를 원하신다면 Insight Partners를 강력 추천합니다.
아다치 유키히코 대표이사, 딥블루 주식회사
The Insight Partners에서 시장 보고서를 구매한 것은 이번이 처음입니다. 처음에는 확신이 없었지만, 웹사이트를 방문하고 나서 위험을 감수하고 시장 보고서를 구매하는 것이 더 편하다는 것을 알게 되었습니다. 보고서의 품질과 고객 서비스에 매우 만족합니다. 처음 보고서를 보고 몇 가지 질문과 의견이 있었지만, 분석가와 이메일로 몇 차례 대화를 나눈 후, 전략 기획 과정에 참고할 수 있는 보고서를 확보했다고 생각합니다. 시간을 내어 긍정적인 경험을 선사해 주셔서 정말 감사합니다. 다른 사람들에게도 귀사의 서비스를 적극 추천할 것이며, 추가적인 시장 데이터가 필요할 때면 가장 먼저 귀사에 연락하겠습니다.
존 스즈키 사장 겸 최고 경영자, 이사회 이사, BK 테크놀로지스
나이지리아 감염성 질환 IVD 시장 관련 정보 요청에 응해 주신 귀사의 지원과 전문성에 감사드립니다. 귀사의 인내심과 지도, 그리고 할인 혜택을 기꺼이 제공해 주셔서 결국 계약을 성사시킬 수 있었습니다. 첫 만남을 통해 귀사가 저에게 심어주신 좋은 인상을 바탕으로 앞으로도 The Insight Partners와 함께할 수 있기를 기대합니다.
치지오케 박사 오니아 전무이사, 파인크레스트 헬스케어 유한회사구매 이유
- 정보에 기반한 의사 결정
- 시장 역학 이해
- 경쟁 분석
- 고객 인사이트
- 시장 예측
- 위험 완화
- 전략 기획
- 투자 타당성 분석
- 신흥 시장 파악
- 마케팅 전략 강화
- 운영 효율성 향상
- 규제 동향에 발맞춰 대응




















 무료 샘플 받기 -