
Antifog Additives Market Trends, Share & Demand by 2034
Coverage: By Type (Glycerol Esters, Polyglycerol Esters, Sorbitan Esters of Fatty Acids, Ethoxylated Sorbitan Esters, Others); Applications (Food Packaging Films, Agricultural Films, Others) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00006081
- Category : Chemicals and Materials
- No. of Pages : 150
- Available Report Formats :


- Last update date : August 27, 2026


2025 Market Size
US$ 2.43 Bn
Base year value
2034 Forecast
US$ 3.66 Bn
Projected by 2034
CAGR 2026-2034
4.64 %
Growth rate
Addressable Market
US$ 27.63 Bn
(2026-2034)
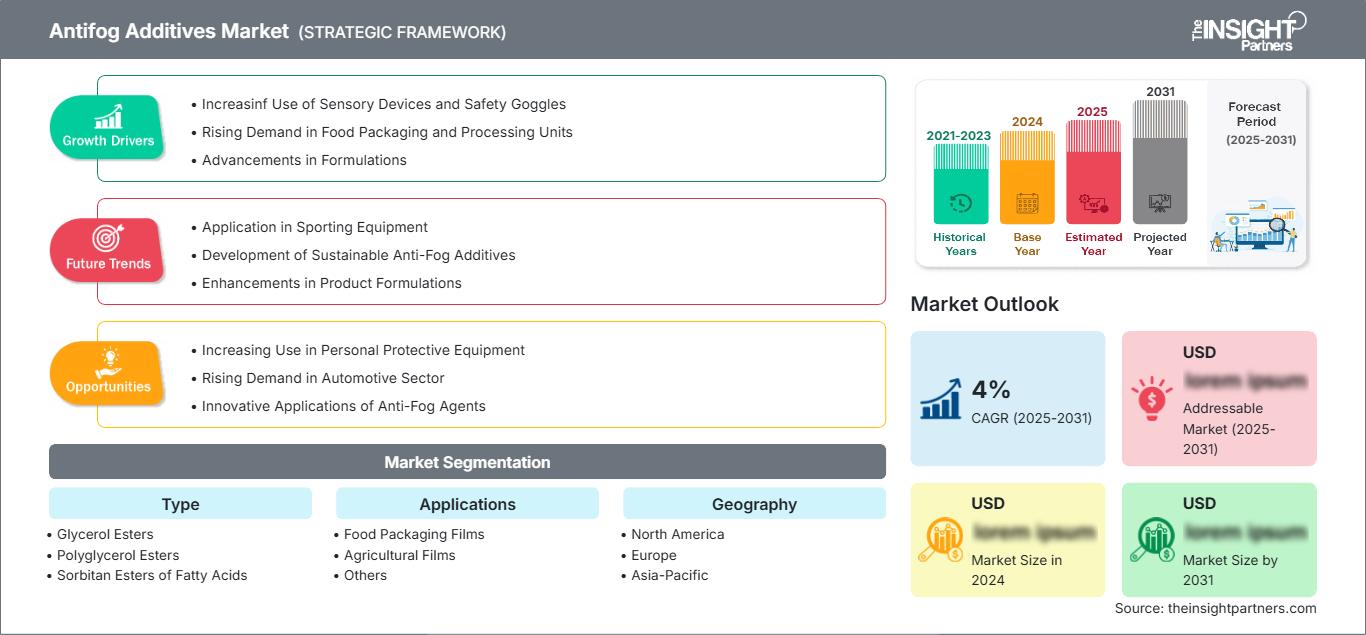
The antifog additives market is valued at US$ 2.43 Billion in 2025 and is projected to reach US$ 3.66 Billion by 2034, expanding at a 4.64% CAGR from 2026 to 2034. Demand is supported by wider use of transparent films, refrigerated food packaging, greenhouse films, and higher-performance multilayer structures requiring controlled condensation. Product development is increasingly focused on food-contact compliance, bio-based feedstocks, low migration, and compatibility with recyclable film architectures.
North America represents a technologically mature demand center, with the antifog additives market size supported by sophisticated flexible-packaging production, refrigerated food distribution, and greenhouse cultivation. The region is estimated to expand at a 4.3–4.8% CAGR during 2026–2034, driven by premium fresh-food packaging, cold-chain requirements, and converter adoption of higher-performance additive concentrates.
Antifog Additives Market Assessment and Insights
- North America: The region is estimated to hold a 22–26% share in 2025 and grow at a 4.3–4.8% CAGR between 2026–2034, supported by food packaging modernization, greenhouse cultivation, and demand for consistent optical performance.
- US: The US represents approximately 75–80% of North America's 2025 demand, growing at a 4.2–4.7% CAGR between 2026–2034, supported by packaged fresh foods and controlled-environment agriculture.
- Europe: Europe is estimated at a 24–28% share in 2025, expanding at a 4.0–4.5% CAGR between 2026–2034, with Germany, Italy, France, Spain, and the UK supporting demand through food packaging and horticultural-film applications.
- Asia Pacific: Asia Pacific is estimated at a 36–40% share in 2025 and a 5.0–5.5% CAGR between 2026–2034, led by China, India, Japan, and South Korea through expanding film conversion and food-processing capacity.
- Largest Segment: Food Packaging Films holds an estimated 64–68% market share in 2025, with a 4.7–5.2% CAGR between 2026–2034, reflecting strong use in refrigerated and fresh-food packaging.
- High Growth Segment: Agricultural Films represents approximately 18–22% market share in 2025, growing at a 5.1–5.6% CAGR between 2026–2034, driven by greenhouse and protected-cultivation applications.
- Key companies analyzed in detail: Ashland Inc.; Clariant AG; Corbion N.V.; Croda International Plc.; Dow Inc.; Evonik Industries AG; Fine Organics Industries Ltd.; Nouryon; PCC SE; Avient Corporation.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The demands of film processing have been evolving towards chemicals that can deliver fast surface migration, wetting and antifog stability across varying temperatures. The use of multilayer and coextruded films in food packaging necessitates an effective additive, which does not impair film sealing, clarity, barrier and mechanical properties. The production environment thus favors concentrated products and the development of chemistries, which are suitable for the process of polyolefin film production.
As far as future needs go, more demand is expected to arise from the Asia Pacific and other developing economies in food processing, where flexible packaging and agricultural protection are gaining importance. Renewable feedstock and food-safe chemistries are also witnessing increasing investment. The trend of increasing scrutiny into packaging materials and demand for recyclability and simplified materials should motivate suppliers to develop antifog chemistries that ensure efficacy in conjunction with monomaterial and recyclable film structures.
Antifog Additives Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 2.43 Billion |
| Market Size by 2034 | US$ 3.66 Billion |
| Global CAGR (2026 - 2034) | 4.64% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Antifog Additives Market Analysis
The antifog additives market growth is closely connected with film production, food processing, agricultural cultivation, and cold-chain logistics. Additive producers make available fatty acid derivatives, glycerol derivatives, sorbitan esters, and polyglycerol esters to the master batch makers and film converters. The formulators of the additives will tailor their products depending on the polymer, processing temperature, migration, fogging, and regulatory considerations.
The value chain starts with vegetable oils, fatty acids, glycerol, and specialty chemical intermediates. They undergo the esterification process, purification, blending, and formulation processes. Films are supplied either via additives that are blended with the resins or through master batching processes. The reliability of supply is affected by the availability of feedstock, oleochemistry prices, capacity issues, and food contact approvals.
The antifog additives market analysis indicates a competitive structure combining multinational specialty-chemical companies with focused oleochemical and additive specialists. Ashland Inc., Clariant AG, Croda International Plc., and Evonik Industries AG bring broad formulation capabilities, while Corbion N.V. and Fine Organics Industries Ltd. provide expertise in renewable and specialty ester chemistries. Avient Corporation competes through masterbatch and polymer-additive integration.
The trend for strategic investment is shifting more and more towards biochemistry, specific grade applications, and multi-functional additives. Dow Inc. and Nouryon leverage their vast network of polymers and chemicals, whereas PCC SE and niche players can leverage their offerings through specific formulation mixes. Product differentiation now hinges on dosage, fogging behavior in both cold and hot fog environments, documentation compliance, extraction resistance, and multilayer structure compatibility.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Antifog Additives Market: Strategic Insights
Regional Insights
North America antifog additives market
North America is estimated to account for 22–26% of the antifog additives market share in 2025, with a growth of 4.3–4.8% CAGR through 2034. Demand is concentrated in the US, followed by Canada and Mexico. Effective transportation of refrigerated foods, produce packaging, greenhouse growing, and flexible film conversion are some of the factors that will help drive additives' use in food and agricultural uses.
Converters in the region are now demanding additives that have the ability to function with temperature cycles rather than additives that can work in static refrigeration environments alone. Areas of demand include multilayer PE/PP films, recyclable packaging formats, and masterbatches. Compliance with food contact requirements as well as packager specifications by retailers is also driving supplier choice. The US is the main regional market for several reasons.
U.S. antifog additives Market
The US represents approximately 75–80% of North America's 2025 antifog additives market, with a 4.2–4.7% CAGR through 2034. Demand comes primarily from fresh produce, meat, dairy, prepared foods, and greenhouse films. Large film converters increasingly require formulations that preserve transparency during refrigerated storage and transportation while remaining compatible with high-speed extrusion.
Companies including Ashland Inc., Dow Inc., and Avient Corporation participate in broader polymer-additive and formulation ecosystems relevant to film applications. Food packaging remains the dominant use, while controlled-environment agriculture creates additional demand for longer-lasting antifog performance. Converter preferences are moving toward internal additives and masterbatches that minimize coating operations, simplify processing, and maintain clarity without adversely affecting sealing or recycling characteristics.
Europe antifog additives Market
Europe is estimated at 24–28% of the Antifog additives market in 2025, expanding at a 4.0–4.5% CAGR. Germany is the leading country, supported by advanced plastics processing, food manufacturing, and packaging machinery. The UK, France, Italy, and Spain provide additional demand through food packaging and horticultural applications.
The UK emphasizes high-visibility fresh-food packaging and retailer-driven sustainability requirements. Germany combines strong film-conversion capabilities with sophisticated recycling and material-efficiency priorities. France, Italy, and Spain have important fresh produce and agricultural-film applications, particularly where greenhouse and protected cultivation are established. European suppliers increasingly emphasize renewable feedstocks, food-contact documentation, lower migration, and compatibility with recyclable structures.
APAC antifog additives Market
APAC holds an estimated 36–40% share of the Antifog additives Market in 2025 and is projected to expand at a 5.0–5.5% CAGR, making it the leading regional market. China is the largest country, followed by Japan, South Korea, India, and Australia. Expanding food processing and flexible-film capacity support demand.
Industrialization, urbanization, cold-chain investment, and protected cultivation are major drivers. China and India provide volume growth through packaging conversion, while Japan and South Korea emphasize high-performance films. Australia contributes through horticulture and fresh produce packaging. Regulatory attention to food-contact materials and recyclable packaging is encouraging suppliers to introduce higher-purity and bio-based formulations.
Middle East & Africa antifog additives Market
The Middle East & Africa Antifog additives Market represents a smaller demand base but is expected to expand at a 4.6–5.1% CAGR. Saudi Arabia is the leading market, supported by food processing and greenhouse investment, while the UAE is developing packaging and controlled-environment agriculture. South Africa remains important for fresh produce and agricultural-film applications.
Energy availability and infrastructure investment support regional polymer conversion, while food-security programs encourage greenhouse cultivation. Rest-of-MEA demand remains fragmented but benefits from imported flexible packaging, agricultural modernization, and expanding food-processing capacity. Suppliers able to provide heat-resistant, long-lasting formulations can address demanding climatic conditions where film temperatures and storage conditions differ substantially from temperate markets.
Segmentation Analysis
Type
The type segment of the Antifog additives Market is expected to expand at a 4.3–5.0% CAGR during 2026–2034. Product selection depends on polymer compatibility, migration behavior, fogging temperature, dosage, regulatory status, and required duration. Glycerol and polyglycerol-based chemistries remain important, while higher-performance formulations target multilayer and recyclable packaging structures. The antifog additives market scope increasingly includes food-contact-compliant and renewable formulations.
- Glycerol Esters: Widely used in PE-based food films because of effective migration and wetting behavior. Their established processing history supports continued use across conventional and recyclable flexible packaging.
- Polyglycerol Esters: Provide strong performance in demanding film structures and can be formulated for hot- and cold-fog conditions. Their versatility supports premium packaging and specialized applications.
- Sorbitan Esters of Fatty Acids: Established antifog chemistry used where controlled surface migration and compatibility with food-contact applications are required. Agricultural films also provide an important outlet.
- Ethoxylated Sorbitan Esters: Offer useful wetting and surface-modification characteristics for selected film formulations. Their future positioning depends increasingly on regulatory acceptance and formulation optimization.
- Others: Include specialized ester and multifunctional chemistries developed for particular polymer systems. Demand is application-specific and typically linked to performance requirements that conventional additives cannot fully satisfy.
Applications
The applications segment of the Antifog additives Market is projected to grow at a 4.4–5.2% CAGR from 2026–2034. Food packaging represents the largest consumption base because transparency directly influences product presentation, while agricultural films require longer-lasting antifog performance under high humidity and temperature cycling. The segment increasingly emphasizes formulations compatible with thinner films and simplified material structures.
- Food Packaging Films: The dominant application, used for fresh produce, meat, dairy, prepared foods, and refrigerated products. Antifogging maintains visibility, supports presentation, and reduces condensation-related quality concerns.
- Agricultural Films: Used in greenhouse and horticultural films to maintain light transmission and reduce water droplets. Demand rises with protected cultivation, crop-intensification programs, and climate-controlled agriculture.
- Others: Covers selected industrial, specialty, and transparent-film uses where condensation affects visibility or performance. Adoption remains application-specific and depends on performance requirements and processing economics.
Opportunity Snapshot
| Applications | Revenue Contribution | Trend Tag | Adoption Stage |
| Food Packaging Films | High | Cold-chain clarity | Mature |
| Agricultural Films | Medium | Greenhouse yield | Scaling |
| Others | Low | Specialty clarity | Emerging |
Antifog Additives Market Growth Drivers and Impact Analysis
Expansion of refrigerated and fresh-food packaging
The development of chilled and fresh food transport and distribution is boosting the demand for film packaging materials, which maintain transparency in situations where temperature changes cause moisture condensation inside the film. Fresh produce, meats, dairy products, and ready-made meals often pass through the process of refrigerated storage before being sold in retail stores, undergoing temperature changes from high to low and vice versa. The antifog additives reduce the risk of forming water droplets on the surface of the film. Therefore, antifog becomes a criterion of performance for the film manufacturers and not just an aesthetic quality. The packaging material suppliers now assess antifog together with other technical parameters such as sealability, oxygen permeability, puncture resistance, and optical qualities.
Growth of protected agriculture and greenhouse cultivation
The protected agriculture segment is also generating a secondary source of demand other than food packaging. Films used in greenhouses and horticulture need controlled condensation since water droplets may interfere with light transmission and generate localized dripping, affecting cultivation. With producers increasing their output per unit of cultivation area, the performance of the films will be key. Antifog additives enable condensation to form into a uniform layer, offering better optical transmission as compared to water droplets. The demand is more significant in Asia, the Middle East, Europe, and North America, where there is an increase in cultivation using greenhouses due to differing climatic regions. Film suppliers that offer longer-lasting additives and in particular those of multilayer films, can serve such demand.
Shift toward food-safe and renewable additive chemistries
Regulations on food-contact properties and sustainability goals are driving the choice of additives within the packaging value chain. Converters now take into account not only antifogging capability, but also the migration potential, toxicity of the additive, its bio-based nature, and compatibility with the recycling process. The use of bio-based glycerol, sorbitan, and polyglycerol esters could offer the possibility of reduced use of non-renewable resources while maintaining the same mechanism needed for the antifog effect. This trend alters the dynamics of the supplier business because traceability and regulations are playing a role in determining purchasing decisions. Companies that have labs for testing and using food contact properties can cut the qualification time for their customers.
Antifog Additives Market Future Trends
Bio-based formulations become mainstream in premium films
The antifog additives market trends are moving toward renewable ester chemistry as packaging producers seek lower fossil content without sacrificing clarity or processing performance. Formulations for the future will blend plant-based raw materials with migration and extraction resistance, in addition to enhanced performance even at lower levels of concentration. Future development will focus on multilayer PE, PP, and polyester films, where regular additives might be less effective or could react with barrier or sealing layers. The range of product grades specific to particular uses, such as hot food, cold food, and greenhouses, is also expected to increase from suppliers. In contrast to the view of plant-based material as a separate sustainable element, renewable additives will be considered by their performance attributes.
Multifunctional additives reduce formulation complexity
Future formulations will increasingly incorporate antifog with antistatic, slip, antiblock, or processing properties. Such a formulation will allow a reduction in the number of masterbatch feeds and simplify the dosage process for film conversion. The importance of multifunctionality will be especially high in the case of multi-layer packaging films, as the amount of additive available will be less here, and also the interaction of additives may influence optical or mechanical properties. It will make sense for suppliers to create concentrates tailored specifically to a particular layer and a particular polymer, and not universal concentrates. Using digital formulations and application testing, additives will be selected more rapidly by matching with the resin type, extrusion parameters, temperature of storage, and film thickness.
Antifog Additives Market Opportunities
Develop specialized solutions for recyclable mono-material films
The antifog additives market Forecasts point to an opportunity for suppliers that can formulate additives specifically for recyclable mono-material PE and PP packaging. As converters reduce multilayer complexity, additive compatibility with the host polymer becomes more important because even small formulation changes can influence sealing, haze, friction, and recycling performance. Suppliers can differentiate by developing low-dose concentrates that maintain antifog performance without creating processing complications or excessive migration. Application laboratories can support qualification through simulated refrigeration, humidity cycling, and shelf-life testing. Partnerships with film producers and packaging converters can accelerate commercialization by validating formulations directly on commercial extrusion lines. Such collaboration also provides a route to application-specific products rather than commodity additives.
Expand high-performance additives for protected agriculture
Agricultural films offer an investment opportunity for suppliers able to address extended service periods, high humidity, ultraviolet exposure, and temperature fluctuations simultaneously. Greenhouse operators increasingly require films that maintain optical performance throughout the crop cycle, creating demand for antifog systems with controlled migration and long-term effectiveness. Product developers can combine antifog chemistry with stabilizer and optical-management technologies while maintaining compatibility with multilayer film structures. Growth opportunities are particularly relevant in regions expanding protected cultivation, including the Asia Pacific and the Middle East. Suppliers that provide technical support for dosage optimization, film testing, and climate-specific performance can strengthen customer retention. Local masterbatch production can further improve responsiveness where agricultural-film converters operate near major horticultural clusters.
Recent Developments
- February 19, 2026: Cosmo First Limited launched a sealable, peelable, transparent anti-fog BOPET lidding film for refrigerated and fresh-food packaging. The film uses an antifog coating on the sealable side to prevent droplet formation and maintain clarity through storage and display, demonstrating increasing use of specialized antifog structures beyond conventional polyolefin films.
- July 7, 2025: Tosaf introduced its FogFree portfolio of antifog masterbatches for demanding packaging applications. The technology is designed to prevent droplet formation by modifying surface tension and creating a uniform water layer, with the company positioning internal masterbatch integration as an alternative to separate surface coatings for packaging structures requiring sustained optical clarity.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for