
Emission Control Catalyst Market Trends, Demand & Growth by 2034
Coverage: By Metal Type (Palladium Platinum, Rhodium, Others); Application (Mobile Sources, Stationary Sources) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00009768
- Category : Chemicals and Materials
- No. of Pages : 150
- Available Report Formats :


- Last update date : August 13, 2026


2025 Market Size
US$ 8.42 Bn
Base year value
2034 Forecast
US$ 11.97 Bn
Projected by 2034
CAGR 2026-2034
3.99 %
Growth rate
Addressable Market
US$ 92.62 Bn
(2026-2034)
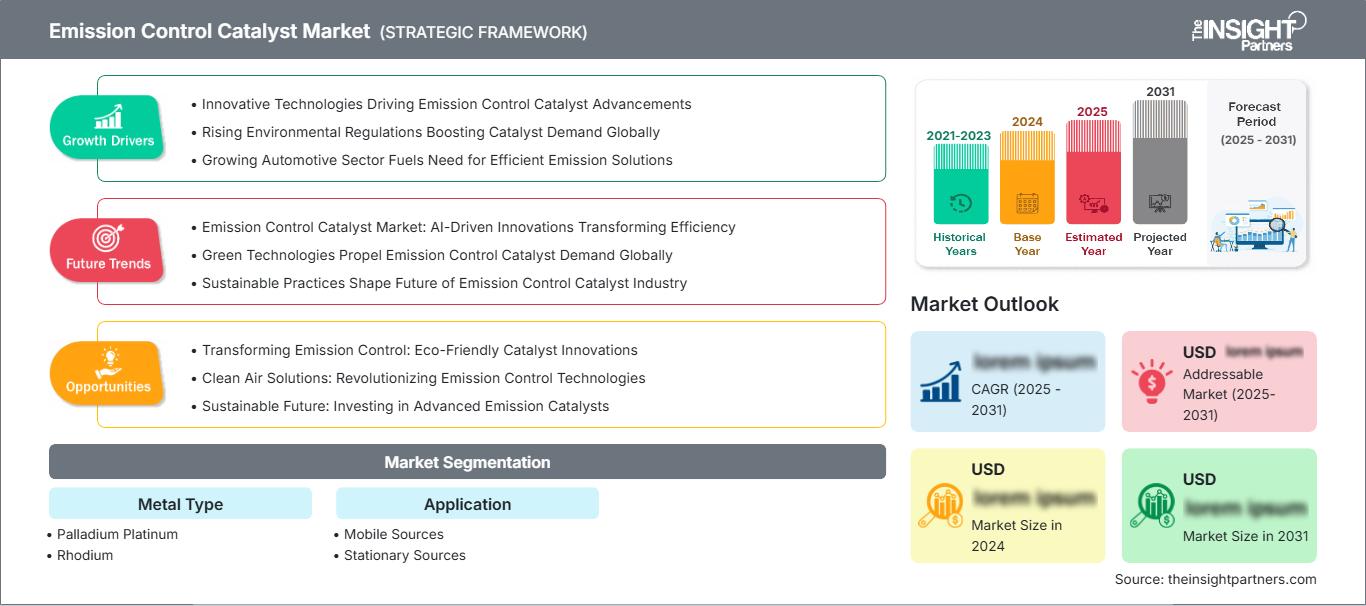
The Emission Control Catalyst Market size was valued at US$ 8.42 Billion in 2025 and is projected to reach US$ 11.97 Billion by 2034, registering a CAGR of 3.99% during 2026–2034. The market growth will be propelled by stringent emissions standards, growing vehicular production, greater use of green transport technologies, and ongoing need for catalytic products for both mobile and stationary emission control applications.
Being fueled by regulatory compliance needs and decarbonization programs implemented by the industry, North America offers a secure market growth prospect for the emission control technologies. It is forecasted that the region’s growth rate will vary between 3.5% and 4.5% annually over 2026-2034.
Emission Control Catalyst Market Assessment and Insights
- North America accounted for an estimated share of 25–29% in 2025 and is projected to grow at a CAGR range of 3.5–4.5% between 2026–2034. The market is supported by regulatory standards, automotive emission controls, and industrial pollution management initiatives.
- US represented an estimated share of 78–84% of the North American market in 2025 and is expected to expand at a CAGR range of 3.6–4.6% during 2026–2034. Demand is driven by vehicle emission regulations and industrial applications.
- Europe held an estimated share of 28–32% in 2025 and is anticipated to grow at a CAGR range of 3.2–4.2% from 2026–2034. Germany, France, the UK, and Italy contribute significantly due to automotive manufacturing and environmental compliance measures.
- Asia Pacific captured an estimated share of 34–38% in 2025 and is forecast to register a CAGR range of 4.2–5.2% between 2026–2034. China, Japan, South Korea, and India are driving regional expansion through vehicle production and industrial development.
- Largest Segment Mobile sources represented the leading application segment with an estimated market share of 65–70% in 2025 and a CAGR range of 3.8–4.8% during 2026–2034.
- High Growth Segment Stationary sources are expected to demonstrate stronger expansion, accounting for an estimated market share of 30–35% in 2025 and growing at a CAGR range of 4.0–5.0% during 2026–2034.
- Key companies analyzed in detail: BASF SE, Johnson Matthey Plc, Solvay SA, Umicore NV/SA, Corning Incorporated, Clariant AG, Topsoe A/S, Aerinox Inc., Clean Diesel Technologies, Inc., DCL International Inc.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The Emission Control Catalyst has witnessed notable technological developments owing to the efforts of catalyst manufacturers in terms of enhancing their efficiency, durability, and compatibility with emission standards. Innovations in the formulation of precious metals, substrates, and catalyst coatings have helped in boosting the performance of emission control catalysts in various applications including automobiles and industries. There has been an increase in efficient use of materials in innovative designs that help in maintaining emission control efficiency along with coping with cost issues arising due to the use of platinum group metals.
Future development of the Market is anticipated to be driven by rising environmental regulations, increase in automobile fleet in emerging markets, and investments in eco-friendly technologies in industries. Growing opportunities in the market can be seen in Asia Pacific and emerging markets owing to the strengthening of emission control infrastructure. Air quality regulations and technological upgradation in industries are expected to drive demand for such catalysts.
Emission Control Catalyst Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 8.42 Billion |
| Market Size by 2034 | US$ 11.97 Billion |
| Global CAGR (2026 - 2034) | 3.99% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Emission Control Catalyst Market Analysis
The growth of the Emission Control Catalysts market is mainly driven by the rising regulatory push against emissions from transportation and industries. Governments across the world are enforcing more stringent regulations on nitrogen oxides, carbon monoxide, hydrocarbons, and particulates to encourage the use of catalytic conversion technology. The ecosystem comprises of precious metal providers, catalyst makers, substrate providers, automobile original equipment manufacturers, industrial equipment makers, and the end customers. The supply dynamics are shaped by the supply of platinum group metals, the recycling process, and technological developments.
The catalyst makers have been developing new catalysts that enhance the efficiency of conversion while lowering the requirement of costly raw materials. The demand from the automotive industry will be one of the biggest driving forces behind the market growth due to increased production of vehicles. Besides, there has been an expansion in the demand from the industrial segment as power generation companies, manufacturing plants, and chemical processing plants use these products.
Market analysis for Emission Control Catalysts shows that competitive environment is driven by innovation, management of precious metals and development of catalysts tailored for certain applications. Leading companies, BASF SE, Johnson Matthey Plc, Umicore NV/SA and Corning Incorporated, invest in advanced catalyst technologies and manufacturing processes in order to cope with the changes in regulations. Customized emission control catalyst companies such as Clean Diesel Technologies, Inc., DCL International Inc. and Aerinox Inc. enhance their competitive advantage through customization of the emission control solutions.
The increasing investments are directed towards improving catalyst efficiency, developing of alternatives to metals and capabilities of material recycling. The cooperation of catalyst manufacturers with automobile manufacturers and industrial technology firms drives innovation in the market. Companies differentiate through research capabilities, manufacturing facilities all over the world and regionally customized solutions.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Emission Control Catalyst Market: Strategic Insights
Regional Insights
North America Emission Control Catalyst Market
North America is expected to hold 25-29% of the Emission Control Catalyst Market share in 2025, which is further estimated to grow at a compound annual growth rate of 3.5%-4.5% during the forecast period 2026-2034. The presence of developed automotive industry, emission regulations, and regular investments in industrial emission control equipment are some of the factors that drive the market in the region.
The US forms the major contributor in the region owing to vehicle emission standards, industrial upgrading, and growing demand for applications in heavy-duty transportation sector. Canada and Mexico act as the contributors to the market in the region through their respective automotive manufacturing operations and emission management in the industries. Increased awareness about greenhouse gas emission reduction and improvement in air quality drives the use of efficient catalysts.
U.S. Emission Control Catalyst Market
The U.S. Market represented an estimated 78–84% share of North America in 2025 and is expected to grow at a CAGR range of 3.6–4.6% during 2026–2034. The country maintains a strong position due to advanced automotive production, established regulatory frameworks, and extensive adoption of emission reduction technologies across transportation and industrial sectors.
Companies like BASF SE, Johnson Matthey Plc, and Corning Incorporated provide local expertise for innovations in catalyst technology and availability. The demand is affected by emission regulations for gasoline and diesel vehicles, requirements for heavy-duty vehicles, and the use of pollution control devices for industries. Growing investment in green mobility and industry facility upgrades will fuel the market growth in the future.
Europe Emission Control Catalyst Market
Europe accounted for an estimated share of 28–32% of the Market in 2025 and is projected to grow at a CAGR range of 3.2–4.2% between 2026–2034. Germany leads regional demand due to its automotive manufacturing base, environmental regulations, and strong presence of catalyst technology providers. The UK, France, Italy, and Spain are also contributing through transportation and industrial applications.
There are emission reduction initiatives, commercial vehicle policies, and industrial air quality policies that help in the growth of the UK market. Germany has the highest share in the market because of its manufacturing and advanced engineering skills. France, Italy, and Spain have demand from passenger cars, industrial products, and energy applications. The regulation of low emission from vehicles and industries in Europe encourages investments in efficient catalysts.
APAC Emission Control Catalyst Market
The APAC region was valued at 34-38% of the market for Emission Control Catalysts in 2025 and has a projected CAGR of 4.2-5.2% during 2026-2034. The region has seen considerable growth in this market because of the increase in vehicles and industrialization.
China is the major contributing region as a result of the production of vehicles and industry expansion. Japan and South Korea aid in the growth of demand due to technological development in automobiles. Increasing demand in India and Australia as a result of rising numbers of cars, industrialization, and environmental improvement activities makes them emerging regions. Government regulations on emission reduction and greener modes of transportation are driving the use of catalysts.
Middle East & Africa Emission Control Catalyst Market
The Middle East & Africa Market is estimated to hold a smaller share in 2025 and is projected to expand at a CAGR range of 3.0–4.0% during 2026–2034. Saudi Arabia leads regional demand through energy sector modernization, industrial projects, and transportation emission management initiatives. The UAE is also contributing through infrastructure development and cleaner technology adoption.
South Africa continues to be a significant market owing to mining activities, industrial activities, and transportation needs. Countries under RoMEA are steadily increasing their investment in emission control technology because of environmental legislations. Construction of infrastructure related to energy sector, industries, and transportation is anticipated to increase the demand for catalysts in the region.
Segmentation Analysis
Metal Type
Metal Type is a critical segment of the Emission Control Catalyst Market and is expected to grow at a CAGR range of 3.5–4.5% during 2026–2034. Precious metals remain essential for catalyst performance due to their high activity, durability, and ability to support chemical conversion reactions. Manufacturers are focusing on optimized formulations and recycling methods to manage raw material costs while maintaining efficiency.
- Palladium Platinum materials are widely used in catalyst formulations due to their effectiveness in reducing harmful emissions from vehicle exhaust systems. Demand is supported by automotive applications requiring reliable conversion performance and regulatory compliance.
- Rhodium remains important for nitrogen oxide reduction applications because of its high catalytic efficiency. Its strategic importance is linked to advanced emission control systems used in gasoline and heavy-duty vehicle technologies.
Application
Application segment is projected to register a CAGR range of 3.8–4.8% during 2026–2034. Increasing regulatory requirements across transportation and industrial sectors are driving adoption of catalyst technologies. The segment benefits from rising vehicle production, industrial emission management, and investments in cleaner technologies. The Emission Control Catalyst Market scope continues expanding as industries seek efficient solutions for reducing pollutant emissions.
- Mobile Sources represent the largest application area due to extensive use in passenger vehicles, commercial vehicles, and heavy-duty transportation systems. Increasing emission standards and vehicle electrification strategies continue influencing catalyst demand.
- Stationary Sources are gaining importance through applications in power plants, industrial facilities, and manufacturing operations. Growing emphasis on industrial air quality management is supporting adoption of stationary emission control systems.
Opportunity Snapshot
| Application | Revenue Contribution | Trend Tag | Adoption Stage |
| Mobile Sources | High | Vehicle Emissions | Mature |
| Stationary Sources | Medium | Industrial Control | Scaling |
Emission Control Catalyst Market Growth Drivers and Impact Analysis
Stringent Global Emission Regulations
Increasingly strict emission standards implemented by governments and environmental agencies are creating sustained demand for advanced catalyst technologies. Regulations targeting nitrogen oxides, carbon monoxide, hydrocarbons, and particulate emissions are encouraging automotive manufacturers and industrial operators to adopt efficient emission reduction systems. Regulatory frameworks across North America, Europe, and Asia Pacific are influencing product development strategies and accelerating investments in catalyst research. Vehicle manufacturers are required to integrate advanced after-treatment systems to comply with evolving standards, while industrial facilities are upgrading pollution control equipment. These regulatory changes are improving adoption of high-performance catalyst solutions and encouraging manufacturers to develop products with enhanced conversion efficiency and longer operating life.
Increasing Vehicle Production and Transportation Demand
Growing global vehicle production and increasing demand for commercial transportation are contributing significantly to catalyst adoption. Passenger vehicles, heavy-duty trucks, and commercial fleets require emission control systems to meet regulatory requirements and improve environmental performance. Emerging economies are witnessing higher vehicle ownership rates, creating additional demand for catalyst-equipped transportation systems. The expansion of logistics, freight transportation, and urban mobility networks is further supporting the requirement for emission reduction technologies. Automotive manufacturers are focusing on optimized catalyst designs that provide effective pollutant conversion while maintaining fuel efficiency. This trend is encouraging technology providers to invest in advanced formulations and manufacturing capabilities to serve evolving transportation requirements.
Industrial Adoption of Air Pollution Control Technologies
Industrial facilities are increasingly implementing emission control technologies to comply with environmental regulations and improve operational sustainability. Power generation plants, chemical processing facilities, manufacturing units, and other industrial operations require effective solutions for controlling harmful emissions. Growing awareness of air quality management and regulatory enforcement is encouraging investments in stationary emission control systems. Catalyst technologies are being integrated into industrial processes to reduce pollutants and support cleaner production methods. The expansion of industrial infrastructure in developing economies is creating additional opportunities for catalyst suppliers. Companies are focusing on durable solutions capable of operating under high-temperature and challenging industrial conditions to meet diverse application requirements.
Emission Control Catalyst Market Future Trends
Development of Low Precious Metal Catalyst Technologies
The technology development in the Emission Control Catalyst Market Treands is expected to focus on reducing dependence on expensive precious metals while maintaining catalyst performance. Manufacturers are investing in advanced formulations, optimized catalyst structures, and improved material utilization techniques to lower production costs. Research activities are increasingly centered on enhancing metal dispersion, improving conversion efficiency, and extending catalyst lifespan. These innovations are important as industries seek cost-effective emission control solutions amid fluctuations in platinum group metal prices. Automotive and industrial users are expected to increasingly adopt optimized catalyst technologies that balance regulatory performance with economic considerations. The shift toward efficient material usage will influence future product strategies and encourage collaboration between catalyst developers and end users.
Integration with Hybrid and Alternative Powertrain Systems
The evolution of hybrid vehicles and alternative powertrain technologies is expected to influence future catalyst development requirements. Although electrification is expanding, internal combustion engines and hybrid systems are expected to remain relevant across several transportation segments, particularly commercial vehicles and long-distance applications. Catalyst manufacturers are developing solutions designed for changing exhaust characteristics, lower operating temperatures, and improved efficiency. Future systems may require advanced catalyst designs capable of supporting diverse fuel technologies and evolving vehicle architectures. This trend will encourage manufacturers to enhance product adaptability and develop emission control solutions suitable for next-generation transportation platforms while maintaining compliance with increasingly stringent environmental standards.
Emission Control Catalyst Market Opportunities
Expansion of Emission Control Infrastructure in Emerging Economies
Developing economies present significant opportunities due to increasing vehicle ownership, industrialization, and implementation of stricter environmental regulations. Countries across Asia Pacific, Latin America, and the Middle East are investing in transportation infrastructure and industrial modernization, creating demand for emission control technologies. Companies can expand their presence by establishing local manufacturing capabilities, developing regional partnerships, and offering solutions tailored to local regulatory requirements. The Emission Control Catalyst Market Forecasts indicate that emerging markets will remain important areas for future investment as governments strengthen air quality initiatives. Suppliers focusing on cost-effective technologies and localized support services can benefit from increasing adoption across automotive and industrial sectors.
Growth Potential in Industrial Emission Reduction Applications
Industrial emission reduction initiatives provide opportunities for catalyst manufacturers to expand beyond transportation applications. Power generation facilities, chemical plants, and manufacturing industries are increasingly investing in pollution control systems to meet environmental standards. Companies developing durable catalyst solutions for high-temperature and continuous operation environments can address growing industrial requirements. Strategic collaborations with industrial equipment providers and energy companies can support broader market penetration. Increasing focus on sustainable industrial practices is expected to create demand for advanced stationary source technologies. Manufacturers that combine technical expertise with application-specific solutions may strengthen their competitive position in industrial emission management markets.
Recent Developments
- July 2026: Honeywell Technologies has completed its acquisition of Johnson Matthey’s Catalyst Technologies business for £1.325 billion in cash. This acquisition enhances Honeywell's portfolio in refining, petrochemicals, and renewable fuels, providing a more comprehensive offering in energy and process technologies, alongside existing automation and digital solutions. It expands the global installed base and improves service capabilities across various applications, reaffirming Honeywell's commitment to integrated solutions that drive operational excellence and efficiency in the industrial value chain.
- April 2026: Evonik has introduced advanced isodewaxing catalysts to enhance the production of high-quality fuels and lubricants. This innovation combines Zeopore's mesoporized zeolite system with Evonik's extensive catalyst and metal expertise. The new catalyst platform aims to improve product yields, fuel quality, and operational efficiency for refiners and renewable fuel producers. Key features include a redesigned zeolite structure that optimizes porosity, facilitating better access to active sites, enhancing isomerization reactions, and minimizing unwanted cracking..
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners provided valuable market intelligence that supported our global go-to-market strategy. Their team was professional, responsive, and attentive to our feedback, providing thoughtful analysis and helpful methodological clarifications throughout the project.
Junmo Kim Chief Financial Officer (CFO), Enertech Co., Ltd.
The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for