
Flexible Plastic Pouches Market Trends, Size & Forecast by 2034
Coverage: By Material (Polyethylene, Polypropylene, Others); Type (Flat Pouches, Stand-up Pouches); Application (Food and Beverages, Personal Care and Home Care, Health Care, Others) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00025666
- Category : Chemicals and Materials
- No. of Pages : 150
- Available Report Formats :


- Last update date : October 30, 2026


2025 Market Size
US$ 220 Bn
Base year value
2034 Forecast
US$ 305.37 Bn
Projected by 2034
CAGR 2026-2034
3.71 %
Growth rate
Addressable Market
US$ 2,386.09 Bn
(2026-2034)
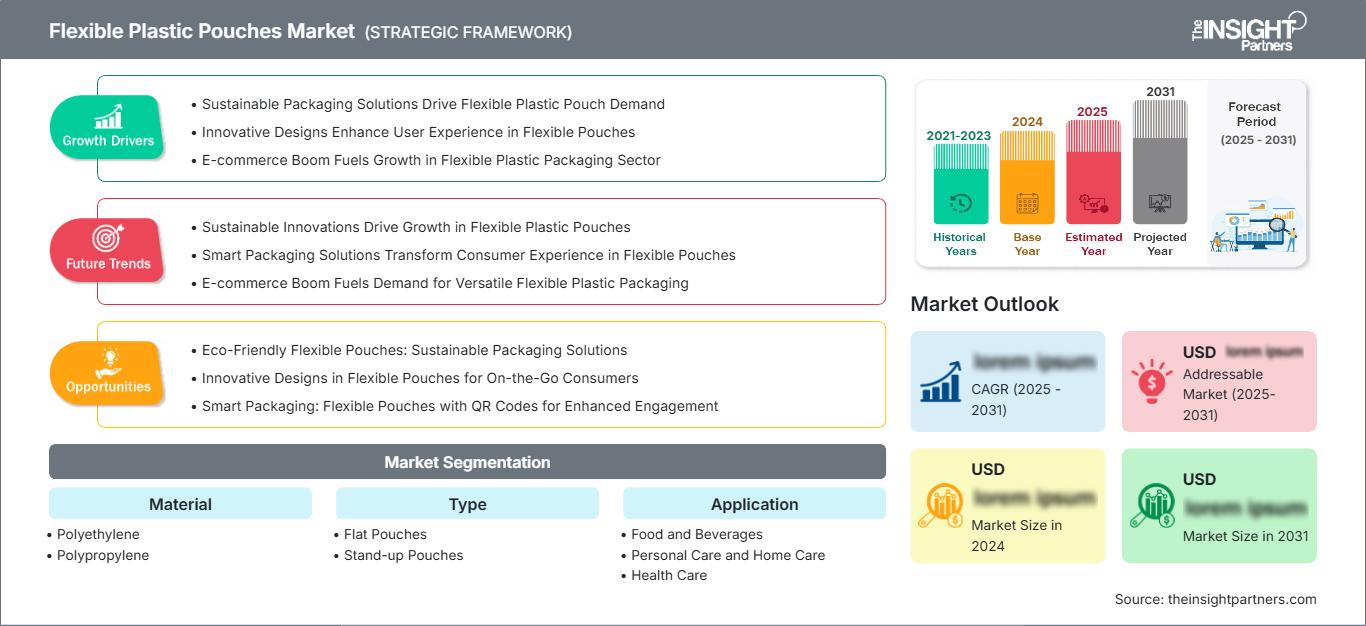
The flexible plastic pouches market reached US$ 220 Billion in 2025 and is projected to reach US$ 305.37 Billion by 2034, with a mathematically aligned CAGR of 3.71% during 2026–2034. Demand is supported by lightweight packaging, material efficiency, convenience-oriented formats, extended product protection, and expanding applications across food, beverages, personal care, home care, and health care. Advances in recyclable polyethylene and polypropylene structures are also influencing converter investment and brand-owner packaging strategies.
North America flexible plastic pouches market size is expected to expand at approximately ~3% CAGR through 2034, supported by established flexible-packaging infrastructure, high penetration of packaged foods, and continued conversion from rigid formats where lightweighting and logistics efficiency provide economic benefits. Recyclability requirements and retailer packaging commitments are also encouraging converters to redesign pouch structures around compatible polymer streams and improved material efficiency.
Flexible Plastic Pouches Market Assessment and Insights
Regional Outlook
- North America: ~22% of the global market in 2025 | ~3% CAGR through 2034. Market position: North America represents a mature regional market supported by established food, beverage, personal care, and household-product packaging demand. Converter capabilities, retail penetration, and investment in recyclable structures sustain its substantial market position.
- US: ~82% of North American market revenue in 2025 | ~3% CAGR through 2034. Market position: The US represents the largest country market in North America, supported by sophisticated converting infrastructure, extensive packaged-food consumption, strong private-label activity, and growing requirements for lightweight and recycling-compatible flexible packaging.
- Europe: ~23% of the global market in 2025 | ~3% CAGR through 2034. Market position: Europe is a mature market where packaging-waste requirements, circular-material targets, and demand for recyclable structures influence purchasing decisions. Germany is the leading country in Europe, followed by substantial demand from the UK, France, Italy, and Spain.
- Asia Pacific: ~41% of the global market in 2025 | ~5% CAGR through 2034. Market position: Asia Pacific is the largest and fastest-growing regional market, supported by packaged-food consumption, urbanization, manufacturing expansion, and rising modern-retail penetration. China is the leading country in Asia Pacific, with India providing substantial incremental demand.
Segment Outlook
- Food and Beverages: ~52% Share in 2025 | ~4% CAGR through 2034. Market position: Food and beverages lead because pouches combine barrier protection, low packaging weight, efficient transportation, portion flexibility, and convenient handling. Strong demand for processed foods, snacks, sauces, ready meals, and beverage formats reinforces the segment.
- Stand-up Pouches: ~40% Share in 2025 | ~5% CAGR through 2034. Market position: Stand-up formats benefit from shelf visibility, resealability, efficient product dispensing, and compatibility with increasingly lightweight structures. Their adoption is expanding across food, household products, personal care, and selected health care applications.
Competitive Coverage
Amcor plc, B and A Packaging India Ltd., Constantia Flexibles, Goglio SpA, Huhtamaki Oyj, Mondi plc, ProAmpac, Sonoco Products Company, UFlex Limited, Sealed Air Corporation
Methodology
The Insight Partners follows Data Collection & Secondary Research, Primary Research, Data Analysis, and Data Triangulation & Final Review to validate market estimates and insights.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
Packaging manufacture has moved away from traditional multi-layer structures towards lightweight film, superior sealants, better barrier properties, and polymeric materials that lend themselves to recyclability. Polyethylene continues to play an important role due to its flexibility, sealability, moisture-resistance, and wide range of converting capability, while polypropylene is used in cases that need greater heat-resistance and dimensional capability. Digital printing, better gravure and flexographic printing technology, down gauging, and lamination are helping converters achieve a balance between appearance, barrier capability, processability, and use of material.
From 2022 to 2034, investments are expected to focus on recyclable mono-materials, high barrier polymer solutions, refills, and manufacturing solutions that can handle smaller batches and offer greater flexibility. New markets in Asia will continue to be relevant since food packaging penetration and organized retailing is growing from a relatively low base. In Europe and North America, regulations pertaining to packaging waste and recyclability may determine material choice and investments in converters.
Flexible Plastic Pouches Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 220 Billion |
| Market Size by 2034 | US$ 305.37 Billion |
| Global CAGR (2026 - 2034) | 3.71% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Flexible Plastic Pouches Market Analysis
Demand includes applications where there is need of protection for the contents while at the same time keeping the package light and the logistics requirement minimized. Industries such as food processors, home goods manufacturers, personal care products industries, and health care companies usually judge pouch constructions in terms of their barrier properties, seal strength, processibility, shelf impact, and end-of-life issues. The value chain in the flexible plastic pouches market involves polymer suppliers, film converters, printers, laminators, pouch makers, filling machinery suppliers, brand owners, retailers, and recyclers.
Supply aspects are still influenced by polyethylene and polypropylene supply conditions, resin price changes, film conversion capacity, printing capacity, and plant location within the region. While big converters can have some cost advantages in film extrusion, printing, laminating, and procurement of materials, niche converters can differentiate themselves using structure uniqueness, small batch production, technical barriers, and pouches made for specific applications.
According to the flexible plastic pouches market report, the level of competitiveness will depend upon the global competitors who have a broad geographic presence and regional competitors who have a strong customer relationship. Competitors like Amcor plc, Constantia Flexibles, Mondi plc, Huhtamaki Oyj, ProAmpac, Sonoco Products Company, and Sealed Air Corporation work on the basis of material science, converting technology, sustainable structure, and wide applications. Uflex Limited and B & A Packaging India Ltd provide support to the competitive scenario through regional manufacturing and converting, while Goglio SpA is still relevant for its flexible packaging applications.
Strategic investments will now be directed towards structures that have recyclable materials, superior performance of PE and PP films, digital printings, automation and production capacity located near consumer goods manufacturing clusters. Strategic positions for companies will be determined by their capability to offer complete packaging solution, and not just one element like film or pouch.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Flexible Plastic Pouches Market: Strategic Insights
Regional Insights
North America Flexible Plastic Pouches Market
Demand from North America is estimated at about ~22% of the world total in 2025 and is set to show a ~3% CAGR to 2034. Factors include the presence of an advanced packaged foods industry, mature retail channels, extensive flexible film converting facilities, and established demand for lightweight packaging. Packaging pouches have special significance in cases where there is a requirement for light-weight packaging, transportation ease, resealing properties, and attractive shelf display without changing filling line economics.
The main source of demand is the US, and Canada and Mexico add their contributions in terms of processed foods, consumer goods, and manufacturing. The competition dynamics are increasingly being impacted by the use of sustainable materials such as recyclable PE/PP constructions, downgauging, and post-consumer recycled content approaches. There are also pressures for the adoption of packaging formats which are capable of meeting evolving sustainability needs. This is favorable for sustained but not radical growth, with expansion derived mainly through format substitution.
U.S. Flexible Plastic Pouches Market
The US accounts for about ~82% of North American flexible plastic pouches market share in 2025 and is expected to grow at a ~3% CAGR until 2034. Growth drivers include significant quantities of packaged foods, well-established production of private-label brands, high consumption of convenience foods, and active participation of international players in packaging conversion.
Major players of the US competitive landscape are Amcor plc, ProAmpac, Sonoco Products Company, and Sealed Air Corporation, as well as local converters. Areas of innovation focus on development of recycled polymer structures, improved barriers, resealable closures, and downgauged films. The importance of food and beverages sector is linked to ability of pouches to package sauces, snacks, processed foods, pet food, etc. E-commerce sector drives need for packaging that is light and provides protection to products.
Europe Flexible Plastic Pouches Market
Europe comprises around ~23% of the flexible plastic pouches market share in 2025 and is anticipated to exhibit a ~3% CAGR during 2034. Germany is the key country in Europe and is bolstered by a well-established manufacturing industry, advanced food-processing industry, and excellent packaging conversion capability. The UK also has considerable demand in food, household, personal care, and retail applications, whereas France and Italy have demand generated through branded consumer products, food processing, and packaging manufacturing. Spain has benefited from packaged food, beverages, and consumer product manufacturing.
Packaging waste minimization, recyclability, material efficiency, and circularity are important for European demand. These factors will make converters change structure designs but still retain barrier properties and fill line compatibility. Constantia Flexibles, Mondi plc, Huhtamaki Oyj, Goglio SpA, and Amcor plc have considerable regional presence through flexible packaging technology and customer base.
Throughout the area, buyers are looking at the packaging system as a whole and not just considering the cost of the pouches. Compatibility, recyclability, weight reduction, printing, protection, and supply have become important considerations in buying decisions. The presence of a strong clientele for industrial and food processing in Germany along with the packaging machinery sector in Italy makes it easier to grow.
APAC Flexible Plastic Pouches Market
Asia Pacific represents approximately ~41% of the global market in 2025 and is expected to expand at a ~5% CAGR through 2034, making it the fastest-growing regional market in this assessment. China is the leading country in Asia Pacific, supported by large-scale food processing, consumer-product manufacturing, packaging production, and extensive polymer-conversion capacity. India is also gaining importance as packaged-food penetration, organized retail, and domestic manufacturing expand.
Both Japan and South Korea have been contributing with their packaging applications and high quality consumer products, whereas there is already demand from Australia in the categories of food, household, and personal care. The regional investments are being made towards lightweight films, recyclable PE and PP structures, automation, and pouch conversion at high speeds. Urbanization and penetration of packaged consumer goods in the region have widened the scope of demand.
Middle East & Africa Flexible Plastic Pouches Market
Middle East & Africa is projected to register approximately ~5% CAGR through 2034. Saudi Arabia and the UAE represent important Middle Eastern demand centers because of food processing, consumer-goods distribution, retail modernization, and investments in domestic manufacturing. South Africa provides a significant African packaging base through established food, beverage, personal care, and household-product industries, while Rest of MEA contributes through developing consumer markets.
Energy availability and petrochemical integration give the region a structure-based advantage in the manufacturing and conversion of polymers. Infrastructural investments, food security initiatives, local production projects, and the rise in modern retail are facilitating the acceptance of pouches. The suppliers now consider their regional manufacturing footprint since regional conversion offers them reduced logistics costs and better response to their food and consumer goods customers.
Segmentation Analysis
Material
Material selection determines flexibility, sealing behavior, barrier performance, durability, processing requirements, and recyclability. Polyethylene remains the principal material platform because of its broad film-conversion compatibility and suitability for lightweight packaging. Polypropylene provides complementary performance where thermal resistance and stiffness are important. Within this category, Polypropylene segment in the flexible plastic pouches market is expected to record a ~5% CAGR during 2026–2034, supported by demand for higher-performance packaging structures and recyclable polymer solutions.
- Polyethylene: Polyethylene is widely adopted because it combines flexibility, moisture resistance, sealability, and cost efficiency. Its compatibility with mono-material pouch structures also supports applications where recyclability and downgauging are increasingly important procurement considerations.
- Polypropylene: Polypropylene provides higher temperature resistance and stiffness than many polyethylene structures. It is relevant for packaging exposed to demanding filling or sterilization conditions and for applications requiring dimensional stability and robust sealing performance.
Type
Type selection reflects consumer handling, shelf presentation, filling requirements, closure needs, and product dispensing characteristics. The segment in the remains divided between formats optimized for straightforward, space-efficient packaging and formats designed to provide stronger shelf presence and consumer convenience. Within this category, Stand-up Pouches in the flexible plastic pouches market are expected to register a ~5% CAGR during 2026–2034, supported by resealability, product visibility, portability, and expanding applications beyond traditional food packaging.
- Flat Pouches: Flat pouches provide efficient material utilization, compact storage, and straightforward manufacturing. They remain relevant for products where shelf footprint, low packaging weight, and economical filling are more important than upright presentation or advanced dispensing functionality.
- Stand-up Pouches: Stand-up pouches provide improved shelf visibility and can accommodate zippers, spouts, handles, and other convenience features. Their ability to combine functionality with lightweight construction supports increasing use across food, household, personal care, and selected health care products.
Application
Application requirements in the flexible plastic pouches market determine the balance between barrier protection, package integrity, convenience, appearance, regulatory compliance, and filling performance. Food and beverages represent the largest demand pool because pouch formats can address diverse packaged-product requirements while supporting efficient transportation and storage. Within this category, Food and Beverages is expected to record a ~4% CAGR during 2026–2034, supported by packaged-food penetration and continued conversion toward convenient formats.
- Food and Beverages: Food and beverage packaging uses pouches where product protection, shelf life, portability, resealability, and efficient transportation are important. The format accommodates a broad range of processed and packaged products and supports both mass-market and premium positioning.
- Personal Care and Home Care: Personal and household products increasingly use pouches for refill, dispensing, concentrate, and everyday-use formats. Their lightweight construction can reduce packaging material and transportation requirements while enabling differentiated graphics and functional closures.
- Health Care: Health care applications require controlled barrier performance, seal integrity, hygiene, and dependable packaging consistency. Pouches are relevant for products where lightweight construction must be combined with protection against moisture, contamination, and handling-related damage.
Opportunity Snapshot
| Application | Revenue Contribution | Trend Tag | Adoption Stage |
|---|---|---|---|
| Food and Beverages | High | Convenience Foods | Mature |
| Personal Care and Home Care | Medium | Refill Formats | Scaling |
| Health Care | Medium | Barrier Protection | Scaling |
Flexible Plastic Pouches Market Growth Drivers and Impact Analysis
Lightweighting and Material Efficiency in Consumer Packaging
Lightweighting remains a fundamental commercial driver because pouch structures can deliver product protection using less packaging material and lower transportation weight than many rigid alternatives. The impact is strongest in high-volume consumer categories where packaging weight affects procurement costs, logistics efficiency, pallet utilization, and distribution economics. Converters are responding through film downgauging, improved sealant systems, higher-strength polymer structures, and process optimization. For brand owners, the commercial value extends beyond material reduction because lighter packages can support improved handling and storage. The resulting demand encourages investment in extrusion, printing, lamination, and pouch-making equipment capable of maintaining package performance while reducing material intensity. This mechanism supports steady adoption across food, household products, personal care, and selected health care applications.
Convenience Packaging and Changing Consumption Patterns
Consumer demand for portability, resealability, portion control, easy dispensing, and compact storage is expanding the functional role of pouches. Stand-up configurations can provide shelf visibility while incorporating zippers, spouts, handles, and tear features suited to specific product categories. These characteristics are particularly relevant as food consumption becomes more convenience-oriented and household products increasingly use concentrated or refill formats. For manufacturers, pouches can also simplify package handling and support differentiated product presentation. The commercial impact extends to retail because flexible packages can use shelf space efficiently and create strong visual differentiation through printing. As brands seek packaging that combines convenience with lower material use, pouch formats gain opportunities in categories traditionally dominated by bottles, jars, cartons, and other rigid containers.
Recyclability Requirements and Polymer-Compatible Packaging Design
Recycling objectives are changing the technical criteria used to design flexible pouches. Traditional multilayer constructions can provide excellent barriers but may complicate recycling when incompatible materials are combined. This challenge is driving development of mono-material PE and PP structures, improved barrier coatings, compatible sealants, and designs that preserve performance while simplifying end-of-life processing. The flexible plastic pouches market impact is significant because converters must balance recyclability with oxygen and moisture barriers, puncture resistance, heat-sealing performance, filling-line compatibility, and shelf life. Investment therefore increasingly targets material science and process engineering rather than pouch conversion alone. Suppliers capable of demonstrating performance under real production conditions can gain access to customers seeking packaging redesigns driven by corporate sustainability commitments and evolving packaging regulations.
Flexible Plastic Pouches Market Future Trends
Expansion of Recyclable Mono-Material Pouch Platforms
Through 2034, recyclable mono-material architectures are likely to become increasingly important in pouch development as brands and converters seek packaging structures that better align with evolving recycling systems. The technical challenge is to preserve the barrier performance historically achieved through combinations of different polymers, aluminum, adhesives, and coatings while simplifying the material structure. This will encourage innovation in high-barrier PE and PP films, coatings, sealants, and orientation technologies. Product developers are likely to prioritize application-specific structures rather than a single universal pouch design. Food, personal care, and household products will provide important testing grounds because these categories require a combination of shelf life, appearance, machinability, and convenience. Commercial adoption will depend on demonstrated recycling compatibility and reliable performance on existing filling equipment.
Refillable and Reuse-Oriented Pouch Formats
Refill packaging is positioned to become an increasingly important extension of pouch functionality, particularly in personal care and home care. Rather than replacing the primary container, a flexible pouch can serve as a lower-material refill that transfers product into a durable dispenser or reusable package. This model changes pouch design requirements because ease of pouring, controlled dispensing, leak prevention, and consumer handling become central considerations. Manufacturers are likely to develop spouted, resealable, and ergonomic structures tailored to repeat purchasing cycles. The flexible plastic pouches market trends extends beyond sustainability positioning because concentrated products and refill systems can reduce transportation requirements and increase product density. Adoption will vary by category and geography, with stronger potential where consumers already accept refill behavior and retailers can provide suitable merchandising systems.
Flexible Plastic Pouches Market Opportunities
Localized Production for High-Growth Consumer Markets
Packaging suppliers can capture growth by establishing or expanding pouch-conversion capacity close to fast-growing food, personal care, home care, and health care manufacturing clusters. Localized production can reduce lead times, lower exposure to long-distance freight, and enable converters to adapt structures to regional filling equipment and regulatory requirements. Asia Pacific provides particularly relevant opportunities because expanding packaged-food and consumer-goods manufacturing can create demand for both high-volume standard pouches and customized formats. India and Southeast Asia can support capacity investments where domestic consumer markets and export-oriented manufacturing develop simultaneously. Strategic projects should prioritize extrusion, printing, lamination, pouch-making, and quality-control capabilities rather than isolated equipment additions. Suppliers with integrated operations can improve responsiveness and manage material specifications more consistently.
High-Performance Sustainable Structures for Premium Applications
Another opportunity lies in developing pouches that combine high barrier performance with recyclable or lower-impact material architectures. Premium food, health care, personal care, and specialty household products often require stronger protection and more sophisticated graphics than basic pouch applications. This creates room for suppliers to differentiate through oxygen and moisture barriers, enhanced seal integrity, premium printing, controlled dispensing, and application-specific polymer structures. Investments in coating, extrusion, digital printing, and material-science capabilities can help converters address smaller premium runs without sacrificing technical consistency. Commercial success will depend on proving that sustainable structures can maintain product shelf life and manufacturing efficiency. Suppliers able to provide validated performance data alongside packaging redesign support can participate earlier in customers' product-development cycles.
Recent Developments
- September 2026: Amcor plc — Amcor announced its participation in PACK EXPO International 2026, highlighting flexible packaging technologies, recyclable packaging designs, recycled-content solutions, and applications across food, beverage, health care, home, beauty, and personal care. The company also highlighted a recycle-ready refill pouch and reclosable health care pouch among its recent innovations.
- May 2026: ProAmpac — ProAmpac showcased new sustainable packaging innovations at Interpack 2026, including recyclable film and fiber structures and new flexible packaging solutions following its acquisitions of TC Transcontinental Packaging and PAC Worldwide. The company positioned expanded manufacturing scale and material science capabilities around sustainability and regulatory-readiness requirements.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners provided valuable market intelligence that supported our global go-to-market strategy. Their team was professional, responsive, and attentive to our feedback, providing thoughtful analysis and helpful methodological clarifications throughout the project.
Junmo Kim Chief Financial Officer (CFO), Enertech Co., Ltd.
The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for