
Water Quality Sensor Market Growth, Demand & Size by 2034
Coverage: By Product Type (TOC Analyzers, PH Sensor, Dissolved Oxygen Analyzers, Conductivity Sensors, Turbidity Meters, Others); Application (Laboratories, Industrial, Aquaculture, Drinking Water, Wastewater Treatment, Others) and Geography, and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPTE00002283
- Category : Electronics and Semiconductor
- No. of Pages : 150
- Available Report Formats :


- Last update date : September 28, 2026


2025 Market Size
US$ 2.13 Bn
Base year value
2034 Forecast
US$ 3.86 Bn
Projected by 2034
CAGR 2026-2034
6.85 %
Growth rate
Addressable Market
US$ 27.09 Bn
(2026-2034)
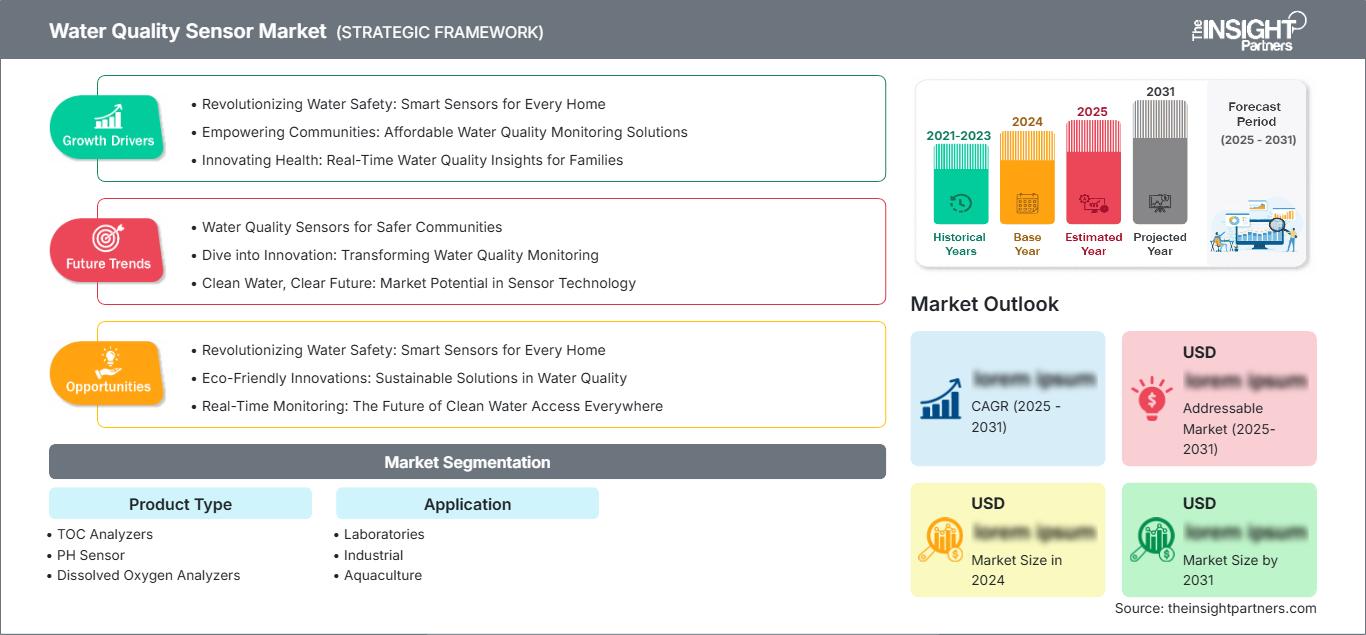
The water quality sensor market was valued at US$ 2.13 Billion in 2025 and is projected to reach US$ 3.86 Billion by 2034, expanding at a CAGR of 6.85% from 2026 to 2034. The market covers sensing and analytical technologies used to measure physical, chemical, and biological indicators across water treatment, industrial processing, laboratories, aquaculture, and drinking-water systems.
North America is expected to maintain a strong position, with the water quality sensor market size supported by the modernization of municipal infrastructure, stricter discharge controls, and increasing adoption of continuous monitoring. The region is estimated to expand at a 6.9–7.5% CAGR between 2026 and 2034, supported by digital water programs and the replacement of aging analytical equipment with connected sensing platforms.
Water Quality Sensor Market Assessment and Insights
- North America: North America is estimated to account for a 34–38% share in 2025, with the water quality sensor market growing at a 6.9–7.5% CAGR between 2026–2034, supported by municipal upgrades, industrial compliance, and connected monitoring adoption.
- US: The US represents approximately 70–74% of North America's 2025 share, growing at a 6.8–7.4% CAGR between 2026–2034, supported by wastewater modernization and regulatory monitoring requirements.
- Europe: Europe is estimated at a 27–31% share in 2025, growing at a 6.1–6.8% CAGR between 2026–2034. Germany, the UK, France, Italy, and Spain remain important markets because of industrial wastewater controls and water-efficiency programs.
- Asia Pacific: Asia Pacific is estimated at a 25–29% share in 2025, expanding at a 7.8–8.6% CAGR between 2026–2034. China, Japan, South Korea, India, and Australia are driving adoption through industrialization, urban water infrastructure, and environmental monitoring.
- Largest Segment: The pH Sensor segment is estimated to hold a 28–32% market share in 2025 and expand at a 6.4–7.0% CAGR between 2026–2034, reflecting broad deployment across treatment and industrial applications.
- High Growth Segment: Aquaculture is estimated to represent a 10–14% market share in 2025, with a 8.5–9.5% CAGR between 2026–2034, driven by tighter control of dissolved oxygen, pH, conductivity, and turbidity.
- Key companies analyzed in detail: Analytical Technology, Inc.; Omega Engineering, Inc.; Hach Company; ABB Ltd.; HORIBA, Ltd.; Siemens AG; General Electric Company; Halma plc; Emerson Electric Co.; Yokogawa Electric Corporation.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The water quality sensor market has evolved from laboratory-centric testing toward distributed, continuous, and increasingly connected measurement. New sensor technologies in optical dissolved oxygen sensing, digital pH sensors, solid state electronics, advanced conductivity probes and automation of turbidity measurement have facilitated field application. Sensors are being increasingly integrated with transmitters, controllers, communication interfaces, and software by the industry, thus making procurement decisions less about single instruments and more about monitoring architectures.
The potential future growth will be in applications that integrate compliance monitoring with process optimization. Emerging markets are investing in wastewater treatment plants, water supply systems and industrial environment control, while developed markets focus on renewal and digitization. Regulations requiring risk-based water safety assessment, including the WHO guidelines revised in 2026, underscore the importance of accurate measurement at all stages of water processing.
Water Quality Sensor Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 2.13 Billion |
| Market Size by 2034 | US$ 3.86 Billion |
| Global CAGR (2026 - 2034) | 6.85% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Water Quality Sensor Market Analysis
Demand is increasingly tied to the need for timely measurement rather than periodic sampling alone. The water quality sensor market growth is supported by treatment operators seeking continuous visibility into pH, dissolved oxygen, conductivity, turbidity, and organic loading. The ecosystem includes makers of sensors, producers of analytical instrumentation, integrators, treatment systems firms, utilities, industries, laboratories, and maintenance firms.
Market dynamics are influenced by the robustness of sensors, their calibration needs, chemical resistance, and servicing throughout the lifecycle. Industries place more emphasis on rugged sensors and maintenance, while laboratories seek accuracy and reliability. With optical sensing and digital communications technologies, some hassles can be eliminated, and modular controllers enable multiple parameters to be incorporated into one system.
Competitive positioning increasingly depends on the water quality sensor market analysis of total ownership cost, connectivity, measurement stability, and service infrastructure rather than sensor price alone. Hach Company, ABB Ltd., Emerson Electric Co., and Yokogawa Electric Corporation have broad industrial and water-monitoring capabilities, while HORIBA, Ltd., Omega Engineering, Inc., and Analytical Technology, Inc. address specialized analytical requirements.
Investment strategies are trending towards multi-parameter platforms, digital diagnostics, remote data access, and harsh environment sensors. Siemens AG and General Electric Company offer expanded automation and infrastructural competencies, while Halma plc gains from having a diversified portfolio with competencies in environmental and measuring technology. The ability to differentiate is thus increasingly tied to installed base, calibration, integration, and applications expertise.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Water Quality Sensor Market: Strategic Insights
Regional Insights
North America water quality sensor market
North America is estimated to represent 34–38% of global revenue in 2025 and is projected to expand at a 6.9–7.5% CAGR through 2034. The US accounts for 70–74% of the regional market, supported by municipal wastewater upgrades, industrial discharge monitoring, and replacement of aging analytical equipment. Canada adds demand from mining, municipal treatment, food processing, and resource-intensive industries.
The regional purchasing environment favors connected sensors capable of continuous operation and integration with supervisory control systems. Utilities increasingly seek lower maintenance requirements and stronger traceability of measurements, while industrial operators use sensors to improve process stability and reduce compliance exposure. Hach Company, Emerson Electric Co., ABB Ltd., and Omega Engineering, Inc. maintain relevant product and service capabilities, strengthening local availability and application support.
U.S. water quality sensor Market
The U.S. represents approximately 70–74% of North America's 2025 water quality sensor market share and is expected to grow at a 6.8–7.4% CAGR through 2034. Demand is concentrated across drinking-water utilities, wastewater facilities, industrial plants, laboratories, and environmental monitoring programs.
Application trends favor online measurement, automated alerts, and digital data transfer. Municipal operators increasingly require sensors that can support continuous process visibility without extensive manual calibration. Industrial buyers prioritize ruggedness in corrosive or variable environments. Hach Company, ABB Ltd., Emerson Electric Co., Siemens AG, and Analytical Technology, Inc. have established market presence, while specialized suppliers compete through parameter-specific accuracy and service responsiveness.
Europe water quality sensor Market
Europe is estimated to account for 27–31% of global revenue in 2025 and is projected to grow at a 6.1–6.8% CAGR through 2034. Germany is the leading country, followed by the UK, France, Italy, and Spain, with demand shaped by environmental compliance, water reuse, industrial treatment, and modernization of monitoring infrastructure.
The UK market benefits from utility investment and rigorous water-quality oversight, while Germany combines strong industrial demand with advanced wastewater treatment practices. France, Italy, and Spain are increasingly relevant as utilities address water stress, treatment efficiency, and reuse requirements. The regional market favors reliable, digitally connected instruments that can support traceability and remote supervision. Suppliers with European service networks and automation integration capabilities are positioned to address replacement and modernization cycles.
APAC water quality sensor Market
APAC is estimated to hold a 25–29% share in 2025 and is projected to grow at a 7.8–8.6% CAGR through 2034, making it the fastest-growing major region. China leads regional demand, followed by Japan, South Korea, India, and Australia.
Industrial wastewater regulation, urbanization, aquaculture expansion, and infrastructure investment are increasing sensor deployment. China and India provide significant volume opportunities, while Japan and South Korea emphasize precision and automation. Australia has additional demand linked to water scarcity and resource management. Policy attention to wastewater treatment and water security supports broader adoption of continuous monitoring technologies.
Middle East & Africa water quality sensor Market
The Middle East and Africa market is expected to expand at a 5.5–6.3% CAGR through 2034, supported by desalination, water reuse, municipal infrastructure, and industrial water management. Saudi Arabia and the UAE lead Middle Eastern demand, while South Africa represents a major African market.
Energy-intensive desalination and treatment facilities require reliable conductivity, pH, turbidity, and dissolved oxygen monitoring. Saudi Arabia benefits from large-scale water infrastructure programs, while the UAE emphasizes desalination efficiency and reuse. South Africa and the Rest of MEA offer opportunities as utilities and industries improve monitoring capability, although capital availability and technical-service coverage remain important purchasing considerations.
Segmentation Analysis
Product Type
The Product Type segment is projected to grow at a 6.3–7.1% CAGR from 2026–2034. Demand is distributed across sensors and analyzers measuring distinct water-quality parameters, with buyers increasingly favoring reliable digital outputs, simplified calibration, and compatibility with centralized control systems. Parameter selection varies according to treatment stage, water chemistry, regulatory requirements, and process sensitivity.
- TOC Analyzers: Total organic carbon analyzers are important where operators need continuous visibility into organic loading. Demand is concentrated in drinking-water treatment, pharmaceuticals, semiconductor manufacturing, and high-purity process water applications requiring sensitive contamination control.
- PH Sensor: pH sensors occupy a broad installed base because pH influences treatment chemistry, corrosion, biological activity, and discharge compliance. Their versatility makes them common across municipal, industrial, laboratory, and aquaculture operations.
- Dissolved Oxygen Analyzers: Dissolved oxygen analyzers are essential for biological wastewater treatment, aquaculture, and process applications. Optical designs increasingly appeal to operators seeking longer service intervals, stable measurement, and reduced maintenance.
- Conductivity Sensors: Conductivity sensors provide a rapid indication of ionic concentration, contamination, salinity, and process changes. They are strategically important in water treatment, chemical processing, power generation, food production, and desalination systems.
- Turbidity Meters: Turbidity meters support particulate monitoring and treatment verification. Their importance increases where utilities require rapid detection of filtration problems, distribution disturbances, or changing source-water conditions.
Application
The Application segment is expected to expand at a 6.8–8.2% CAGR from 2026–2034. Demand differs by monitoring frequency, regulatory requirements, process complexity, and water chemistry. Continuous sensing is particularly valuable where changing conditions can affect treatment efficiency, biological performance, product quality, or public-health protection.
- Laboratories: Laboratories remain important for reference measurements, method validation, calibration, and detailed water characterization. Portable and benchtop instruments support quality assurance while complementing online monitoring networks.
- Industrial: Industrial users deploy sensors to control process water, wastewater discharge, cooling systems, boilers, and production environments. Purchasing decisions emphasize reliability, automation compatibility, chemical resistance, and lifecycle economics.
- Aquaculture: Aquaculture operations require close control of water conditions because dissolved oxygen, pH, temperature, and suspended particles influence stock health and production efficiency. Automated monitoring supports rapid intervention.
- Drinking Water: Drinking-water facilities use sensors across source, treatment, storage, and distribution stages. Continuous measurement strengthens operational control and helps identify deviations before they become larger quality events.
- Wastewater Treatment: Wastewater treatment is a major application because online measurements support aeration, chemical dosing, biological treatment, and discharge management. Sensors help operators balance treatment performance with energy and chemical consumption.
Opportunity Snapshot
| Application | Revenue Contribution (High/Medium/Low) | Trend Tag (MAX 2 words) | Adoption Stage (Emerging/Scaling/Mature) |
| Laboratories | Medium | Reference Testing | Mature |
| Industrial | High | Process Control | Scaling |
| Aquaculture | Medium | Oxygen Control | Scaling |
| Drinking Water | High | Network Monitoring | Mature |
| Wastewater Treatment | High | Effluent Control | Mature |
Water Quality Sensor Market Growth Drivers and Impact Analysis
Expansion of Continuous Water Monitoring Infrastructure
Continuous measurement is taking on greater significance as utilities and industrial installations shift from sample-based testing to continuous measurement. The market for water quality sensors will benefit from online devices that can allow for an immediate understanding of the issues detected through laboratory analysis after the fact. Continuous measurements of pH, conductivity, dissolved oxygen, and turbidity can all be linked up with process controls and alarms. This creates an immediate connection between measurement and action. Continuous measurements in a wastewater plant can be used for optimal aeration and process stabilization, whereas drinking water installations can utilize distributed measurements to set quality standards. The value proposition goes beyond simply compliance, as sensors can lower the need for sampling, enable faster troubleshooting, and create process consistency. Suppliers combining durable hardware with connectivity and diagnostics are poised to take advantage of modernization investments.
Stricter Risk-Based Water Quality Management
Increasingly, there is an emphasis within regulatory systems on preventive risk management, which is driving an infrastructure need for accurate measurement systems. The market is driven by the increasing adoption of water safety plans, process control systems, and surveillance models that relate source water quality to the performance of the treatment and distribution system. The WHO guidance focuses more on risk management, monitoring, and improvement rather than endpoint testing. This trend increases the need for sensors that will provide accurate operational data from key points of the water cycle. Monitoring frequency, location, resources and relevance of the information are issues that must be considered by utilities. As such, there is increasing demand for tools that provide not only accurate data but also ease of maintenance and data processing.
Industrial Water Reuse and Process Efficiency
Water recycling in industry will drive demand for sensing devices capable of validating water conditions before and after various stages of water treatment. The market benefits from organizations looking to cut down on their freshwater intake while ensuring equipment protection and efficient processing procedures. Conductivity and TOC measuring will be useful in detecting changes in high-purity water, while dissolved oxygen and pH measuring will ensure a stable processing procedure. Water reuse systems will also benefit from reliable sensors since the variability of the source water may affect treatment needs. As more and more facilities switch to closed-loop systems, sensing devices will be used as crucial components of processing facilities, not merely peripheral laboratory devices.
Water Quality Sensor Market Future Trends
AI-Assisted Sensor Diagnostics and Predictive Monitoring
The water quality sensor market trends are likely to increasingly incorporate software that interprets sensor behavior rather than simply displaying measurements. In future systems, readings from history, calibration, environmental conditions, and processes will help determine the drifts, fouling, abnormal readings, or potential maintenance needs. This way, predictive diagnostics will be used to minimize unnecessary maintenance while assisting operators to differentiate true water quality readings from those of the instrument. With integration into cloud technology and edge computing, alarms could be prioritized based on operational risks. This technology will become more important when dealing with geographic distribution in the water network, where maintenance teams cannot visit all sites regularly. In the future, manufacturers will compete with one another using advanced diagnostic algorithms, secure communication systems, and automated quality management systems.
Multi-Parameter Platforms Become Standardized
Future measurement platforms would be able to integrate multiple measurements into one modular platform to be customized based on treatment needs. Rather than using a separate device for each measurement, the system would allow for the connection of probes such as pH, conductivity, turbidity, and dissolved oxygen, among others, via common controllers and communication mechanisms. This would make the process of installation, monitoring, and operation less cumbersome. Modularity would also allow for the addition of measurement devices as required. To suppliers of equipment, modularity would be an avenue through which to extend their revenue base by selling additional devices and upgrades without having to replace the entire measurement platform. This concept will be especially important to small-scale water utilities and plants where fewer technical resources would call for simplicity in architecture.
Water Quality Sensor Market Opportunities
Digital Monitoring for Distributed Water Networks
Market scope goes beyond treatment facilities and includes distribution systems where the situation may be different after leaving the central facilities. Suppliers may implement compact connected sensing devices in strategically chosen locations and measure such parameters as pH, conductivity, turbidity, and temperature. This opportunity is most appropriate where the networks are large, there are different sources, and the water age poses some challenges for operation. Remote communication, diagnostics, and alerts may make it possible for distributed monitoring to be more effective than conventional inspection. Suppliers may capitalize on this opportunity by manufacturing devices that are robust, easy to calibrate, have secure communication, and have multiple options for power sources. Alliance with utility technology suppliers will improve the economics of such an approach.
Integrated Monitoring for Water Reuse Projects
The water quality sensor market forecasts indicate attractive opportunities in facilities that expand water reuse while maintaining strict process controls. The projects involving reuse will necessitate multiple points of measurement, since it is important to monitor the quality of water being treated at each stage of filtration, biological processing, disinfection, storage, and final use. It will be possible to create application kits consisting of sensors, controllers, analytics, and services for reuse applications by the suppliers. The opportunity will be especially pertinent to the industrial sites, where the water availability will have a direct impact on the productivity and operational expenses. The desalination and wastewater treatment projects might require monitoring of conductivity, turbidity, dissolved oxygen, and organics.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners provided valuable market intelligence that supported our global go-to-market strategy. Their team was professional, responsive, and attentive to our feedback, providing thoughtful analysis and helpful methodological clarifications throughout the project.
Junmo Kim Chief Financial Officer (CFO), Enertech Co., Ltd.
The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for