
隆胸市场:规模、份额及机遇(2034 年)
隆胸市场规模及预测(2021-2034)、全球及区域份额、趋势和增长机会分析报告涵盖范围:按产品(硅胶乳房假体、盐水乳房假体);形状(解剖型、圆形);表面(光滑型、纹理型);手术方式(乳房下皱襞入路、腋窝入路、乳晕周围入路、脐周入路);最终用户(医院、美容诊所和门诊护理机构等);以及地理区域(北美、欧洲、亚太地区以及中南美洲)。
- 状态 : 数据发布
- 报告代码 : TIPRE00022685
- 类别 : 生命科学
- 页数 : 150
- 可用报告格式 :


- 最后更新日期 : August 05, 2026


2025年市场规模
152.2 亿美元
基准年值
2034 年预测
292 亿美元
预计到2034年
2026-2034年复合年增长率
7.51 %
增长率
目标市场
2002 亿美元
(2026-2034)
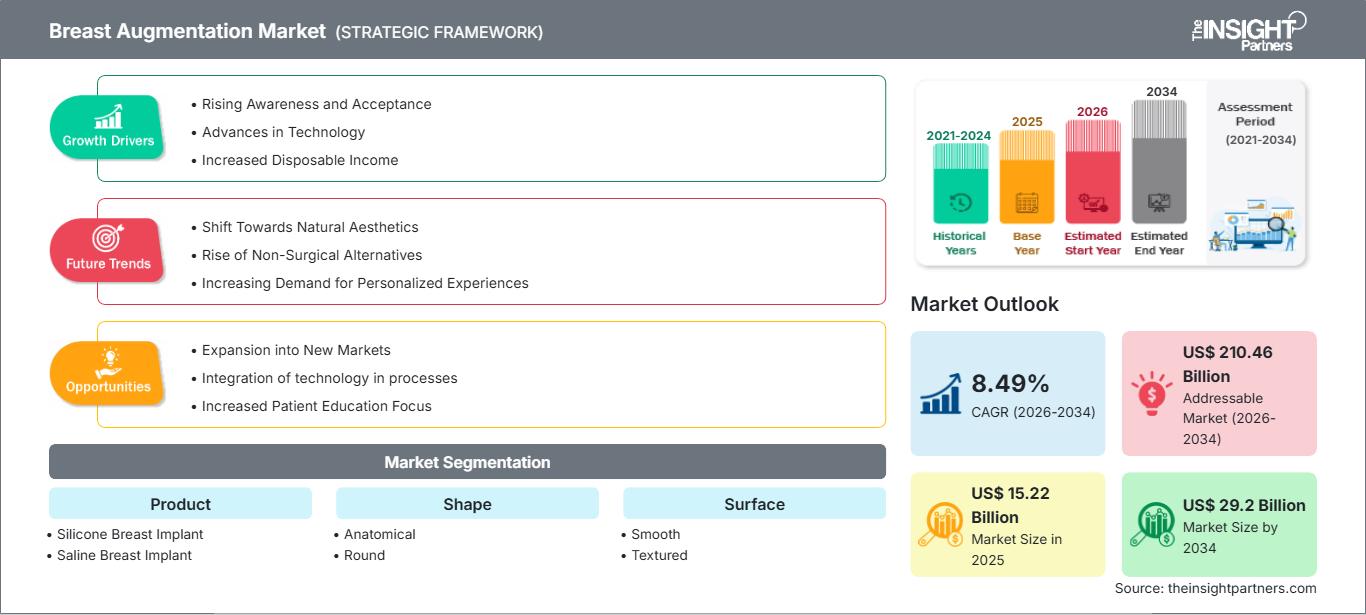
2025年,隆胸市场价值152.2亿美元,预计到2034年将达到292亿美元;预计2026-2034年期间的复合年增长率为7.51%。
隆胸市场评估与洞察
- 北美在 2025 年占据 38% 至 42% 的市场份额,预计在 2026 年至 2034 年间将以 7.8% 至 8.4% 的复合年增长率增长。获得 FDA 批准的产品、专科外科医生、重建项目和植入物登记参与情况都强化了市场需求。
- 2025 年,美国占北美市场的 82% 至 86%,预计在 2026 年至 2034 年间,其复合年增长率将达到 7.9% 至 8.5%,这得益于植入物审批、翻修手术和重建需求。
- 2025年,欧洲市场份额占比为24%至28%,预计2026年至2034年间将以7.2%至7.8%的复合年增长率增长。德国、法国、意大利、西班牙和英国通过私人美容诊所和符合MDR标准的供应商引领需求。
- 亚太地区在2025年占据了22%至26%的市场份额,预计在2026年至2034年间将以9.2%至10.0%的复合年增长率增长。中国、日本、韩国、印度和澳大利亚的增长主要得益于医疗美容支出和外科医生培训的增加。
- 2025 年,硅胶乳房植入物占据了 78% 至 84% 的市场份额,预计 2026 年至 2034 年的复合年增长率将达到 8.4% 至 9.0%,这反映了患者对自然触感的偏好以及更广泛的产品供应。
- 高增长细分市场:光滑表面种植体在 2025 年占据 58-64% 的市场份额,预计在 2026 年至 2034 年间将以 9.0-9.8% 的复合年增长率增长,这得益于纹理种植体受到审查后,出于安全考虑而进行的购买转变。
- 重点分析的公司有:Mentor Worldwide LLC、Allergan Aesthetics、Tiger Aesthetics Medical LLC 旗下的 Sientra、Ideal Implant Incorporated、Laboratoires Arion、CEREPLAS、Sebbin SAS、GC Aesthetics plc、POLYTECH Health & Aesthetics GmbH、广州万和塑料材料有限公司。
资料来源: Insight Partners 根据专有研究、政府出版物、公司年报、投资者报告、行业数据库和专家访谈进行的分析。
Breast Augmentation Market has transitioned from simple breast volume augmentation to more advanced implant science, procedure planning, and safety management. Manufacturers focus on cohesive gel implants, shell structure, smooth surface, larger implant profiles, and surgeon training. Manufacturing factors impacting production have become regulation-driven, post-approval testing, compliance with the quality system, and regional distribution partners. In this way, evidence, traceability, and warranty become as important as the physical characteristics of the products.
In the forecast period, the market would benefit from growing demand in Asia Pacific and the Middle East, where aesthetic clinics would be growing in number. Regulations would not inhibit market growth but rather would direct it to approved, evidenced, and physician-approved products. Future investment is expected to go into differentiated silicone products, digital consultation tools, and reconstruction products.
Breast Augmentation Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 15.22 Billion |
| Market Size by 2034 | US$ 29.2 Billion |
| Global CAGR (2026 - 2034) | 7.51% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Breast Augmentation Market Analysis
Growth in the market for breast augmentation surgery is driven by increased acceptance of elective aesthetics, increased reconstruction surgery, and consumer preference for personalization. Growth in demand happens in locations where there are specialized plastic surgeons, registry tracking for implants, and funding. There are changes in supply as well due to the fact that the FDA has compelled manufacturers to move towards implants with a smooth surface, clear patient decision checklists, and evidence-based positioning for their products.
There are several players in the value chain of the industry such as suppliers of silicone raw materials, implant makers, regulatory specialists, distributors, hospitals, ASCs, and plastic surgery clinics. Breast reconstruction for cancer is an important structural layer of demand, particularly in developed markets with well-organized oncological care. Professional societies and physician training programs also contribute to the ecosystem.
The Breast Augmentation Market report reveals that competition is becoming technology-driven rather than price-driven. Mentor Worldwide LLC and Allergan Aesthetics rely on a larger portfolio and access to hospitals, whereas Sientra through Tiger Aesthetics Medical LLC is repositioning via regenerative medicine adjacency. On the other hand, GC Aesthetics plc and POLYTECH Health & Aesthetics GmbH are competing with their European manufacturing capabilities and portfolio.
植入体的定位高度依赖于监管、外科医生的熟悉程度以及表面差异。美国市场批准了Establishment Labs公司的Motiva植入体,这引发了人们对新一代光滑表面植入体的讨论,但这些植入体并非都属于同一家公司。像Laboratoires Arion、CEREPLAS、Sebbin SAS和广州万和塑料材料有限公司这样的专业公司,凭借其丰富的产品目录和与外科医生的良好关系,满足了不同地区的市场需求。
您可以调整的内容
- ● 细分
- ● 地理
- ● 竞争分析
- ● 语言偏好
隆胸市场:战略洞察
区域洞察
北美隆胸市场
北美市场在2025年占据了38%至42%的市场份额,预计在2026年至2034年间将以7.8%至8.4%的复合年增长率增长。北美隆胸市场份额的增长归功于FDA批准的植入物产品、手术信息公开、上市后监测以及完善的重建方案。患者决策清单和黑框警告提高了公众意识,同时也促使患者更加倾向于在医生的指导下做出知情决策。
美国将引领市场扩张,其次是加拿大,这两个国家的整形外科医生网络和乳房重建项目都已相当完善。制造商的活动主要集中在硅胶假体、光滑质地和高端产品系列上。包括国家乳房植入物登记处在内的临床注册基础设施进一步推动了市场需求。
美国隆胸市场
预计到2025年,美国将占北美地区的82%至86%,并在2026年至2034年间保持7.9%至8.5%的复合年增长率。美国食品药品监督管理局(FDA)的审批流程、高密度的外科医生以及患者的融资方式,共同促成了较高的单次手术价值。近期获批的大尺寸重建植入物和光滑表面器械为外科医生提供了更多选择,也加剧了器械之间的竞争。
由于其产品获得批准、开展教育推广活动并提供质保服务,Mentor Worldwide LLC、Allergan Aesthetics 和 Tiger Aesthetics Medical LLC 的子公司 Sientra 在美国市场占据着举足轻重的地位。应用趋势表明,人们对初次隆胸、假体置换和乳房切除术后重建的兴趣持续高涨。与医院签订重建手术合同也变得越来越重要。
欧洲隆胸市场
预计到2025年,欧洲将占据24%至28%的市场份额,并在2026年至2034年间保持7.2%至7.8%的复合年增长率。德国凭借其专科诊所、先进的外科设施以及因医疗器械法规(MDR)而对可追溯植入物的偏好,在该地区占据主导地位。GC Aesthetics plc、POLYTECH Health & Aesthetics GmbH、Sebbin SAS、CEREPLAS和Laboratoires Arion等公司也为欧洲的供应商格局做出了贡献。
英国的整形外科市场由私人机构主导,重建手术需转诊,并遵循严格的患者咨询流程。市场需求均衡分布于初次隆胸和假体置换之间,专业咨询会影响假体的选择。光滑表面假体和安全记录正成为备受关注的市场中的关键差异化因素。
法国、意大利和西班牙由于其悠久的美容医学历史和专业的整形外科医生,在规模上更具优势。法国拥有强大的本土制造商和严格的监管体系,而意大利和西班牙则拥有稳定的私人诊所数量。在这些市场,市场正朝着更加注重文件记录、外科医生培训和患者个性化植入方案的方向发展。
亚太地区隆胸市场
亚太地区2025年的市场份额为22%-26%,预计2026年至2034年的复合年增长率将达到9.2%-10.0%。中国是市场份额最大的国家,其次是日本、韩国、印度和澳大利亚。可支配收入的增加、人们对医美接受度的提高以及专科诊所数量的增长是推动市场需求的主要因素。
影响政策的因素包括医疗器械的良好注册、对私营医疗保健领域的投资以及质量控制。韩国和日本对美容技术的发展起着主导作用,而印度和中国则通过城市地区的手术量贡献了市场规模。亚太地区的市场需求受分销商和外科医生培训项目的影响。
中东和非洲隆胸市场
预计2026年至2034年间,中东和非洲地区的复合年增长率将达到8.0%-8.8%,其中阿联酋在该地区植入物使用方面处于领先地位。沙特阿拉伯、南非以及中东和非洲其他国家也通过私立医院、医疗旅游和高端美容诊所参与其中。
Growing investments in healthcare infrastructure and clinics specializing in procedures involving implants have made implant procedures easier. Public investments in healthcare in the Gulf region as a result of energy investments make provision for premium procedures, while South Africa continues to act as a hub of procedures for parts of the continent.
Segmentation Analysis
Product
The Product segment is expected to grow at a CAGR of 8.3–8.9% during 2026–2034. Breast Augmentation Market scope across product types is defined by implant feel, rupture behavior, cost, regulatory approval, and patient preference. Silicone products dominate mature markets, while saline products retain relevance where adjustability, incision size, and pricing influence surgeon recommendations.
- Silicone Breast Implant: Silicone implants hold the strongest market position due to natural feel, broad profile availability, and strong surgeon familiarity. They are strategically important for premium augmentation and reconstruction planning.
- Saline Breast Implant: Saline implants serve cost-sensitive and specific clinical needs, particularly where adjustability is valued. Their role remains narrower but relevant in selected patient groups and surgical preferences.
Shape
The Shape segment is projected to grow at a CAGR of 8.1–8.7% during 2026–2034. Shape selection depends on body frame, desired contour, surgeon technique, implant pocket planning, and reconstruction requirements. Round implants are widely used because of procedural simplicity and predictable fullness, while anatomical implants retain value in selected aesthetic and reconstructive indications.
- Anatomical: Anatomical implants support contour-specific procedures and reconstruction cases where a natural slope is desired. Their use depends on careful pocket control and surgeon experience.
- Round: Round implants maintain broad demand because they provide upper-pole fullness, easier orientation, and wide product availability. They are strategically important in high-volume aesthetic procedures.
Surface
The Surface segment is forecast to grow at a CAGR of 8.6–9.2% during 2026–2034. Surface selection has become central to safety perception, clinical counselling, and procurement. Smooth implants are gaining preference after regulatory scrutiny of textured products, while textured implants remain selectively used where local approvals and clinical judgment support their application.
- Smooth: Smooth implants are increasing in strategic importance because of safety-related purchasing shifts, regulatory confidence, and patient preference. They are strongly aligned with current product innovation.
- 纹理:纹理植入物在重建和解剖定位方面仍有一定用途,但由于几个成熟市场中安全审查的加强和外科医生的谨慎,需求受到限制。
机遇概览
|
段名称 |
收入贡献 |
潮流日 |
收养阶段 |
|
硅胶隆胸假体 |
高的 |
自然的感觉 |
成熟 |
|
盐水乳房假体 |
中等的 |
可调节填充 |
成熟 |
|
解剖学 |
中等的 |
轮廓规划 |
规模化 |
|
圆形的 |
高的 |
上部饱满 |
成熟 |
|
光滑的 |
高的 |
安全轮班 |
规模化 |
|
纹理 |
低的 |
选择性使用 |
成熟 |
隆胸市场增长驱动因素及影响分析
乳腺癌手术后重建需求不断增长
乳房重建之所以成为一项持久的结构性驱动因素,是因为它将植入物需求与肿瘤治疗路径联系起来,而不仅仅是出于个人审美需求。在美国,强生医疗科技公司指出,每年有超过24.6万名女性接受乳房切除术,这使得基于植入物的重建方案需求持续存在。如今,更大尺寸的植入物设计能够满足以往缺乏合适选择的患者的需求,从而提升外科医生个性化手术效果的能力。这不仅扩大了传统隆胸诊所的需求范围,也提高了医院采购的相关性。当肿瘤中心、整形外科医生和器械制造商围绕重建时机、患者咨询和植入物供应进行协调时,市场将从中受益。随着时间的推移,这一驱动因素应会促进高价值硅胶植入物的普及,尤其是在拥有保险覆盖重建项目的成熟医疗体系中。
转向表面光滑且有循证医学支持的植入物
安全沟通已显著改变了产品选择。FDA 的资料强调,乳房植入物并非终身医疗器械,必须在手术前明确告知风险。该机构还持续评估医疗器械报告、上市后研究合规性以及制造商标签。这些要求正在增强市场对具有临床证据支持、标签透明且上市后数据可追溯的产品的需求。随着患者和外科医生寻求符合安全预期的产品,光滑表面系统正变得日益重要。因此,市场扩张并非仅仅依靠手术量的增加,而是正在向受监管、有据可查且摩擦更小的产品类别升级。拥有强大的证据生成能力、合规体系和外科医生培训的制造商,将比主要依靠价格竞争的公司更具优势。
更广泛的植入物产品组合,实现个性化手术
Portfolio depth is increasingly important because patients differ by anatomy, reconstruction history, desired projection, and tolerance for revision risk. Allergan Aesthetics has highlighted Natrelle’s range of more than 300 implant options, while Mentor Worldwide LLC has introduced larger reconstruction-focused implants. These developments show that competitive advantage is moving toward profile breadth, gel choices, sizes, and application-specific families. Surgeons can better match implant characteristics with tissue envelope, body frame, and aesthetic objectives. The Market benefits because personalization can improve patient satisfaction and reduce compromise in complex cases. Manufacturers that support planning, education, and reliable availability across sizes can increase surgeon loyalty, reduce substitution risk, and capture premium demand across augmentation, revision, and reconstruction workflows.
Breast Augmentation Market Future Trends
Digital planning and patient-specific implant selection
Breast Augmentation Market trends will increasingly include digital consultation, imaging-based sizing, and structured decision support. Clinics are likely to use visualization tools to improve expectation management, reduce sizing uncertainty, and document shared decision-making. This trend will matter because implant selection is highly preference-sensitive, and dissatisfaction often relates to size, projection, or symmetry rather than device failure alone. Digital workflows can also support follow-up reminders, implant card management, and revision planning. Manufacturers may integrate educational platforms with surgeon networks to influence product selection earlier in the consultation journey. The long-term effect will be a more data-driven pathway where clinical judgment, patient goals, and device attributes are aligned before surgery.
Regulatory-led preference for traceable premium devices
Future demand will be shaped by patient awareness, global device vigilance, and surgeon preference for traceable products. Registries such as the National Breast Implant Registry demonstrate how device tracking can support safety monitoring and evidence development. As regulators and professional societies continue emphasizing informed consent, patients will likely favor brands with accessible labeling, postmarket data, and reliable warranties. This creates a premiumization trend, especially in North America and Europe, where procurement decisions are increasingly linked to compliance confidence. The Market will therefore reward companies that invest in quality systems, long-term studies, and transparent risk communication rather than relying on visual differentiation alone.
Breast Augmentation Market Opportunities
Expansion in Asia Pacific premium aesthetic centers
亚太地区投资前景广阔,因为手术接受度、私立诊所扩张和城市收入增长三者正齐头并进。隆胸市场预测显示,该地区的增长速度将高于全球平均水平,尤其是在训练有素的外科医生和高端器械分销商正在提升产能的地区。中国、韩国、日本、印度和澳大利亚各自需要不同的渠道策略,从与医院的合作关系到对美容诊所的培训。制造商可以通过支持医生培训、本地化的患者资料以及可靠的监管申报来获取价值。在患者越来越注重安全性、舒适度和品牌声誉的地区,高端硅胶和光滑表面植入物系列产品应该会表现出色。由于亚太各国的监管注册和分销商质量差异显著,因此,严格的市场准入是实现这一目标的关键。
以重建为重点的医院合作关系
医院供应合作关系为稳定需求创造了机会,使其不再局限于非必需的美容周期。艾尔建美学与Vizient的供应商协议表明,采购网络如何能够扩大学术医疗中心、社区医院和综合医疗服务网络获取植入物产品的渠道。这种模式具有重要的战略意义,因为重建手术通常依赖于医院的采购、报销途径和多学科癌症治疗。制造商可以通过提供外科医生培训、库存可靠性、患者病历记录和保修支持来促进产品的普及。与非必需的美容手术相比,乳房增大市场能够从这些机构渠道获得更高质量的增长,因为它们受短期消费者情绪的影响较小。与肿瘤重建优先事项保持一致的公司也将有助于提高临床医生的信任度,并维护品牌的长期发展。
最新进展
- 2025年10月:艾伯维旗下公司艾尔建美学宣布,其子公司Natrelle与Vizient签署供应商协议,这将扩大其植入物产品组合的供应渠道,覆盖学术医疗中心、社区医院、整合医疗服务网络和非急性护理机构。该协议有助于提高美国医疗机构的采购效率、价格优势,并为其提供重建手术方案。
- 2025年5月:强生医疗科技公司在美国推出MENTOR MemoryGel Enhance乳房假体,专为乳房切除术后乳房较大的患者设计。该系列产品提供930cc至1445cc的多种尺寸,旨在满足此前缺乏合适尺寸乳房重建方案的患者的需求,填补了乳房切除术后约15%的重建选择缺口。
- 2024年4月:Tiger Aesthetics Medical LLC收购了Sientra Inc.乳房植入物业务的几乎所有资产。此次交易使Sientra成为Tiger Aesthetics Medical LLC的一个部门,并将该公司的植入物产品组合与Tiger的再生医学战略相结合,同时保留了Sientra位于威斯康星州富兰克林工厂的生产和运营。
常见问题解答

- 全面的市场规模与预测分析
- 详细的细分市场分析
- 深入的市场动态评估
- 区域及国家级洞察
- 竞争格局与企业对标分析
- 战略性商业情报
客户评价

The Insight Partners 提供了有价值的市场情报,帮助我们制定并推进全球市场进入战略。他们的团队专业、响应及时,并认真听取我们的反馈,在整个项目过程中提供了深入的分析和有帮助的方法论说明。
Junmo Kim 首席财务官(CFO), Enertech Co., Ltd.
Insight Partners 的 SCADA 系统市场报告内容全面,对当前趋势和未来预测提供了宝贵的见解。该团队始终高度专业、响应迅速且乐于助人。我们非常满意,强烈推荐他们的服务。
兰·凯德姆 伙伴, Reali Technologies LTD
我请求一份关于特定软件市场的报告,团队在几天内就完成了。报告信息非常相关,而且呈现得非常出色。之后,我请求对报告进行一些修改和补充。团队再次迅速响应,不到一周我就收到了最终报告。
让-埃尔韦·詹恩 主席, 未来分析公司
我们与 Insight Partners 合作进行了一项重要的市场研究和预测。他们清晰地洞察了机遇和风险,帮助我们制定了计划。他们的研究简单易用,数据可靠,帮助我们做出了明智而自信的决策。我们强烈推荐他们。
皮尤什·纳格帕尔 高级副总裁, 远光全球
Insight Partners 凭借其深厚的行业专业知识,提供了富有洞察力、结构合理的市场研究。他们的团队始终专业且响应迅速。用户友好的网站让访问行业报告变得顺畅无阻。我们强烈推荐他们可靠、高质量的研究服务。
安达幸彦 首席执行官, 深蓝有限责任公司
这是我第一次从The Insight Partners购买市场报告。起初我有些犹豫,但访问了他们的网站后,我更放心地冒险购买市场报告。我对报告的质量和客户服务非常满意。我对最初的报告有一些疑问和意见,但在与他们的分析师通过电子邮件沟通了几次后,我相信这份报告可以作为我们战略规划流程的参考。非常感谢您抽出宝贵的时间,让这次体验如此愉快。我一定会向其他人推荐你们的服务,当我们需要更多市场数据时,你们将是我的首选。
约翰·铃木 总裁兼首席执行官、董事会董事, BK科技
感谢您在处理我关于尼日利亚传染病体外诊断市场信息请求的过程中所展现的支持和专业精神。感谢您的耐心、指导,以及您愿意提供的折扣,最终促成了这笔交易。我期待未来与 Insight Partners 继续合作,这一切都要归功于您与我初次接触后留下的良好印象。
奇吉奥克博士 ONYIA 董事总经理, PineCrest 医疗保健有限公司购买理由
- 明智的决策
- 了解市场动态
- 竞争分析
- 客户洞察
- 市场预测
- 风险规避
- 战略规划
- 投资论证
- 识别新兴市场
- 优化营销策略
- 提升运营效率
- 顺应监管趋势




















 获取免费样品 -