Medical Device Coating Market Size, Trends & Growth by 2034
Medical Device Coating Market Size and Forecast (2021 - 2034), Global and Regional Share, Trend, and Growth Opportunity Analysis Report Coverage: By Material Type (Polymer, Metal, and Others), Device Type (Medical Equipment and Tools, Medical Devices, Medical Implant, and Others), Coating (Hydrophilic Coating, Anti-Microbial Coating, Drug-Eluting Coating, Anti-Thrombogenic Coating, and Others), and Application (Infection Diseases, General Surgery, Orthopedic, Neurology, and Others), and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Report Date : Nov 2026
- Report Code : TIPRE00009272
- Category : Chemicals and Materials
- Status : Data Released
- Available Report Formats :


- No. of Pages : 150
Key market dynamics include an escalating need for antimicrobial surfaces to mitigate healthcare-associated infections, a global rise in cardiovascular and orthopedic surgeries, and the rapid miniaturization of medical devices requiring high-performance lubricious coatings. Additionally, the market is expected to benefit from the growing integration of drug-delivery systems within implants, a shift toward bioabsorbable materials, and significant healthcare infrastructure investments across Asia-Pacific region.
Medical Device Coating Market AnalysisThe medical device coating market analysis indicates a transition from simple protective layers to complex, multifunctional interfaces that actively enhance clinical outcomes. The market trends highlight a growing preference for specialty contract coating services over in-house production as OEMs seek to navigate tightening regulatory requirements and reduce capital expenditure. Strategic opportunities are emerging in the development of non-thrombogenic and bioactive coatings for long-term implantable devices, which help reduce the risk of clot formation and improve osseointegration. The market growth depends on the durability of coatings under diverse sterilization methods and the successful reduction of particulate matter in vascular applications. Competitive differentiation is now centered on providing comprehensive regulatory support and technical data that prove long-term biocompatibility and coating integrity.
Medical Device Coating Market OverviewMedical device coatings have evolved from niche industrial applications to essential components of modern surgical and diagnostic tools. The market encompasses a wide variety of technologies designed to improve device navigation, prevent bacterial colonization, and facilitate the controlled release of pharmaceuticals. Both established multinational chemical corporations and specialized biomedical startups compete in this space, utilizing advanced application techniques like physical vapor deposition and ultraviolet curing. Growing demand for minimally invasive procedures among aging populations in North America and Europe has increased the popularity of hydrophilic-coated guidewires and catheters as standard clinical solutions. North America leads in revenue due to its mature medical technology ecosystem, while Asia-Pacific is advancing rapidly through increased domestic manufacturing and rising healthcare access. The US market remains the global leader, driven by a vast ecosystem of innovative medical technology companies and a high volume of advanced surgical procedures. Rapid adoption of minimally invasive techniques and stringent safety regulations propel the demand for sophisticated functional surfaces, particularly in cardiovascular and neurological interventions.
Customize Research To Suit Your Requirement
We can optimize and tailor the analysis and scope which is unmet through our standard offerings. This flexibility will help you gain the exact information needed for your business planning and decision making.
Medical Device Coating Market: Strategic Insights
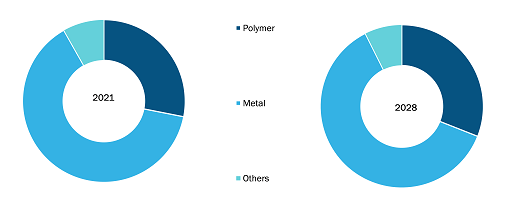
| Market Size Value in | US$ 7,644.09 Million in 2021 |
| Market Size Value by | US$ 12,818.01 Million by 2028 |
| Growth rate | CAGR of 7.7% from 2022 to 2028 |
| Forecast Period | 2022-2028 |
| Base Year | 2021 |
Shejal
Have a question?
Shejal will walk you through a 15-minute call to present the report’s content and answer all queries if you have any.
 Speak to Analyst
Market Drivers:
- Rising Prevalence of Chronic Diseases and Aging Population: The global increase in conditions such as diabetes and heart disease necessitates more surgeries involving coated stents, pacemakers, and orthopedic implants.
- Advancements in Minimally Invasive Surgery: The trend toward less invasive techniques relies heavily on hydrophilic and lubricious coatings that allow instruments to glide through narrow anatomical structures without causing tissue trauma.
- Stringent Infection Control Protocols: Hospitals are increasingly adopting antimicrobial-coated devices to lower the incidence of secondary infections, which reduces patient recovery time and overall healthcare costs.
Market Opportunities:
- Development of Smart and Bioactive Coatings: Opportunities exist for coatings that can sense physiological changes or promote targeted tissue growth, particularly in the orthopedic and dental segments.
- Expansion in Emerging Markets: Increasing medical tourism and healthcare spending in countries like China, India, and Brazil offer a high-growth corridor for affordable yet high-quality coated medical tools.
- Transition to PFAS-Free and Sustainable Materials: As environmental regulations evolve, there is a significant opportunity for companies to lead the market by providing high-performance, eco-friendly coating alternatives.
The medical device coating market share is analyzed across various segments to provide a clearer understanding of its structure, growth potential, and emerging trends. Below is the standard segmentation approach used in most industry reports:
By Material Type:
- Polymer: The leading segment due to the versatility of materials like silicone, fluoropolymers, and parylene, which offer excellent biocompatibility and lubricity.
- Metal: A high-growth segment featuring silver, copper, and titanium coatings valued for their natural antimicrobial properties and durability.
- Others: Includes ceramic and carbon-based coatings used for specialized high-wear applications in orthopedic and dental implants.
By Device Type:
- Medical Equipment and Tools: Covers a broad range of surgical instruments, diagnostic machines, and hospital furniture requiring protective or antimicrobial surfaces.
- Medical Devices: Represents the largest volume, including catheters, guidewires, and syringes that utilize functional coatings for better performance.
- Medical Implant: A high-value segment focused on long-term stents, heart valves, and joint replacements requiring biocompatible and drug-eluting interfaces.
- Others: Includes protective clothing and specialized sensors.
By Coating:
- Hydrophilic Coating: The dominant coating type, essential for reducing friction in minimally invasive vascular and urological procedures.
- Anti-Microbial Coating: A rapidly expanding category driven by global initiatives to combat antibiotic-resistant pathogens in clinical settings.
- Drug-Eluting Coating: Specialized coatings used primarily in cardiology to deliver localized therapy and prevent restenosis.
- Anti-Thrombogenic Coating: Critical for blood-contacting devices like oxygenators and vascular grafts to prevent the formation of blood clots.
- Others: Includes hydrophobic and radiopaque coatings.
By Application:
- Infectious Diseases: Focuses on antimicrobial protection for diagnostic and treatment tools used in high-risk environments.
- General Surgery: The largest application segment, covering a wide array of everyday surgical instruments and consumables.
- Orthopedic: Concentrates on improving the wear resistance and bone integration of joint and spinal implants.
- Neurology: The fastest-growing segment, utilizing advanced micro-coatings for neurovascular catheters and brain-stimulation leads.
- Others: Includes cardiovascular, dentistry, and gynecology applications.
By Geography:
- North America
- Europe
- Asia Pacific
- South & Central America
- Middle East & Africa
Asia-Pacific is expected to grow fastest in the coming years. This growth is fueled by massive infrastructure investments in China and India, alongside a shift toward domestic procurement. Emerging markets in South & Central America, the Middle East, and Africa also present untapped opportunities as they modernize clinical facilities and adopt minimally invasive surgical standards.
The medical device coating market is transitioning toward advanced surface modification as manufacturers seek to improve device efficacy and patient safety. Below is a summary of market share and trends by region:
North America
- Market Share: Dominates the global landscape, driven primarily by the United States.
- Key Drivers:
- Strong innovation ecosystem with over 200 FDA 510(k) approvals for coated devices.
- Significant NIH funding exceeding $1 billion for biomaterials research supporting high-end R&D.
- Robust reimbursement systems and high procedure volumes for cardiovascular and orthopedic surgeries.
- Trends: Market maturation is leading to a focus on nanotechnology and smart coatings that enhance device efficacy by up to 30% in minimally invasive applications.
Europe
- Market Share: Holds a strong global presence, led by Germany, the UK, and Switzerland.
- Key Drivers:
- Compliance with the stringent EU MDR (Medical Device Regulation) framework, which has spurred a 20% increase in new product development.
- Rising healthcare needs of an aging population requiring long-term orthopedic and neurological implants.
- Strategic clusters in the Netherlands and Switzerland specializing in precision coating for high-tech medical tools.
- Trends: Shift toward prioritizing milk-based bioresorbable coatings and antimicrobial surfaces to meet the demands of eco-conscious and safety-focused European healthcare systems.
Asia-Pacific
- Market Share: The fastest-growing region, with China serving as a global manufacturing powerhouse.
- Key Drivers:
- Rapid urbanization and increasing disposable incomes are leading to a preference for advanced westernized healthcare solutions.
- Government mandates for medical self-sufficiency, such as China's target for 70% domestic procurement in diagnostic imaging.
- High demand for premium, clean-label medical tools in the pediatric and geriatric segments.
- Trends: Heavy reliance on OEM partnerships and B2B contracts for high-end hydrophilic coatings used in the burgeoning cardiovascular sector.
South and Central America
- Market Share: Emerging market with a growing manufacturing sector in countries like Brazil and Chile.
- Key Drivers:
- Modernization of small-scale medical device firms into commercial-grade operations to supply urban healthcare hubs.
- Rising awareness of the benefits of antimicrobial coatings in reducing hospital-acquired infections (HAIs).
- Trends: Growth of boutique contract coating services and the introduction of specialized coatings for dental and aesthetic medical devices.
Middle East and Africa
- Market Share: Developing market with South Africa and Saudi Arabia leading the transition toward formalized commercial production.
- Key Drivers:
- Strategic investments in hospitals to improve local health security and reduce reliance on high-cost imports.
- Traditional presence of large-scale public health initiatives driving demand for affordable, high-volume coated disposables like syringes and catheters.
- Trends: Implementation of modern thin-film deposition technologies to formalize the local manufacturing market, coupled with a focus on high-nutrient pediatric device coatings.
High Market Density and Competition
Competition is intensifying due to the presence of established leaders such as Surmodics, Inc., Biocoat Incorporated, and DSM Biomedical. Specialized technical players and regional contract manufacturers also contribute to a diverse and rapidly expanding market landscape.
This competitive environment pushes vendors to differentiate through:
- Advanced Formulation Science: Developing proprietary coating chemistries that offer superior durability and can be applied to difficult-to-coat substrates like nitinol and PEEK.
- Regulatory Packaging: Providing pre-validated coating data and master files to help device manufacturers accelerate their FDA and MDR approval processes.
- Technological Integration: Utilizing new processes like UV curing and plasma-enhanced deposition to improve production efficiency and reduce environmental impact.
Opportunities and Strategic Moves
- Expansion into Neurovascular and Cardiology: Focus on high-margin segments where thin-film coatings are critical for the functionality of life-saving devices.
- Sustainable Manufacturing: Adopting water-based and low-VOC coating processes to align with global environmental goals and appeal to hospitals seeking ethical supply chains.
- Koninklijke DSM NV
- Hydromer Inc
- Surmodics Inc
- Biocoat Inc
- AST Products Inc
- Covalon Technologies Ltd
- Harland Medical Systems Inc
- Precision Coating Company Inc
- Kisco Ltd
- Formacoat LLC
Disclaimer: The companies listed above are not ranked in any particular order.
Medical Device Coating Market News and Recent Developments- In February 2026, Hydromer, Inc., a leader in hydrophilic, thromboresistant, and antimicrobial coating technologies for over 40 years, announced its expansion into the manufacturing and global supply of automated high-speed coating and UV curing equipment. By integrating proprietary coatings with high-performance machinery, Hydromer now provides a comprehensive, end-to-end solution for medical device manufacturers worldwide.
- In January 2026, Formacoat announced the launch of HydroMark™, its proprietary platform of hydrophilic coatings, marking a major milestone in the company’s evolution from contract coating application to full-service coating service innovator.
The Medical Device Coating Market Size and Forecast (2021–2034) report provides a detailed analysis of the market covering the areas:
- Medical Device Coating Market size and forecast at global, regional, and country levels for all the key market segments covered under the scope
- Medical Device Coating Market trends, as well as market dynamics such as drivers, restraints, and key opportunities
- Detailed PEST and SWOT analysis
- Medical Device Coating Market analysis covering key market trends, global and regional framework, major players, regulations, and recent market developments
- Industry landscape and competition analysis covering market concentration, heat map analysis, prominent players, and recent developments in the Medical Device Coating Market.
- Detailed company profiles
Report Coverage
Revenue forecast, Company Analysis, Industry landscape, Growth factors, and Trends
Segment Covered
Material Type, Device Type, Coating, and Application
Regional Scope
North America, Europe, Asia Pacific, Middle East & Africa, South & Central America
Country Scope
Argentina, Australia, Brazil, Canada, China, France, Germany, India, Italy, Japan, Mexico, Saudi Arabia, South Africa, South Korea, Spain, United Arab Emirates, United Kingdom, United States
Frequently Asked Questions
Healthcare providers are increasingly prioritizing technologies that reduce contamination and healthcare-associated infections. This is encouraging greater adoption of antimicrobial surface technologies and stimulating investment in advanced protective coating platforms.
Key competitive factors include coating durability, biocompatibility, regulatory expertise, customization capabilities, manufacturing scalability, intellectual property portfolios, and the ability to support customers throughout product development and commercialization.
Hydrophilic coatings represent the largest coating category due to their extensive use in catheters, guidewires, and minimally invasive devices. Their ability to reduce friction and improve procedural efficiency supports widespread adoption across multiple therapeutic areas.
Asia Pacific is projected to record the strongest expansion due to increasing healthcare investments, growing medical device manufacturing capacity, expanding patient access to advanced treatments, and supportive government initiatives promoting domestic production.
The study indicates growing focus on multifunctional coatings, advanced biomaterials, drug-delivery technologies, and surface engineering solutions capable of simultaneously improving safety, performance, durability, and patient outcomes.
- Koninklijke DSM NV
- Hydromer Inc
- Surmodics Inc
- Biocoat Inc
- AST Products Inc
- Covalon Technologies Ltd
- Harland Medical Systems Inc
- Precision Coating Company Inc
- Kisco Ltd
- Formacoat LLC
The Insight Partners performs research in 4 major stages: Data Collection & Secondary Research, Primary Research, Data Analysis and Data Triangulation & Final Review.
- Data Collection and Secondary Research:
As a market research and consulting firm operating from a decade, we have published many reports and advised several clients across the globe. First step for any study will start with an assessment of currently available data and insights from existing reports. Further, historical and current market information is collected from Investor Presentations, Annual Reports, SEC Filings, etc., and other information related to company’s performance and market positioning are gathered from Paid Databases (Factiva, Hoovers, and Reuters) and various other publications available in public domain.
Several associations trade associates, technical forums, institutes, societies and organizations are accessed to gain technical as well as market related insights through their publications such as research papers, blogs and press releases related to the studies are referred to get cues about the market. Further, white papers, journals, magazines, and other news articles published in the last 3 years are scrutinized and analyzed to understand the current market trends.
- Primary Research:
The primarily interview analysis comprise of data obtained from industry participants interview and answers to survey questions gathered by in-house primary team.
For primary research, interviews are conducted with industry experts/CEOs/Marketing Managers/Sales Managers/VPs/Subject Matter Experts from both demand and supply side to get a 360-degree view of the market. The primary team conducts several interviews based on the complexity of the markets to understand the various market trends and dynamics which makes research more credible and precise.
A typical research interview fulfils the following functions:
- Provides first-hand information on the market size, market trends, growth trends, competitive landscape, and outlook
- Validates and strengthens in-house secondary research findings
- Develops the analysis team’s expertise and market understanding
Primary research involves email interactions and telephone interviews for each market, category, segment, and sub-segment across geographies. The participants who typically take part in such a process include, but are not limited to:
- Industry participants: VPs, business development managers, market intelligence managers and national sales managers
- Outside experts: Valuation experts, research analysts and key opinion leaders specializing in the electronics and semiconductor industry.
Below is the breakup of our primary respondents by company, designation, and region:
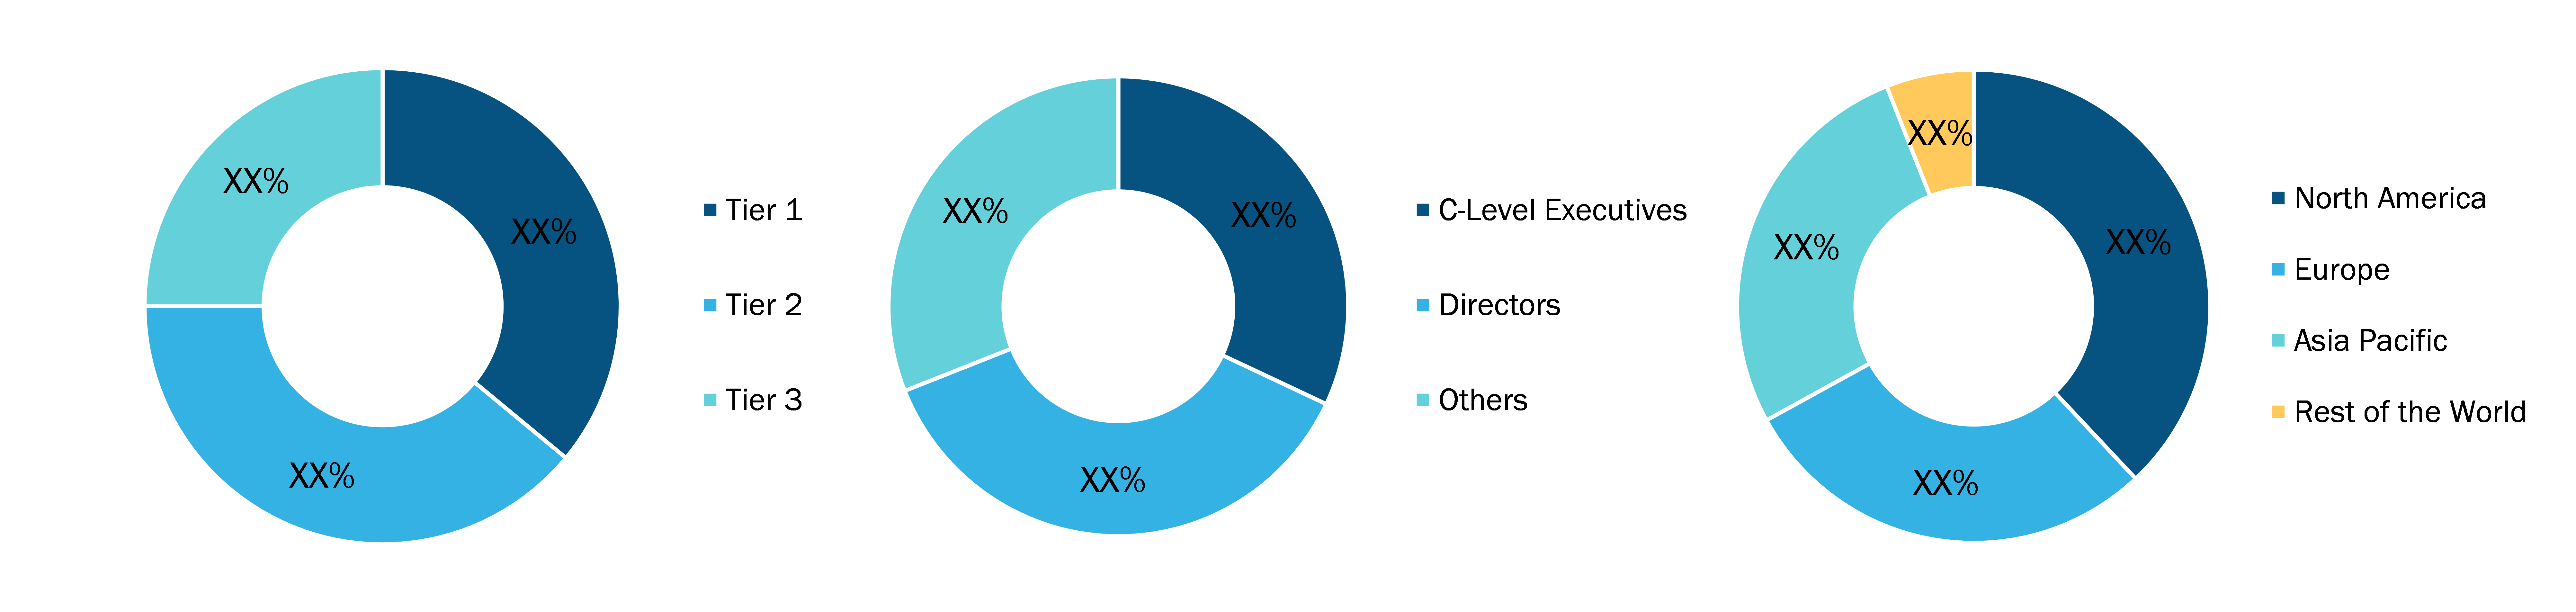
Once we receive the confirmation from primary research sources or primary respondents, we finalize the base year market estimation and forecast the data as per the macroeconomic and microeconomic factors assessed during data collection.
- Data Analysis:
Once data is validated through both secondary as well as primary respondents, we finalize the market estimations by hypothesis formulation and factor analysis at regional and country level.
- 3.1 Macro-Economic Factor Analysis:
We analyse macroeconomic indicators such the gross domestic product (GDP), increase in the demand for goods and services across industries, technological advancement, regional economic growth, governmental policies, the influence of COVID-19, PEST analysis, and other aspects. This analysis aids in setting benchmarks for various nations/regions and approximating market splits. Additionally, the general trend of the aforementioned components aid in determining the market's development possibilities.
- 3.2 Country Level Data:
Various factors that are especially aligned to the country are taken into account to determine the market size for a certain area and country, including the presence of vendors, such as headquarters and offices, the country's GDP, demand patterns, and industry growth. To comprehend the market dynamics for the nation, a number of growth variables, inhibitors, application areas, and current market trends are researched. The aforementioned elements aid in determining the country's overall market's growth potential.
- 3.3 Company Profile:
The “Table of Contents” is formulated by listing and analyzing more than 25 - 30 companies operating in the market ecosystem across geographies. However, we profile only 10 companies as a standard practice in our syndicate reports. These 10 companies comprise leading, emerging, and regional players. Nonetheless, our analysis is not restricted to the 10 listed companies, we also analyze other companies present in the market to develop a holistic view and understand the prevailing trends. The “Company Profiles” section in the report covers key facts, business description, products & services, financial information, SWOT analysis, and key developments. The financial information presented is extracted from the annual reports and official documents of the publicly listed companies. Upon collecting the information for the sections of respective companies, we verify them via various primary sources and then compile the data in respective company profiles. The company level information helps us in deriving the base number as well as in forecasting the market size.
- 3.4 Developing Base Number:
Aggregation of sales statistics (2020-2022) and macro-economic factor, and other secondary and primary research insights are utilized to arrive at base number and related market shares for 2022. The data gaps are identified in this step and relevant market data is analyzed, collected from paid primary interviews or databases. On finalizing the base year market size, forecasts are developed on the basis of macro-economic, industry and market growth factors and company level analysis.
- Data Triangulation and Final Review:
The market findings and base year market size calculations are validated from supply as well as demand side. Demand side validations are based on macro-economic factor analysis and benchmarks for respective regions and countries. In case of supply side validations, revenues of major companies are estimated (in case not available) based on industry benchmark, approximate number of employees, product portfolio, and primary interviews revenues are gathered. Further revenue from target product/service segment is assessed to avoid overshooting of market statistics. In case of heavy deviations between supply and demand side values, all thes steps are repeated to achieve synchronization.
We follow an iterative model, wherein we share our research findings with Subject Matter Experts (SME’s) and Key Opinion Leaders (KOLs) until consensus view of the market is not formulated – this model negates any drastic deviation in the opinions of experts. Only validated and universally acceptable research findings are quoted in our reports.
We have important check points that we use to validate our research findings – which we call – data triangulation, where we validate the information, we generate from secondary sources with primary interviews and then we re-validate with our internal data bases and Subject matter experts. This comprehensive model enables us to deliver high quality, reliable data in shortest possible time.
 Get Free Sample For