
Industrial Gases for Glass Industry Market Size, Growth & Trends by 2034
Industrial Gases for Glass Industry Market Size and Forecasts (2021–2034), Global and Regional Share, Trends, and Growth Opportunity Analysis Report Coverage : by Gas Type (Nitrogen, Oxygen, Hydrogen); Storage and Distribution (Cylinder and Packaged Gas, Merchant Liquid Distribution, Tonnage Distribution); Glass Type (Container Glass, Flat Glass, Glass Fiber); Function (Forming and Melting, Atmospheric Control, Finishing/Polishing); and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00039885
- Category : Chemicals and Materials
- No. of Pages : 150
- Available Report Formats :


- Last update date : September 01, 2026


2025 Market Size
US$ 5.78 Bn
Base year value
2034 Forecast
US$ 12.34 Bn
Projected by 2034
CAGR 2026-2034
8.79 %
Growth rate
Addressable Market
US$ 81.16 Bn
(2026-2034)
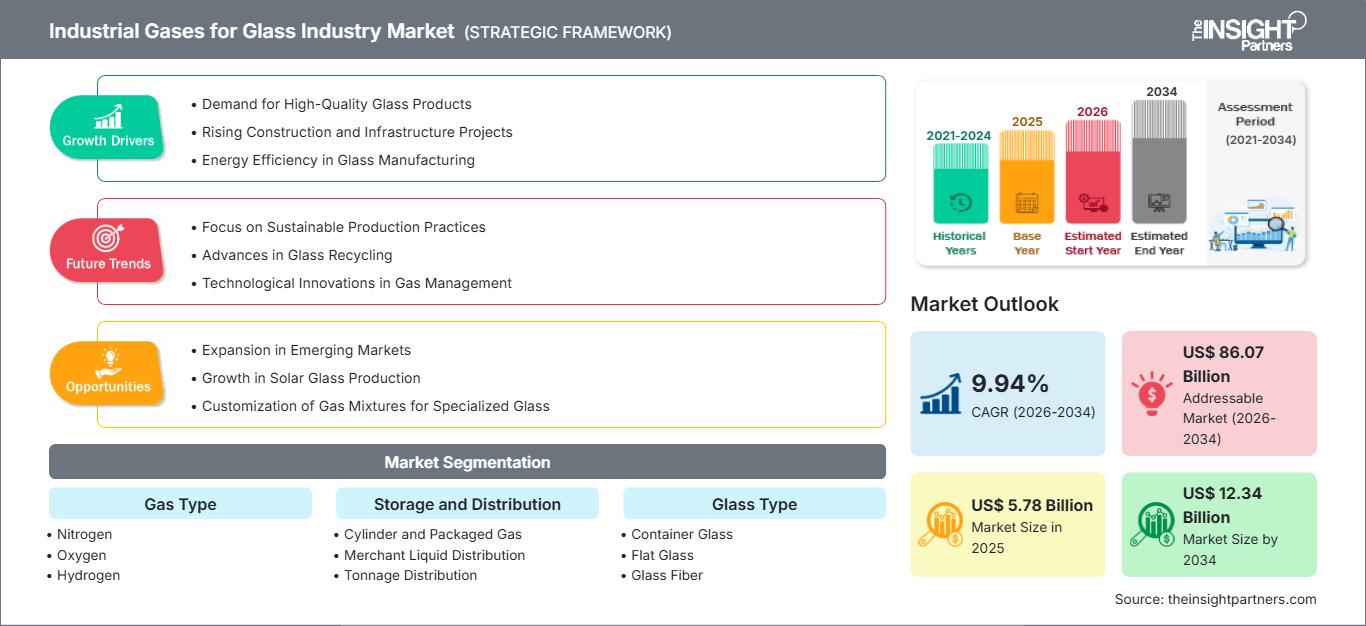
The Industrial Gases For Glass Industry market was valued at US$ 5.78 billion in 2025 and is expected to reach US$ 12.34 billion by 2034; it is estimated to record a CAGR of 8.79% during 2026-2034.
Industrial Gases for Glass Industry Market Assessment and Insights
- North America is estimated at a 25–29% share in 2025, growing at a CAGR of 8.9–9.6% between 2026–2034, supported by furnace upgrades and energy-efficiency investments.
- US is estimated at 78–82% of North America's 2025 demand, growing at a CAGR of 8.8–9.5% between 2026–2034, led by container and flat glass production.
- Europe is estimated at a 24–28% share in 2025, growing at a CAGR of 8.7–9.4% between 2026–2034, led by Germany, Italy, France, the UK, and Spain.
- Asia Pacific is estimated at a 34–38% share in 2025, growing at a CAGR of 10.4–11.2% between 2026–2034, led by China, Japan, South Korea, and India.
- Largest Segment is Oxygen, with a 52–56% market share in 2025 and a CAGR of 9.7–10.3% between 2026–2034, reflecting its central combustion role.
- High Growth Segment is Hydrogen, with an 11–15% market share in 2025 and a CAGR of 11.5–12.5% between 2026–2034, supported by controlled atmospheres.
- Key companies analyzed in detail: Linde plc, Air Liquide S.A., Air Products and Chemicals, Inc., Messer SE & Co. KGaA, Taiyo Nippon Sanso Corporation, Iwatani Corporation, Gulf Cryo Holding RSC Limited, Southern Industrial Gas Sdn. Bhd., Nippon Gases, Air Water Inc.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
Production economics are changing from mere molecule production to combustion, atmosphere control, and equipment integration. Oxygen enrichment and oxy-fuel technologies offer possibilities of increased thermal efficiency while reducing the amount of flue gases produced, while nitrogen and hydrogen provide the basis for controlled atmosphere conditions. The importance of production, bulk liquid provision, telecommunication, and engineering services becomes increasingly important in the supplier choice process as these link gas supply with furnace performance and emissions.
In future, the emergence of new glass clusters and furnace retrofitting initiatives would result in an increase in demand for onsite oxygen, nitrogen generation, hydrogen readiness, storage capacity, and digital monitoring. Increasing demands in terms of combustion emissions and energy efficiency would favor technologies that optimize gas use while ensuring production capacity. Supplie.rs offering molecule, equipment, engineering and services would have a competitive edge.
Industrial Gases for Glass Industry Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 5.78 Billion |
| Market Size by 2034 | US$ 12.34 Billion |
| Global CAGR (2026 - 2034) | 8.79% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Industrial Gases for Glass Industry Market Analysis
Demand is based on energy intensity of glass melting processes and stable process conditions. Oxygen guarantees high combustion intensity; nitrogen and hydrogen play the role in forming of controlled atmosphere. Ecosystem includes gas producers, plants for air separation, storages, pipes, burners, furnace integration companies, glass manufacturers, and logistics companies. Economics of supply depends on degree of capacity use, cost of electricity, distance of delivery, and density of goods.
Value creation is becoming more and more specific as it relates to application-related gas programs. Big glass-producing facilities tend to opt for tonnage or local gas supply in case of sufficient demand for building specific infrastructure. In turn, small glass processors usually use bottled gas or packaged gas. Contract arrangements can include minimum volumes, indexed prices, equipment ownership, and contingency gas supply. Reliability is extremely important as furnace downtime can lead to significant production losses.
The competitive environment consists of international gas companies alongside regional suppliers who compete on the basis of proximity, logistics flexibility, and glass applications specialization. Linde plc focuses on gas technologies and onsite solutions, whereas Air Liquide S.A. specializes in oxy-combustion engineering and gas supply. In its turn, Air Products and Chemicals, Inc. and Messer SE & Co. KGaA are competing on the basis of comprehensive industrial gas portfolio. The list of regional competitors includes Taiyo Nippon Sanso Corporation, Iwatani Corporation, Gulf Cryo Holding RSC Limited, and Southern Industrial Gas Sdn. Bhd.
Positioning is becoming more and more dependent on onsite production, furnace engineering, hydrogen availability, and low carbon solutions. Besides, Nippon Gases and Air Water Inc. provide regional coverage, whereas established suppliers are able to leverage their production and bulk liquid networks to decrease delivered prices. As a result, capital expenditures will be most probably made in highly consuming glass clusters where dedicated plants could be more efficiently utilized.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Industrial Gases for Glass Industry Market: Strategic Insights
Regional Insights
North America Industrial gases for glass industry market
North America is projected to claim a 25-29% industrial gases for glass industry market share in 2025 and grow at a CAGR of 8.9-9.6% till 2034. The market enjoys well-established container and flat glass manufacturing, furnace cycles, and emphasis on energy efficiency. The United States leads regional demand, whereas Canada participates via niche glass and industrial applications. Buyers consider not only conventional gas prices but also reliability of the supply chain, economics of onsite generation, and emissions.
The growth drivers include modernization of the combustion technology, as well as the oxygen enrichment of the melting process. For example, glass manufacturers aiming for higher capacity can enrich the combustion process with oxygen. On the other hand, nitrogen enables inerting and process protection. Hydrogen is becoming an interesting option due to its potential in low-carbon thermal processes. Suppliers' competitiveness lies in engineering, multiple storage, and gas supply integration with furnace controls.
U.S. Industrial gases for glass industry Market
The US represents approximately 78–82% of North America's 2025 demand and is projected to grow at a CAGR of 8.8–9.5% through 2034. Its market is supported by container-glass production, architectural and automotive flat glass, and specialty applications. Large facilities favor bulk and onsite models because continuous furnace operation requires dependable oxygen and nitrogen availability. Supplier presence includes Linde plc, Air Liquide S.A., Air Products and Chemicals, Inc., and Messer SE & Co. KGaA.
Trends in applications include a shift towards oxygen-fired combustion, nitrogen blanketing, and better furnace atmosphere management. Hydrogen is relatively smaller but still strategically significant because of its use in tin bath atmospheres of float glass production and low-carbon combustion tests. Purchasing is also increasingly based on total cost of delivery, alternative supplies, purity, integration with equipment, and service support. This will likely benefit suppliers that can offer contractual stability along with local presence and process engineering capability.
Europe Industrial gases for glass industry Market
Europe is estimated at a 24–28% share in 2025 and is expected to grow at a CAGR of 8.7–9.4% through 2034. Germany is a leading market, followed by Italy, France, the UK, and Spain. Furnace efficiency programs, emissions requirements, and replacement of older combustion systems support demand for oxygen, nitrogen, and hydrogen-based process solutions.
Germany enjoys a wide scope of industrial manufacturing and demands for flat, container, and specialty glass. Italy is still significant in terms of its involvement in container and tableware manufacturing, while France combines both packaging and specialty usage of glass. The UK and Spain participate through their activities in the area of container, flat, and fiber manufacturing.
APAC Industrial gases for glass industry Market
APAC is projected to capture a share of 34–38% in 2025, growing at a CAGR of 10.4–11.2% until 2034 to become the largest regional market. China is the major region of demand, whereas Japan, South Korea, India, and Australia play their role via existing and emerging glass applications.
Industries, construction, automobiles, electronics, and solar glasses drive local consumption. Emphasis on efficiency and reduction of emissions contributes to increased oxygen enrichment, local production, and efficient furnaces. It is expected that China will continue to lead while India and Southeast Asia present additional opportunities through capacity additions.
Middle East & Africa Industrial gases for glass industry Market
Middle East and Africa region expected to experience growth of CAGR between 8.0% and 8.8% till 2034. Industrial diversification and development of infrastructure drive the Saudi Arabian and UAE market, while South African market depends on existing manufacturing demand. Other markets of the region provide demand via construction, packaging, and emerging industrial hubs.
The Saudi Arabian market is projected to be the largest regional market due to development of manufacturing investments. Infrastructure and logistics development drive the UAE market, while South African market depends on the presence of comparatively developed consumer base. Availability of energy, implementation of infrastructure projects, and presence of gas assets affect the economics of supply.
Segmentation Analysis
Gas Type
Gas Type segment in the industrial gases for glass industry market is projected to grow at a CAGR of 9.7–10.4% during 2026–2034. Oxygen remains central to combustion improvement, nitrogen supports inerting and atmospheric control, and hydrogen provides an emerging pathway for controlled atmospheres and lower-carbon process experimentation. Adoption varies with furnace design, glass type, plant scale, and emissions objectives.
- Nitrogen: Supports inerting, purging, forming environments, and float-glass atmosphere control, making reliable purity and continuous delivery strategically important for oxidation protection.
- Oxygen: Holds the largest position because oxygen-assisted and oxy-fuel combustion can improve heat transfer, reduce flue-gas volume, and support productivity and emissions management.
- Hydrogen: Represents an emerging molecule for controlled atmospheres and selected combustion applications, gaining importance as producers evaluate lower-carbon thermal processes.
Storage and Distribution
Storage and Distribution segment in the industrial gases for glass industry market is expected to advance at a CAGR of 9.3–9.9% during 2026–2034. The preferred model depends on consumption volume, continuity requirements, site location, and infrastructure economics. Large furnaces increasingly favor dedicated arrangements, whereas smaller facilities require flexible packaged delivery.
- Cylinder and Packaged Gas: Serves lower-volume and intermittent requirements, providing flexibility for finishing, maintenance, laboratory, and specialty applications where dedicated infrastructure is uneconomic.
- Merchant Liquid Distribution: Supports medium-to-high consumption sites through cryogenic liquids, balancing flexibility, storage capacity, delivery frequency, and investment requirements without dedicated production assets.
- Tonnage Distribution: Fits large glass plants with sustained consumption, enabling dedicated pipelines or onsite assets, strong continuity, and integration between gas supply and furnace operations.
Glass Type
Glass Type segment in the industrial gases for glass industry market is forecast to expand at a CAGR of 9.5–10.1% during 2026–2034. Container, flat, and fiber glass differ in furnace configuration, production scale, atmosphere requirements, and finishing processes. These differences shape gas intensity and preferred supply models.
- Container Glass: Requires high-volume, continuous furnace operation, creating strong demand for oxygen, process control, and dependable bulk or onsite gas supply.
- Flat Glass: Uses controlled atmospheres and high-temperature processing, supporting oxygen, nitrogen, and hydrogen combinations across melting and tin-bath operations.
- Glass Fiber: Requires stable melting and forming conditions, with gas solutions supporting thermal efficiency, atmosphere management, product consistency, and specialized processing.
Function
Function segment in the industrial gases for glass industry market is projected to grow at a CAGR of 9.8–10.4% during 2026–2034. Gas demand spans primary melting, atmospheric control, and downstream finishing. Suppliers increasingly package gases with burners, controls, monitoring, and technical services to improve process outcomes.
- Forming and Melting: Represents the core gas-intensive stage, where oxygen supports combustion efficiency and controlled gas conditions help stabilize quality and throughput.
- Atmospheric Control: Uses nitrogen and hydrogen to protect surfaces, manage oxidation, and maintain controlled environments, particularly in float-glass and specialized forming operations.
- Finishing/Polishing: Uses process gases in surface treatment and polishing applications, where purity, controlled flow, and application-specific equipment influence finish quality.
Opportunity Snapshot
| Glass Type | Revenue Contribution (High/Medium/Low) | Trend Tag (MAX 2 words) | Adoption Stage (Emerging/Scaling/Mature) |
| Container Glass | High | Furnace Efficiency | Mature |
| Flat Glass | High | Float Inerting | Mature |
| Glass Fiber | Medium | Fiber Quality | Scaling |
Industrial Gases for Glass Industry Market Growth Drivers and Impact Analysis
Furnace efficiency and emissions-control requirements
Glass furnaces operate continuously and consume substantial thermal energy, making combustion efficiency a direct determinant of production economics. Oxygen-assisted combustion can intensify heat transfer while reducing nitrogen entering the furnace, supporting lower flue-gas loads and emissions management. As producers face tighter environmental expectations, gas suppliers gain opportunities to retrofit furnaces with oxygen delivery, burners, controls, and monitoring. The commercial effect extends beyond gas volumes because customers may purchase engineering services, equipment, maintenance, and long-term supply contracts together. Furnace modernization can therefore expand both molecule demand and technical-service revenue.
Expansion of high-throughput glass manufacturing capacity
New and expanded container, flat, and fiber glass facilities require dependable gas infrastructure from commissioning. Large furnaces typically operate with long campaigns, so gas interruptions can create disproportionate operational losses. This encourages producers to select suppliers able to provide dedicated storage, backup inventory, onsite generation, and technical response. Capacity additions also create opportunities to design gas systems around the furnace, improving pipeline layouts, pressure management, and equipment integration. Suppliers with established production assets near glass clusters can achieve stronger utilization and lower logistics costs, supporting long-duration contracts and deeper customer integration.
Digitalized gas management and process optimization
Digital controls are becoming more relevant as glass manufacturers seek tighter furnace stability, lower specific energy consumption, and predictable quality. Sensors, flow meters, remote monitoring, and automated controls can connect gas delivery with furnace conditions, identifying abnormal consumption or pressure deviations earlier. For suppliers, digitalization differentiates service offerings beyond commodity supply. Data-enabled contracts can support performance monitoring, preventive maintenance, delivery planning, and onsite asset optimization. The impact is particularly meaningful for multi-furnace groups seeking consistent operating practices. Over time, digital integration can also align liquid deliveries with actual consumption and production output, reducing emergency deliveries and strengthening integrated supply agreements.
Industrial Gases for Glass Industry Market Future Trends
Hydrogen-ready glassmaking infrastructure
Hydrogen is likely to move from limited experimentation toward selective commercial deployment where furnace design, burner capability, hydrogen availability, and economics align. New furnaces and major rebuilds can incorporate greater fuel flexibility, allowing producers to test hydrogen blends or dedicated combustion without rebuilding the entire gas infrastructure. Suppliers can capture value through hydrogen, blending systems, storage, controls, and engineering support. Hydrogen used with nitrogen in controlled atmospheres will remain relevant for float-glass production. The longer-term trend involves designing plants capable of responding to changing energy markets and carbon policies while maintaining production reliability.
Integrated onsite oxygen and nitrogen generation
Onsite generation in the industrial gases for glass industry market trends is expected to become more attractive at large glass facilities where sustained gas consumption supports dedicated equipment. The model can reduce dependence on frequent bulk deliveries and provide greater control over pressure, purity, and continuity. Compact generation technologies should make onsite systems accessible to additional facilities, particularly where logistics are difficult or expansion requires predictable capacity. Suppliers are likely to combine equipment ownership with long-term service contracts, transferring capital and operational responsibilities from glass manufacturers. Remote monitoring and predictive maintenance can improve availability. Adoption will depend on electricity costs, utilization rates, backup requirements, and merchant-liquid economics.
Industrial Gases for Glass Industry Market Opportunities
Dedicated gas infrastructure for emerging glass clusters
Emerging glass manufacturing clusters provide an opportunity to establish integrated gas ecosystems before individual plants become dependent on fragmented supply. Suppliers can develop production hubs, bulk-liquid terminals, cylinder capacity, and pipeline networks around high-consumption zones. Early participation can secure anchor customers and improve asset utilization as furnaces are commissioned. The strongest opportunities are likely where container, flat, solar, and fiber-glass producers operate within practical delivery distances. Commercial structures can combine long-term commitments with onsite generation and backup supply. For investors, attractiveness depends on customer density, electricity economics, infrastructure availability, and expected utilization. Partnerships with furnace technology providers can strengthen positioning by allowing gas systems to be specified during engineering.
Low-carbon gas solutions bundled with furnace modernization
Furnace rebuild cycles create an opportunity in the industrial gases for glass industry market forecast to sell gas, equipment, engineering, and emissions-reduction services as a modernization package. Suppliers can combine oxygen delivery, advanced burners, heat recovery, controls, nitrogen systems, and hydrogen-ready infrastructure according to the customer's production pathway. This approach allows customers to evaluate decarbonization investments against fuel consumption, throughput, emissions intensity, and maintenance requirements. The opportunity is particularly relevant in mature markets where greenfield capacity is limited but aging furnaces require rebuilding. Suppliers with established engineering teams and customer relationships are positioned to influence technology selection early. Financing or build-own-operate models could further reduce adoption barriers for capital-intensive onsite systems.
Recent Developments
- April 2026: Air Products expanded its US industrial gas footprint with plans to build, own and operate a new air separation unit (ASU) in Cocoa, Florida, reinforcing its push into high-demand industrial and space-sector markets.
- September 2026: Air Liquide S.A. reported deployment of its HeatOx technology at Verallia's new oxy-combustion glass furnace in Campo Bom, Brazil. The installation recovers furnace flue-gas heat to preheat oxygen and natural gas, with the company reporting up to 20% lower carbon emissions versus conventional furnaces and additional production capacity of about 820 tonnes per day.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for