
Square Flanges Market Growth, Share & Trends by 2034
Coverage: By Product Type (SHAB, SHB, LSA); Industry (Chemical Processing, Petrochemical, Oil and Gas, Nuclear Power, Shipbuilding, Others) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00020428
- Category : Manufacturing and Construction
- No. of Pages : 150
- Available Report Formats :


- Last update date : October 30, 2026


2025 Market Size
US$ 1.29 Bn
Base year value
2034 Forecast
US$ 1.85 Bn
Projected by 2034
CAGR 2026-2034
4.15 %
Growth rate
Addressable Market
US$ 14.31 Bn
(2026-2034)
The Square Flanges Market was valued at US$ 1.29 Billion in 2025 and is projected to reach US$ 1.85 Billion by 2034, registering a CAGR of 4.15% during 2026–2034. The market covers square flange products used to create detachable, pressure-resistant connections between piping and equipment. Demand is closely linked to industrial piping maintenance, process plant expansion, fluid handling infrastructure, and replacement requirements across chemical processing, petrochemical, oil and gas, nuclear power, and shipbuilding applications.
Across North America, procurement is supported by replacement of aging process infrastructure, refinery and petrochemical maintenance, and continued requirements for standardized piping components. The regional CAGR is modeled at ~3% through 2034, reflecting mature industrial infrastructure and a relatively high installed base. Demand is also influenced by stringent quality expectations, traceability requirements, pressure-rated connection specifications, and preference for corrosion-resistant materials in demanding process environments. The Square Flanges Market size therefore remains closely connected to maintenance expenditure and industrial capital investment rather than consumer-driven demand.
Square Flanges Market Assessment and Insights
Regional Outlook
- North America: ~22% of the global Square Flanges Market share in 2025 | ~3% CAGR through 2034. Market position: North America represents a mature demand center supported by established process industries, refinery infrastructure, chemical manufacturing, and replacement requirements. Procurement emphasizes specification compliance, material traceability, pressure performance, and reliable delivery for maintenance-intensive applications.
- US: ~82% of North American market revenue in 2025 | ~3% CAGR through 2034. Market position: The US accounts for most regional demand, supported by extensive oil and gas, refining, chemical processing, and industrial piping infrastructure. Replacement activity and engineered project requirements sustain demand for specialized and standard-compliant flange configurations.
- Europe: ~24% of the global market in 2025 | ~3% CAGR through 2034. Market position: Europe is a mature market with established process engineering and shipbuilding capabilities. Germany represents the leading country in Europe, while the UK, France, Italy, and Spain contribute through energy, chemical, marine, manufacturing, and infrastructure applications.
- Asia Pacific: ~40% of the global market in 2025 | ~5% CAGR through 2034. Market position: Asia Pacific is the largest and fastest-growing regional market, supported by industrialization, petrochemical capacity additions, shipbuilding, chemical manufacturing, and expanding process infrastructure. China is the leading country in Asia Pacific, with Japan, South Korea, India, and Australia contributing differentiated demand.
Segment Outlook
- Product Type: ~52% Share in 2025 | ~4% CAGR through 2034. Market position: Product Type represents the largest main segment because square flange purchasing is driven by application-specific connection requirements, dimensional compatibility, pressure conditions, and installed piping configurations. SHAB, SHB, and LSA designs address different connection and sealing requirements.
- Industry: ~48% Share in 2025 | ~5% CAGR through 2034. Market position: Industry is the higher-growth main segment as new process capacity, energy infrastructure, chemical facilities, shipbuilding projects, and equipment replacement create recurring requirements for engineered piping connections and corrosion-resistant flange materials.
Competitive Coverage
Fit-Wel Industries LLP, Honesty Metal Industries, Kalikund Steel & Engineering Company, Metalfar, Metal Tech Engineers, Metal Udyog, RFS Hydraulics Sdn Bhd, Ranflex Metals, Rexino Stainless & Alloys, SP Metals
Methodology
The Insight Partners follows Data Collection & Secondary Research, Primary Research, Data Analysis, and Data Triangulation & Final Review to validate market estimates and insights.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The Square Flanges Market has shifted from being a commodities-based market to one that involves engineering connections tailored to various applications. Distinguishing factors among manufacturers are now based on material availability, dimensional tolerances, pressure class suitability, documentations, machining capabilities, and customization. The range of product offerings includes materials such as stainless steel, carbon steel, alloy steel, duplex steel, and high alloy materials where there are special needs regarding corrosion and temperatures. This reflects the growing need for international standards and custom specifications in the current supplier portfolio, especially in industrial export applications.
Looking to the future, the demand in the Square Flanges Market will be further diversified geographically because of the growth in production capacity in the Asia Pacific region and the sustained investments made by economies in the Middle East in energy and process infrastructure development. The application of Square Flanges in ship building and marine engineering will continue to be important in countries where there is already an ecosystem supporting the manufacture of vessels. The need for certification of materials and pressure integrity, among other qualifications, will further sustain supplier qualification.
Square Flanges Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 1.29 Billion |
| Market Size by 2034 | US$ 1.85 Billion |
| Global CAGR (2026 - 2034) | 4.15% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Square Flanges Market Analysis
Demand in the Square Flanges Market emanates mainly from piping applications in industries that require detachable fittings due to equipment, valve, pump, vessel, hydraulic coupling, and maintenance joints. For chemical and petrochemical processes as well as oil and gas production facilities, material specifications should withstand high pressure, temperature, and corrosion, whereas ship building involves size constraints and marine environment conditions. Hence, the Square Flanges Market growth model is associated with process capabilities, infrastructure replacement, maintenance schedules, and new piping installations.
The supply chain starts with materials such as carbon steel, stainless steel, alloy steels, duplex steels, and other specialty metals, and goes through forging or forming, machining, drilling, facing, heat treating, when necessary, inspections, certifications, stocking, and distribution. Wide material inventory in suppliers’ product lines will allow better adaptation to project-specific requirements and shortened purchasing processes. Standardization simplifies the engineering part, whereas custom sizes and specialty materials make room for value-added manufacturing services.
The Square Flanges Market report shows tha competition is still fragmented amongst specialist manufacturers, exporters, stockists, and suppliers of integrated piping components. Fit-Wel Industries LLP focuses on flanges along with the forged and butt weld fittings, while Kalikund Steel & Engineering Company deals with square flanges among a wide range of products including carbon, stainless, alloy, duplex, and high nickel. Metal Tech Engineers provides various flanges and material grades which enable cross selling amongst different industrial requirements of pipework. Ranflex Metals provides integration of flange manufacturing and stocking along with availability of different metals.
According to the Square Flanges Market report, competitive positioning is not only based on product differentiation but also specification range, delivery capabilities, quality certification, material traceability, and compatibility of international standards. Metal Udyog covers oil & gas, refining, petrochemical, and construction segments, while RFS Hydraulics caters to hydraulic, shipbuilding, marine, oil & gas, and engineering clients in Malaysia. Rexino Stainless & Alloys and SP Metals are involved in the ecosystem of specialist stainless and industrial components while Metalfar and Honesty Metal Industries boost up the supplier base.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
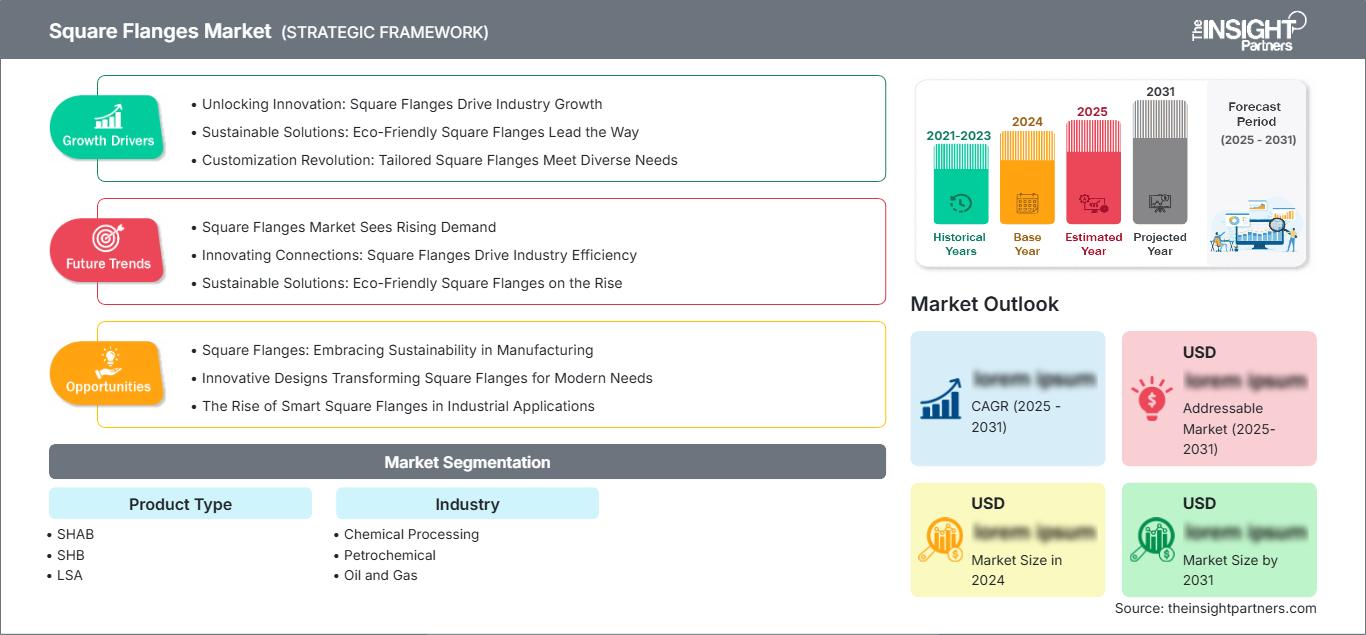
Square Flanges Market: Strategic Insights
Regional Insights
North America Square Flanges Market
The Square Flanges Market forecasts show that North America accounted for approximately ~22% of global demand in 2025 and is projected to expand at ~3% CAGR through 2034. There is a significant installed base of piping systems that will need inspection, repairs, replacements, and standardization due to the established presence of refinery facilities, petrochemical facilities, chemical processing operations, and industrial manufacturing activities within the region. Procurement practices tend to consider factors such as dimensional compatibility, pressure ratings, metallurgical properties, inspection reports, and compatibility with existing piping specifications.
The United States is estimated to account for ~82% of North American revenue in 2025 because of the higher process industry presence and the extensive oil and gas infrastructure. The need for replacement will arise from chemical plants, refineries, gas processing plants, power plants, and industrial water systems. Canada's contribution will come from energy, mining, chemicals, and industrial infrastructures. Lifecycle reliability, material traceability, and response are critical considerations in regional procurement as shutdowns could lead to high operating costs, especially unexpected ones.
U.S. Square Flanges Market
The US represents ~82% of North American revenue in 2025, with a modeled CAGR of ~3% through 2034. The demand drivers for its products are backed by the volume of refineries, petrochemical plants, natural gas plants, chemical industries, electricity generation and industrial machinery. The square flanges are sold within complete packages of pipe and equipment and hence the demand for these products is dependent on maintenance, modifications, replacements and construction projects rather than on individual product cycles.
The application needs will depend upon the pressure, temperature, nature of medium, compatibility with material and installation needs. In recent times buyers are becoming increasingly concerned about certification, dimensional tolerance, ability to conduct inspections, supply of corrosion resistant grades and delivery. Thus specialized suppliers will be able to compete with the help of their inventory and customization capabilities, while the large purchasing initiatives may benefit from the suppliers who are able to offer complete range of pipe components.
Europe Square Flanges Market
Europe represented ~24% of the global market in 2025 and is expected to grow at ~3% CAGR through 2034. Germany is the leading country in Europe, supported by a large industrial manufacturing base, chemical production, machinery engineering, and process equipment ecosystem. The UK contributes through energy infrastructure, refining, chemicals, and offshore-related applications, while France maintains demand from chemical, energy, aerospace-supporting industrial infrastructure, and marine activities.
There is high presence of manufacturing and mechanical engineering industry in Italy, which creates demand for industrial pipe products, whereas Spain provides its contribution in terms of refining, chemicals, energy sector, and shipbuilding industry. In the region, matured industrial structures lead to continuous need for replacements; in purchasing, there is an increasing focus on the lifecycle performance and certification, and not just on the low price of the acquisition. Customers in Europe work under strict compliance of product, material, safety, and environmental regulations.
Thus, the regional market demonstrates steady technical needs and moderate growth in terms of volume. Suppliers who can offer customized sizes, materials with corrosion resistance, and documentation in international standards can cater both to the needs of domestic maintenance operations and engineering projects for export. There are also opportunities in marine and offshore sectors for such suppliers.
APAC Square Flanges Market
Asia Pacific accounted for ~40% of the global market in 2025 and is modeled to expand at ~5% CAGR through 2034, making it the fastest-growing region. China is the leading country in Asia Pacific, supported by its extensive chemical, petrochemical, manufacturing, shipbuilding, and industrial infrastructure. Japan and South Korea contribute through mature manufacturing and marine industries, while India benefits from refinery expansion, chemical production, industrial infrastructure, and domestic manufacturing.
Demand is also created in Australia through energy applications, mining operations, process applications, and infrastructure projects. Demand in the region is also driven through new capacities, industrialization, shipbuilding, and process industry growth. Specified procurement is prevalent, although local sourcing and reduced delivery time are becoming more critical. Industrial capabilities in Northeast Asia, along with growth of capacity in China and India, give APAC a diverse demand base.
Middle East & Africa Square Flanges Market
Middle East and Africa demand is supported by energy infrastructure, refining, petrochemical projects, water systems, industrial processing, and large-scale infrastructure development. The region is modeled to expand at ~5% CAGR through 2034, reflecting project-driven requirements and continued investment in process facilities. Saudi Arabia is the leading country in the Middle East & Africa region where evidence supports a strong concentration of energy and downstream industrial activity.
The UAE contributes through energy, industrial processing, logistics, and infrastructure, while South Africa provides demand from mining, power, chemicals, and industrial maintenance. Rest of MEA markets are more fragmented and often depend on imported piping components and regional distributors. Suppliers with export capabilities, broad material portfolios, recognized standards, and responsive logistics can address procurement requirements where local manufacturing depth is limited. Energy transition projects may also create incremental requirements for corrosion-resistant piping components and specialized process infrastructure.
Segmentation Analysis
Product Type
Product Type represents the largest main segment, with a modeled CAGR of ~4% from 2026 to 2034. The Square Flanges Market scope within this segment is shaped by connection geometry, bolt configuration, sealing requirements, equipment compatibility, and operating conditions. SHAB, SHB, and LSA configurations serve different installation and sealing requirements, making dimensional conformity and engineering specifications central to purchasing decisions. Demand is sustained by replacement activity, new piping installation, and customized requirements in industrial equipment and process plants.
- SHAB: SHAB configurations are designed for applications requiring conventional bolted connections and compatibility with specific piping interfaces. Demand is supported by industrial maintenance and equipment installation where dimensional accuracy, bolt-hole alignment, and pressure integrity are essential.
- SHB: SHB products address connection requirements where the installation configuration differs from conventional SHAB arrangements. Their strategic importance lies in providing standardized alternatives for equipment and piping systems with defined mounting and sealing constraints.
- LSA: LSA designs support specialized connection and sealing configurations, making them relevant where equipment geometry or installation constraints require a particular flange interface. Their use is closely tied to engineering specifications and application-specific procurement.
Industry
Industry is the higher-growth main segment, with a modeled CAGR of ~5% from 2026 to 2034. Industrial expansion, maintenance spending, process equipment replacement, and new capacity additions collectively determine demand across the five specified end-use industries. The Square Flanges Market benefits when process facilities expand their piping networks or replace components exposed to pressure, thermal cycling, vibration, or corrosive media. Supplier qualification is particularly important in applications where connection failure can interrupt production or compromise safety.
- Chemical Processing: Chemical plants require flange materials and configurations compatible with corrosive chemicals, pressure variations, and demanding operating environments. Procurement prioritizes metallurgy, sealing reliability, dimensional accuracy, inspection documentation, and resistance to degradation.
- Petrochemical: Petrochemical facilities generate recurring requirements through process-unit construction, turnaround maintenance, piping modification, and equipment replacement. Material compatibility and pressure performance are important because flanges form part of critical process connections.
- Oil and Gas: Oil and gas applications cover production, gathering, processing, transmission, refining, and supporting infrastructure. Buyers emphasize pressure ratings, material certification, reliability, and compatibility with established piping standards across operating environments.
- Nuclear Power: Nuclear applications impose demanding quality, traceability, inspection, and material-control requirements. Flange procurement is consequently more qualification-intensive, with suppliers required to demonstrate consistency and documentation suitable for highly controlled engineering environments.
- Shipbuilding: Shipbuilding uses compact piping connections across propulsion, utilities, fuel, ballast, cooling, and auxiliary systems. Demand is influenced by vessel construction cycles, repair activity, marine specifications, corrosion resistance, and installation efficiency.
Opportunity Snapshot
| Industry | Revenue Contribution | Trend Tag | Adoption Stage |
| Chemical Processing | High | Corrosion Control | Mature |
| Petrochemical | High | Process Expansion | Mature |
| Oil and Gas | High | Asset Replacement | Mature |
| Nuclear Power | Medium | Quality Criticality | Scaling |
| Shipbuilding | Medium | Marine Fabrication | Scaling |
Square Flanges Market Growth Drivers and Impact Analysis
Expansion of Process and Energy Infrastructure
Expansion and modernization of process infrastructure create recurring requirements for mechanical connections across piping networks, vessels, pumps, valves, heat exchangers, and other equipment. New chemical and petrochemical capacity requires flange procurement during construction, while operating facilities generate replacement demand through maintenance and turnaround programs. Oil and gas infrastructure similarly requires connection components across upstream, midstream, and downstream systems. The impact on the market is amplified when projects specify corrosion-resistant or high-performance materials because these requirements increase the importance of qualified suppliers and technical documentation. Regional industrial investment also broadens the addressable supplier base, particularly in Asia Pacific and the Middle East. Consequently, demand is influenced by both capital expenditure and the installed asset base, providing a combination of project-led and recurring maintenance requirements.
Increasing Preference for Corrosion-Resistant and Specialty Materials
Industrial operators increasingly require materials selected according to fluid chemistry, operating temperature, pressure, and expected service life. Stainless steel, duplex, super duplex, nickel alloys, and other specialty materials can address environments where conventional carbon steel is insufficient. This creates opportunities for manufacturers and stockists that can maintain multiple metallurgy options and provide appropriate material certification. The effect extends beyond product selection because specialty materials require closer control of machining, inspection, traceability, and inventory planning. Chemical processing, petrochemical, marine, and selected energy applications are particularly sensitive to corrosion performance. For suppliers, the shift increases the value of technical expertise and inventory depth, while for buyers it can reduce lifecycle risk. The resulting demand favors vendors able to combine standardized products with application-specific engineering support.
Higher Importance of Quality Assurance and Specification Compliance
Industrial buyers increasingly evaluate piping-component suppliers through documented quality systems, inspection procedures, material certificates, dimensional controls, and conformity with recognized standards. This is particularly relevant where square flanges are installed in systems handling hazardous fluids, high pressures, elevated temperatures, or mission-critical processes. Compliance requirements influence supplier qualification and can reduce the addressable pool of vendors for tightly controlled applications. At the same time, consistent documentation supports international trade because exporters must demonstrate conformity to customer specifications and applicable standards. The commercial impact is a gradual shift from simple price competition toward a broader evaluation of quality, availability, customization, and delivery reliability. Suppliers with established inspection capabilities and documented processes can therefore participate more effectively in technically demanding procurement programs.
Square Flanges Market Future Trends
Digital Specification and Traceability in Industrial Procurement
A major Square Flanges Market trends development is the increasing digitization of specification, quotation, documentation, and traceability processes. Industrial buyers are progressively using digital procurement workflows that require standardized product information, material certificates, inspection records, dimensional drawings, and delivery documentation. Suppliers that organize product data around part numbers, standards, material grades, pressure classes, and application requirements can reduce quotation friction and improve order accuracy. Over time, digital product catalogs and structured technical documentation are likely to become more important for export-oriented suppliers and distributors serving geographically dispersed customers. This trend does not fundamentally change the flange itself, but it changes how products are selected, qualified, compared, and ordered. Vendors with reliable digital documentation can shorten procurement cycles and reduce errors associated with manually interpreting technical specifications.
Customization and Application-Specific Engineering
Future demand is likely to move further toward customized configurations where standard products do not fully satisfy equipment geometry, material compatibility, or installation constraints. Industrial projects increasingly combine standardized piping components with specialized equipment, creating requirements for non-standard dimensions, materials, finishes, drilling patterns, and documentation. Manufacturers with machining, inspection, and engineering capabilities can respond to these requirements without depending entirely on high-volume standardized production. The implication for the Square Flanges Market is greater segmentation by application and specification rather than simple volume expansion. Chemical, marine, energy, and specialized industrial projects can generate higher technical requirements even when unit volumes remain comparatively modest. This supports a supplier model based on flexibility, engineering responsiveness, material availability, and quality assurance.
Square Flanges Market Opportunities
Regional Supply Hubs for Export-Oriented Industrial Components
Suppliers in established manufacturing clusters can expand their addressable market by combining local production or sourcing with export-oriented inventory and certification capabilities. India, for example, has a substantial ecosystem of flange, fitting, pipe, and metal suppliers serving energy and process industries, while Southeast Asian distributors support marine and industrial customers. A regional hub strategy can reduce lead times and provide customers with access to multiple material grades and specifications from a single procurement channel. The Square Flanges Market Forecasts indicate that gradual demand expansion creates an opportunity for suppliers to build recurring export relationships rather than relying exclusively on project-specific orders. Commercial investment can focus on inventory depth, quality documentation, machining capability, technical sales, and digital catalogs. These capabilities improve responsiveness while allowing suppliers to address fragmented customer requirements across multiple industrial sectors.
Specialized Supply for High-Performance Industrial Applications
A second opportunity lies in specialized supply for applications requiring enhanced corrosion resistance, demanding pressure conditions, marine durability, or rigorous inspection. Chemical processing, petrochemical, nuclear, and shipbuilding customers often require closer control over metallurgy, dimensional conformity, and documentation than general industrial buyers. Suppliers can address this opportunity through qualified material sourcing, controlled machining, inspection partnerships, traceability systems, and application engineering. Rather than competing only on standardized flange availability, vendors can build value around specification interpretation and project support. This approach is particularly relevant where procurement teams seek a single supplier capable of coordinating multiple materials and associated piping components. The opportunity also supports deeper relationships with engineering contractors, fabricators, equipment manufacturers, and maintenance organizations that influence component selection during project design and execution.
Recent Developments
- August 2026: RFS Hydraulics Sdn Bhd updated its digital customer and compliance infrastructure, including a privacy notice dated August 20, 2026, while continuing to provide online product information covering flanges, valves, fittings, tubes, and hydraulic hardware. Its current platform supports technical enquiries based on part numbers, standards, sizes, and drawings, reinforcing its role as a specification-led industrial distributor.
- September 2025: Fit-Wel Industries LLP was featured in the September 2025 issue of Industrial Products Source with its portfolio of pipe fittings and flanges. The published product information covered multiple flange configurations, international dimensional standards, and pressure classes, highlighting the company's continuing focus on export-oriented industrial piping components and engineered connection products.
- 2025: Metal Tech Engineers continued expanding its industrial flange offering across stainless steel, carbon steel, alloy steel, and copper-nickel products, with multiple pressure classes and flange configurations. Its current portfolio covers applications across energy, manufacturing, construction, and industrial supply, while its sourcing model supports customized metal requirements.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners provided valuable market intelligence that supported our global go-to-market strategy. Their team was professional, responsive, and attentive to our feedback, providing thoughtful analysis and helpful methodological clarifications throughout the project.
Junmo Kim Chief Financial Officer (CFO), Enertech Co., Ltd.
The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for