
Iron & Steel Market Growth, Demand & Size by 2034
Iron & Steel Market Size and Forecasts (2021 - 2034), Global and Regional Share, Trends, and Growth Opportunity Analysis Report Coverage : by Type (Iron and Steel); Production Technology (Basic Oxygen Furnace, Electric Arc Furnace, Open Hearth); End-Use Industry (Building and Construction, Automotive and Transportation, Industrial Machinery, Consumer Goods); and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00040593
- Category : Chemicals and Materials
- No. of Pages : 150
- Available Report Formats :


- Last update date : August 14, 2026


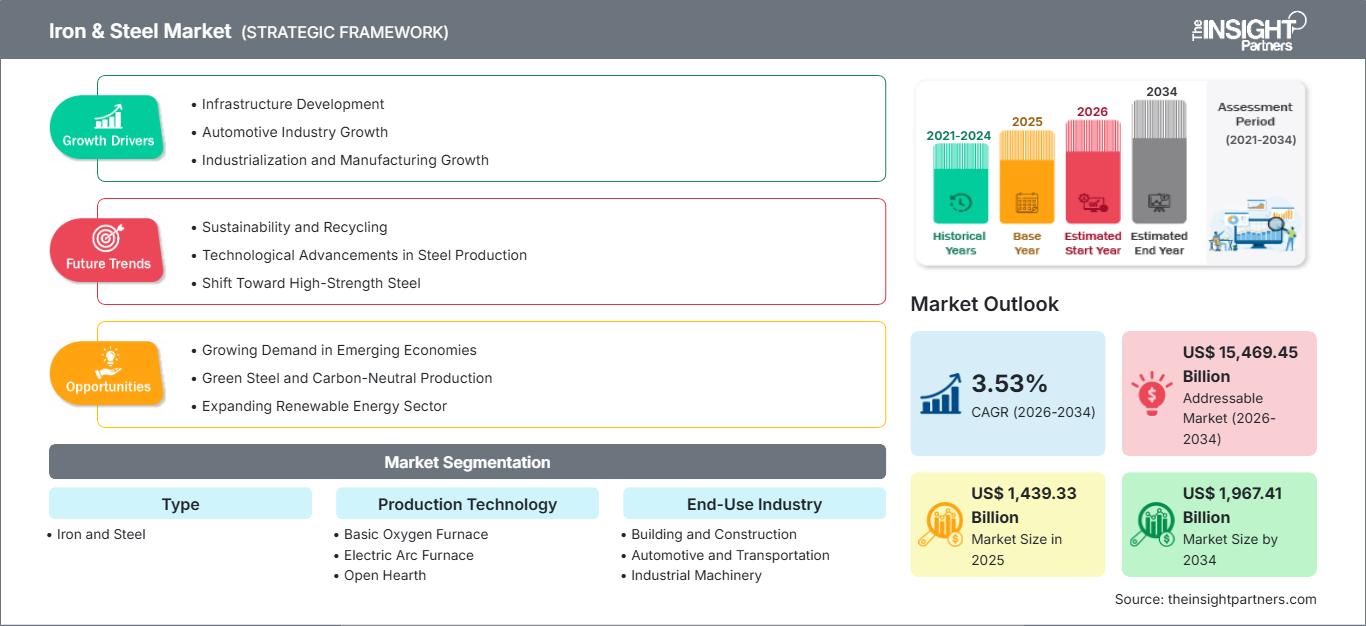
2025 Market Size
US$ 1,439.33 Bn
Base year value
2034 Forecast
US$ 1,967.41 Bn
Projected by 2034
CAGR 2026-2034
3.53 %
Growth rate
Addressable Market
US$ 15,469.45 Bn
(2026-2034)
The iron & steel market was valued at US$ 1,439.33 Billion in 2025 and is projected to reach US$ 1,967.41 Billion by 2034, registering a CAGR of 3.53% during 2026–2034. The market growth is supported by continued demand from construction, automotive, industrial machinery, and consumer goods sectors, along with investments in steel production capacity, infrastructure modernization, and advanced manufacturing technologies across major economies.
The iron & steel market size in North America is influenced by industrial reshoring initiatives, infrastructure renewal programs, and investments in advanced steel grades. The region is expected to witness a CAGR range of 2.8–3.6% during 2026–2034, supported by automotive lightweighting requirements, energy infrastructure development, and modernization of aging transportation networks in the US and Canada.
Iron & Steel Market Assessment and Insights
- North America: The region maintains a mature steel ecosystem supported by automotive, construction, and energy applications. North America accounted for a 16–20% share in 2025 and is expected to grow at a CAGR of 2.8–3.6% between 2026–2034.
- The US: The US benefits from domestic steel production, infrastructure investments, and manufacturing expansion. The US represented a 70–75% share of North America in 2025 and is projected to grow at a CAGR of 2.9–3.7% during 2026–2034.
- Europe: Europe continues to focus on decarbonized steel production and circular manufacturing approaches. Germany, Italy, France, and the UK remain key markets, with Europe contributing a 17–21% share in 2025 and expanding at a CAGR of 2.5–3.3% through 2034.
- Asia Pacific: The region dominates global steel consumption due to large-scale industrialization and infrastructure development in China, India, Japan, and South Korea. Asia Pacific held a 55–60% share in 2025 and is expected to register a CAGR of 3.8–4.6% during 2026–2034.
- Largest Segment: Building and Construction represented the largest end-use industry segment with a 35–40% market share in 2025 and is anticipated to grow at a CAGR of 3.2–4.0% between 2026–2034.
- High Growth Segment: Automotive and Transportation is the high growth segment, accounting for a 18–23% market share in 2025 and projected to expand at a CAGR of 4.0–4.8% during 2026–2034 due to advanced steel adoption.
- Key companies analyzed in detail: ArcelorMittal, Nippon Steel Corporation, POSCO Holdings Inc., Nucor Corporation, HBIS Group Co., Ltd., Ansteel Group Corporation Limited, Tata Steel Limited, JSW Steel Limited, Steel Authority of India Limited, Baowu Steel Group Corporation Limited.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The iron & steel market has evolved through significant transformation in production methods, raw material optimization, and process efficiency improvements. Steelmakers are increasingly adopting electric arc furnace technologies, digital monitoring systems, and low-carbon production pathways to improve operational performance. The transition toward higher-value steel grades for automotive, renewable energy, and infrastructure applications has reshaped production priorities. Basic oxygen furnace technology continues to maintain importance due to large-scale integrated steelmaking capabilities, while electric arc furnaces are gaining traction because of recycling advantages and lower emission potential. These developments are influencing investment decisions across global steel manufacturing hubs.
According to the Iron & Steel Market report, future expansion of the market will be shaped by capacity additions in emerging economies, industrial policy support, and technological investments aimed at reducing carbon intensity. Countries like India, China, and the countries of Southeast Asia will continue to be key players owing to infrastructure development and rising manufacturing. The regulatory environment supporting sustainable manufacturing, efficient recycling, and energy savings is prompting steel manufacturers to adopt eco-friendly solutions. Collaborations among steel manufacturers, technology companies, and energy companies will have an impact on competitiveness up to 2034.
Iron & Steel Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 1,439.33 Billion |
| Market Size by 2034 | US$ 1,967.41 Billion |
| Global CAGR (2026 - 2034) | 3.53% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Iron & Steel Market Analysis
The iron & steel market growth is supported by increasing demand from infrastructure development, transportation manufacturing, industrial equipment production, and urbanization initiatives. Steel still continues to be an important material for use in bridges, buildings, automobiles, machines, and consumer goods due to the strength, recyclability, and cost-effectiveness of the product. The government-led infrastructural development programs, especially in developing countries, still promote the use of steel through investments in railway and road transport networks, renewable energy projects, and industrial plants. The main demand drivers are the construction and automotive industries, which need customized steel types.
The supply chain involves iron ore producers, energy suppliers, steel producers, processors, distributors, and users. Integrated steel producers depend on blast furnaces and basic oxygen furnaces, while electric arc furnace producers depend on scrap as their main input. Supply factors include raw material availability, energy prices, logistics, and environment-related regulations. The increase in importance of resource efficiency has made producers develop better scrap collection mechanisms and more efficient processes.
The competitive landscape of the iron & steel market is characterized by global steel producers focusing on capacity expansion, sustainability initiatives, and product diversification. ArcelorMittal continues to fortify itself with investments in modern solutions for producing steel and decarbonization efforts. Nippon Steel Corporation concentrates on high-quality steel products for industrial use in the automotive industry. POSCO Holdings Inc. develops technologically advanced steel manufacturing, and Nucor Corporation is able to remain competitive with the help of an electric arc furnace-based manufacturing process. In addition to that, there is also HBIS Group Co., Ltd., Ansteel Group Corporation Limited, Tata Steel Limited, JSW Steel Limited, Steel Authority of India Limited, and Baowu Steel Group Corporation Limited that are improving their production capacities and value-added steel offerings.
Investments made by players of the steel market tend to become greener; nowadays, they concentrate more on green steel technologies and renewable energy, as well as the modernization of the production facility. According to the Iron & Steel Market forecast, companies with diversified production assets, strong regional supply networks, and advanced processing capabilities are positioned to capture opportunities arising from infrastructure growth and industrial transformation. Competitive differentiation is expected to depend on sustainability performance, technological innovation, and the ability to supply specialized steel grades for evolving end-use requirements.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Iron & Steel Market: Strategic Insights
Regional Insights
North America Iron & Steel Market
North America accounted for a 16–20% share of the iron & steel market in 2025 and is projected to expand at a CAGR of 2.8–3.6% during 2026–2034. The region benefits from established steel manufacturing infrastructure, domestic scrap availability, and strong demand from construction, automotive, energy, and industrial machinery sectors. The US and Canada remain important contributors due to investments in infrastructure renewal and manufacturing expansion.
Steel producers across North America are focusing on electric arc furnace adoption, advanced steel grades, and lower-emission manufacturing approaches. Government infrastructure programs and increasing demand for sustainable materials are supporting market stability. Investments in renewable energy projects, transportation networks, and industrial facilities are expected to create additional consumption opportunities. The regional supply chain is also adapting through improved recycling systems, localized production strategies, and digital manufacturing solutions.
U.S. Iron & Steel Market
The US represented a 70–75% share of the North American iron & steel market in 2025 and is expected to register a CAGR of 2.9–3.7% during 2026–2034. The country maintains a strong steel production base supported by manufacturers such as Nucor Corporation and other integrated and mini-mill producers. Automotive manufacturing, construction activity, and energy infrastructure remain major demand contributors.
The US steel industry is experiencing increased investment in electric arc furnace facilities, advanced manufacturing technologies, and domestic supply chain resilience. Infrastructure modernization programs are supporting demand for structural steel products, while automotive manufacturers are adopting high-strength steel solutions for vehicle efficiency and safety requirements. The presence of established producers and technology-focused investments continues to strengthen the country’s competitive position within the regional market.
Europe Iron & Steel Market
Europe held a 17–21% of the iron & steel market share in 2025 and is anticipated to grow at a CAGR of 2.5–3.3% between 2026–2034. Germany remains the leading country due to its extensive industrial base, automotive manufacturing ecosystem, and advanced steel processing capabilities. The region is prioritizing low-carbon steel production through hydrogen-based technologies, renewable energy integration, and improved recycling practices.
The UK market is supported by infrastructure projects, energy transition initiatives, and demand from engineering industries. Germany continues to invest in modern steel facilities and sustainable production methods. France, Italy, and Spain are strengthening domestic steel capabilities through efficiency improvements, circular economy programs, and investments in specialized steel products. European producers are increasingly aligning operations with emission reduction objectives, influencing future production strategies and competitive dynamics.
APAC Iron & Steel Market
Asia Pacific dominated the iron & steel market with a 55–60% share in 2025 and is expected to grow at a CAGR of 3.8–4.6% through 2034. China remains the leading country due to its extensive production capacity, while India, Japan, South Korea, and Australia contribute through infrastructure, automotive, and industrial applications.
The region benefits from urbanization, manufacturing expansion, and government-supported infrastructure development. China and India are investing in capacity modernization, while Japan and South Korea focus on advanced steel grades and energy-efficient production. Policy initiatives promoting cleaner technologies and increased domestic manufacturing are expected to support long-term regional growth.
Middle East & Africa Iron & Steel Market
The Middle East & Africa region is expected to expand at a CAGR of 3.0–3.8% during 2026–2034, supported by infrastructure development, industrial diversification, and energy sector investments. Saudi Arabia represents a leading market due to construction activities, industrial expansion programs, and economic diversification initiatives.
The UAE continues to invest in manufacturing and infrastructure projects, while South Africa maintains demand from the mining, construction, and engineering industries. The rest of MEA markets are supported by urban development and transportation investments. The availability of energy resources provides regional producers with opportunities to develop competitive steel manufacturing operations.
Segmentation Analysis
Type
The Type segment includes Iron and Steel and remains fundamental to global industrial development. The segment is projected to grow at a CAGR of 3.3–4.1% during 2026–2034, supported by increasing consumption across infrastructure, manufacturing, transportation, and industrial applications. Steel continues to dominate demand due to its mechanical properties, recyclability, and broad application range, while iron remains essential as a primary input for steel production.
- Iron remains an important raw material category supporting integrated steel production. Demand is influenced by iron ore availability, blast furnace operations, and expanding steelmaking capacity across developing economies.
- Steel represents the dominant material category due to extensive use in construction, automotive manufacturing, machinery, and consumer products. Producers are increasingly developing advanced grades with improved strength and sustainability characteristics.
Production Technology
The Production Technology segment includes Basic Oxygen Furnace, Electric Arc Furnace, and Open Hearth technologies. The segment is expected to grow at a CAGR of 3.1–3.9% during 2026–2034, reflecting ongoing iron & steel market trends focused on production efficiency optimization and the adoption of lower-emission manufacturing methods. Technological selection depends on raw material availability, investment requirements, energy costs, and sustainability targets.
- Basic Oxygen Furnace remains widely used for large-scale integrated steel production. The technology supports high-volume output and continues to serve major steel-producing countries with established industrial infrastructure.
- Electric Arc Furnace is gaining importance due to scrap-based production advantages, operational flexibility, and lower carbon intensity potential. Adoption is increasing among producers investing in sustainable steel manufacturing.
- Open Hearth technology has limited adoption compared with modern processes. Existing facilities are gradually being replaced due to lower efficiency, higher energy consumption, and environmental considerations.
End-Use Industry
The End-Use Industry segment is projected to expand at a CAGR of 3.5–4.3% during 2026–2034. The segment includes Building and Construction, Automotive and Transportation, Industrial Machinery, and Consumer Goods. Increasing infrastructure spending, manufacturing expansion, and demand for durable materials continue to support steel consumption across industries.
- Building and Construction represents the largest application area due to extensive usage in residential, commercial, and infrastructure projects. Steel demand is supported by urbanization, transportation development, and renewable energy infrastructure investments.
- Automotive and Transportation is experiencing increasing adoption of advanced steel grades for vehicle structures, safety components, and lightweighting applications. Manufacturers are seeking stronger materials to improve efficiency while maintaining performance standards.
- Industrial Machinery relies on steel for equipment manufacturing, processing systems, and heavy machinery applications. Demand is supported by industrial automation, manufacturing investments, and the expansion of production facilities.
- Consumer Goods uses steel across appliances, packaging, furniture, and household products. Demand patterns are influenced by consumer spending, manufacturing activity, and material durability requirements.
Opportunity Snapshot
| End-Use Industry | Revenue Contribution (High/Medium/Low) | Trend Tag | Adoption Stage |
| Building and Construction | High | Urban Infrastructure | Mature |
| Automotive and Transportation | High | Lightweight Steel | Scaling |
| Industrial Machinery | Medium | Factory Expansion | Mature |
| Consumer Goods | Medium | Durable Products | Mature |
Iron & Steel Market Growth Drivers and Impact Analysis
Infrastructure modernization and urban development investments
Modernization of infrastructure in developing and developed nations is a major driver that impacts steel consumption patterns. Large investments in transportation systems, bridge development, renewable energy sources, construction of business facilities, and urban residential developments have ensured steady demand for steel products. In countries like India, China, the US, and Saudi Arabia, governments are carrying out infrastructure projects where huge volumes of steel are used. This has boosted the demand for steel that is strong, corrosion-resistant, and fabricated steel. The emergence of smart cities and industrial zones is also prompting steel manufacturers to increase their production capacity.
Increasing adoption of advanced steel grades in automotive applications
The use of sophisticated steels is increasingly being witnessed by automotive manufacturers in order to gain better safety, weight, and manufacturing efficiencies. Steels of high strength, advanced high-strength, and specialized alloys are increasingly being utilized in vehicles as a result of automotive manufacturers' emphasis on fuel efficiency and EVs. The move towards lighter vehicles presents a chance for steel manufacturers to offer their unique types of steels that have superior mechanical properties. Growth in automotive production in the regions of Asia Pacific, Europe, and North America is still providing a boost to the demand for steel products. Collaboration between steel manufacturers and automotive makers is becoming necessary.
Transition toward sustainable steel production technologies
The trends toward environmentally-friendly regulations and decarbonization of the industries are driving more investments into developing technologies that would support sustainable steel production. The steel companies are now considering using electric arc furnaces, integrating renewable energy sources into production, hydrogen-based steelmaking techniques, and recycling innovations to decrease emissions. There are various regulatory measures implemented across Europe, North America, and Asia to encourage companies to update their equipment and use more environmentally friendly production processes. The increased amounts of available scrap steel and enhanced recycling technologies contribute to the development of the circular economy principles. In addition, there is a trend towards implementing digital solutions to increase energy efficiency, raw materials optimization, and lower operating costs.
Iron & Steel Market Future Trends
Expansion of green steel production ecosystems
Steel production systems utilizing green steel production are set to play an increasingly significant role as manufacturers seek to operate their plants with reduced carbon footprints. The development of steel production systems using hydrogen reduction technologies, renewable energy sources, and carbon capture systems will help lower the carbon emissions resulting from traditional steel production processes. The collaboration among steel manufacturers, energy providers, and technology providers is leading to the creation of new approaches to clean steel production. Green steel production systems will impact the procurement practices of industries such as automobiles, construction, and other industries. It is anticipated that governments and industrial firms will provide policy and financial support for green steel production systems.
Digital transformation across steel manufacturing operations
It is anticipated that digital transformation of the steel-making industry would occur in the form of artificial intelligence, automation, predictive maintenance, and process monitoring technologies. Steel companies are adopting digital technologies that would help increase operational efficiencies, cut downtime, and optimize the use of resources. Smart manufacturing technologies would allow for real-time analyses of production variables that would help firms improve quality management and energy savings. Digital technologies are also ensuring safer workplaces and increased consistency of production output. In light of increased competition, steel companies utilizing digital technologies would be better positioned in terms of their operational performance.
Iron & Steel Market Opportunities
Development of specialized steel products for emerging applications
The development of specialized steel products presents significant opportunities for manufacturers seeking higher-value market positions. Demand is increasing for advanced materials used in electric vehicles, renewable energy infrastructure, high-performance machinery, and lightweight transportation systems. Steel producers can capture additional value by expanding portfolios of advanced high-strength steels, electrical steels, and corrosion-resistant grades. Increasing requirements for energy-efficient vehicles and renewable power installations are creating new application areas. Companies investing in research and development, processing capabilities, and customer-specific solutions are positioned to strengthen market competitiveness. Strategic partnerships with automotive manufacturers, engineering companies, and infrastructure developers can further support product innovation and market expansion.
Expansion of steel recycling and circular economy initiatives
Steel recycling and circular economy initiatives offer opportunities to improve resource efficiency and support sustainable production models. Increasing availability of scrap materials, improved collection networks, and regulatory support are encouraging producers to expand recycling-based manufacturing. Electric arc furnace adoption provides opportunities for companies to increase recycled steel utilization while reducing dependence on primary raw materials. Investments in scrap processing technologies, sorting systems, and recycling infrastructure can strengthen supply chain resilience. Steel producers that integrate circular economy strategies can improve environmental performance and respond to growing customer demand for sustainable materials. These initiatives are expected to create new investment opportunities across developed and developing markets.
Recent Developments
- June 2026: ArcelorMittal announced a strategic collaboration with Amazon Web Services (AWS) to accelerate industrial automation across its global operations through advanced cloud, artificial intelligence and edge technologies.
- May 2026: Nippon Steel Corporation (Nippon Steel) and Sanyo Special Steel Co., Ltd. (Sanyo Special Steel), a wholly-owned subsidiary of Nippon Steel, announced that their respective Boards of Directors resolved to conduct a merger (the “Merger”) with Nippon Steel as the surviving company and Sanyo Special Steel as the dissolving company, effective as of April 1, 2027, as follows.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for