
Aramid Fiber Market Size, Growth & Demand by 2034
Coverage: By Product Type (Para-Aramid Fiber and Meta-Aramid Fiber) and End-Use Industry (Safety & Protection Equipment, Aerospace, Automotive, Electronics & Telecommunication, and Others)
- Status : Data Released
- Report Code : TIPRE00006084
- Category : Chemicals and Materials
- No. of Pages : 150
- Available Report Formats :


- Last update date : September 01, 2026


2025 Market Size
US$ 4.52 Bn
Base year value
2034 Forecast
US$ 8.89 Bn
Projected by 2034
CAGR 2026-2034
7.8 %
Growth rate
Addressable Market
US$ 60.34 Bn
(2026-2034)
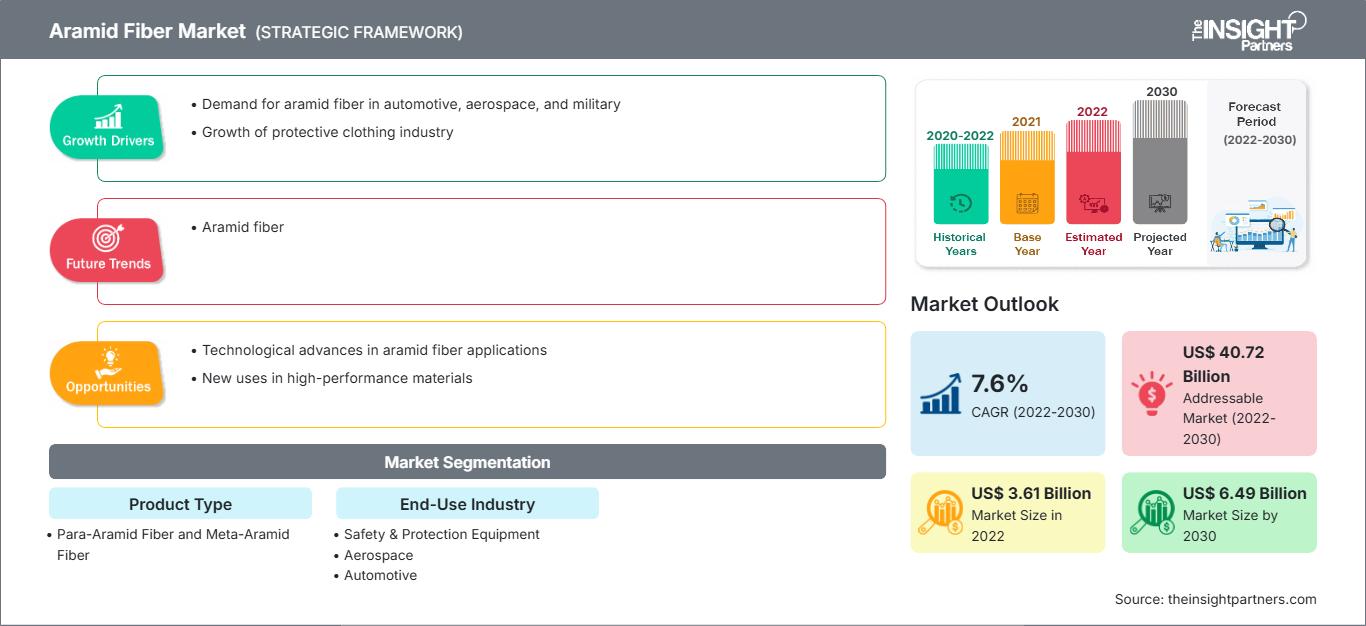
The aramid fiber market is positioned as a high-performance materials segment serving applications where tensile strength, thermal resistance, flame retardancy, low weight, and dimensional stability are critical. The market is valued at US$ 4.52 Billion in 2025 and is projected to reach US$ 8.89 Billion by 2034, expanding at a 7.8% CAGR from 2026 to 2034. Demand is supported by protection equipment, aerospace structures, automotive reinforcement, electrical insulation, and advanced telecommunications.
North America is expected to maintain a strong position through the forecast period, supported by defense modernization, aerospace manufacturing, and demand for lightweight protective systems. The regional aramid fiber market size is also benefiting from domestic advanced-material supply-chain initiatives and qualification requirements that favor established suppliers with certified performance in ballistic, aerospace, and industrial applications.
Aramid Fiber Market Assessment and Insights
- North America: North America is estimated to account for a 28–32% aramid fiber market share in 2025 and expand at a 6.8–7.4% CAGR between 2026–2034, supported by defense procurement, aerospace production, protective equipment, and advanced composite applications.
- US: The US represents approximately 24–28% of the North American market in 2025 and is expected to grow at a 6.9–7.5% CAGR between 2026–2034, led by defense, aerospace, and personal protection applications.
- Europe: Europe is estimated to hold a 24–28% share in 2025 and grow at a 6.4–7.1% CAGR between 2026–2034, with Germany, France, the Netherlands, Italy, and the UK supporting demand through aerospace, automotive, industrial safety, and electrical applications.
- Asia Pacific: Asia Pacific is estimated to command a 37–41% share in 2025 and register a 8.0–8.7% CAGR between 2026–2034, with China, Japan, South Korea, and India benefiting from manufacturing expansion, telecommunications infrastructure, automotive production, and localized fiber capacity.
- Largest Segment: Para-Aramid Fiber is estimated at a 68–72% market share in 2025, expanding at a 7.5–8.1% CAGR from 2026–2034, supported by ballistic protection, reinforcement, optical cables, and high-strength applications.
- High Growth Segment: Electronics & Telecommunication is estimated at a 12–16% share in 2025, growing at a 8.4–9.2% CAGR from 2026–2034, driven by optical-fiber reinforcement and high-performance insulation.
- Key companies analyzed in detail: DuPont de Nemours, Inc.; Teijin Limited; Yantai Tayho Advanced Materials Co., Ltd.; Hyosung Corporation; Toray Industries, Inc.; Kolon Industries, Inc.; Huvis Corporation; China National Bluestar (Group) Co., Ltd.; Taekwang Industrial Co., Ltd.; Kermel S.A.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
This aramid fiber market has progressed from being a protective materials market towards becoming an advanced materials platform. Para-aramid is still key in ballistic protection, optical fibers, tires, ropes, and composites, whereas meta-aramid continues to be more widely used in thermal and electrical protection applications. The dynamics of Asian capacity expansion have affected economics such that producers must focus on producing specialty grades, customized processes for specific applications, value-added conversion, and performance differentiation rather than merely volumes.
For the future, procurement in the aramid fiber market is expected to become increasingly supply-resilient and certification, sustainability, and application-driven. Growth prospects can be found in India and Southeast Asia besides the already existing growth markets in China, Japan, South Korea, Europe, and North America. Production capabilities, circular feedstock, lightweight protection solutions, and electrical infrastructure should drive demand; military and aerospace applications are relatively resilient high performance uses.
Aramid Fiber Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 4.52 Billion |
| Market Size by 2034 | US$ 8.89 Billion |
| Global CAGR (2026 - 2034) | 7.8% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Aramid Fiber Market Analysis
Demand across the aramid fiber market is shaped by the combination of safety requirements, weight reduction, heat resistance, and mechanical performance. The value chain begins with aromatic diamines and diacid chlorides, followed by polymerization, spinning, drawing, finishing, and conversion into yarn, staple fiber, pulp, paper, fabrics, and composites. Market growth therefore depends not only on fiber production but also on converter qualification and downstream application development.
According to the aramid fiber market report, dynamics of supply are becoming more affected by the increase in capacities in Asia. The 2026 strategy of Teijin reveals an overproduction in the para-aramid category, but emphasizes demand in the segments of defense and infrastructure applications. Kolon has expanded its capacity of aramids, whereas Toray Advanced Materials Korea has completed a capacity expansion of 3,000 tons of meta-aramid in 2026. It seems like the trend toward the development of specialty grades and regional supplies is gaining momentum.
There are a number of technology owners and new expanding Asian players in the competitive aramid fiber market. DuPont's Kevlar and Nomex business was sold in April 2026 after the sale of the company for approximately US$1.8 billion to Arclin. The strategy of reorganization within the aramid products of Teijin is geared towards high-value added applications, whereas Kolon, Yantai Tayho, Hyosung, and Toray are building up their capacities and capabilities in various applications. In this way, competition becomes more focused on qualifications of products and grades.
Development of application specific capability and not just capacity becomes the focus of investments. The latest expansion of capacity of meta-aramids in Toray Advanced Materials Korea is aimed at the segments of electrical insulation, industrial safety, and advanced mobility applications. Teijin will be investing in applications of ballistic protection and submarine power cables, whereas other companies in Asia continue to develop specialty para-aramid and meta-aramid grades.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Aramid Fiber Market: Strategic Insights
Regional Insights
North America aramid fiber market
North America is estimated to hold a 28–32% share in 2025 and expand at a 6.8–7.4% CAGR through 2034. Advantages include the existence of an aerospace manufacturing base, defense procurement, law enforcement protection needs, and industrial safety standards. The US market forms the main regional market, whereas Canada participates with its aerospace, industrial, and protective applications.
In the regional environment, emphasis is placed on materials of proven quality with reliable ballistic, thermal, and mechanical performance. There is growing demand for lightweight composite materials, optical comms technology, and specialized industrial textiles. The domestic resilience of the supply chain has been growing particularly important for critical defense materials, thus stimulating investment in US manufacturing and converting capacity.
U.S. aramid fiber Market
The US represents approximately 24–28% of North America in 2025 and is projected to grow at a 6.9–7.5% CAGR through 2034. Defense modernization, aerospace programs, law-enforcement equipment, and industrial safety remain major demand pillars. DuPont historically held a major position through Kevlar and Nomex, although the businesses moved to Arclin in 2026.
According to the aramid fiber market forecast, system weight reduction while preserving the effectiveness of protection is becoming more common during the development of applications. The use of Kevlar EXO in advanced armor and aerospace development shows this trend of developing high-performance fiber solutions. Meanwhile, domestic investments will be spreading from ballistics to manufacturing, although there will still be a preference for suppliers with proven qualifications and reliability.
Europe aramid fiber Market
Europe is estimated to account for 24–28% of global demand in 2025 and grow at a 6.4–7.1% CAGR, with Germany serving as a major industrial market. United Kingdom, France, Italy, Spain, and the Netherlands are represented by the use of aramids in aerospace, automotive, protective clothing, electrical insulation, and industrial markets. The European market becomes increasingly driven by sustainability and product-performance needs.
Demand from the UK and France comes from the aerospace, defense, and protective equipment industries, and Germany represents its demand from the automotive and industrial sectors. Demand from Italy and Spain is generated through automotive, industrial, and protective equipment applications. The Netherlands becomes crucial for production of aramid materials and technical expertise. European clients are becoming increasingly concerned with sustainability and product performance.
APAC aramid fiber Market
APAC is estimated to represent 37–41% of 2025 demand and grow at an 8.0–8.7% CAGR, making it the leading and fastest-expanding regional market. China, Japan, South Korea, and India are central to regional consumption and production, supported by automotive, telecommunications, industrial safety, electronics, and defense applications.
Chinese manufacturing is very substantial in nature, while Japan and South Korea have maintained their technical expertise. India is increasingly becoming an important destination for production and consumption, owing to industrialization and defense fiber manufacturing. On the other hand, Australia mainly contributes through mining, industrial safety and infrastructure applications. Local manufacturers within the region are also developing local capacities to cut down on imports.
Middle East & Africa aramid fiber Market
Middle East and Africa is expected to expand at a 6.2–6.9% CAGR, with Saudi Arabia and the UAE leading regional demand. Thermal protection materials are required for oil and gas exploration, while construction, military procurement, and industry safety offer further possibilities. South Africa is still an industrial country.
The industrial diversification of Saudi Arabia and infrastructure projects of the UAE enable the application of specialty materials. South Africa contributes to this through mining, manufacturing, and protective equipment. The remaining MEA region has less potential, but where the operational environment is tough, technical fibers have more value.
Segmentation Analysis
Product Type
Product Type remains the fundamental technology segmentation, with para-aramid representing the larger demand pool and meta-aramid serving applications requiring thermal stability and flame resistance. The combined segment is expected to grow at a 7.6–8.0% CAGR from 2026–2034. Product selection depends strongly on tensile performance, thermal behavior, electrical insulation, processing requirements, and certification.
- Para-Aramid Fiber: Para-aramid commands the larger market position because of its exceptional tensile strength and low weight. Demand is concentrated in ballistic protection, optical-fiber reinforcement, tires, ropes, aerospace composites, and high-performance industrial applications.
- Meta-Aramid Fiber: Meta-aramid serves applications where flame resistance, thermal stability, and electrical insulation are critical. Protective clothing, electrical equipment, filtration, aerospace interiors, and industrial safety systems represent important demand centers.
End-Use Industry
End-Use Industry is expected to expand at a 7.8–8.3% CAGR from 2026–2034, reflecting increasing penetration into protection, aerospace, automotive, and electronic systems. Qualification requirements, lightweighting targets, thermal management, and reliability considerations influence material selection. Applications with high failure costs generally provide stronger pricing resilience than conventional textile uses.
- Safety & Protection Equipment: Protective equipment remains a core application because aramid combines low weight with high tensile strength, cut resistance, and thermal performance. Demand spans ballistic protection, firefighting garments, industrial clothing, helmets, gloves, and first-responder equipment.
- Aerospace: Aerospace applications use aramid in lightweight composites, interior components, insulation, structural reinforcement, and protective systems. Qualification requirements and long service cycles create high barriers to supplier substitution while encouraging continued investment in certified material grades.
- Automotive: Automotive demand includes tire reinforcement, friction materials, hoses, belts, battery protection, and lightweight components. EV development creates additional opportunities because manufacturers seek materials that combine low mass, mechanical stability, electrical insulation, and thermal resistance.
- Electronics & Telecommunication: Electronics and telecommunication applications increasingly use aramid for optical-fiber reinforcement, cables, electrical insulation, and protective components. Data-center expansion, fiber-network deployment, and higher equipment reliability requirements support continued adoption of high-strength, dimensionally stable fibers.
Opportunity Snapshot
| End-Use Industry | Revenue Contribution (High/Medium/Low) | Trend Tag | Adoption Stage |
|---|---|---|---|
| Safety & Protection Equipment | High | Ballistic Protection | Mature |
| Aerospace | High | Lightweight Composites | Mature |
| Automotive | Medium | EV Reinforcement | Scaling |
| Electronics & Telecommunication | Medium | Fiber Reinforcement | Scaling |
Aramid Fiber Market Growth Drivers and Impact Analysis
Defense modernization and lightweight protective systems
Defense modernization is increasing demand for materials that improve protection without adding excessive equipment weight. Aramids offer a combination of mechanical properties such as tensile strength, impact resistance, thermal stability, and low density; therefore, they can be used for helmets, body armor, vehicles, rope, and protective materials. In procurement projects, considerations about the mobility of soldiers and weights of the systems make it possible to design higher performing fiber variants and new textile architectures. Commercial value is added to the material since it qualifies to be used in military procurement programs and can then find its way into law enforcement, fire protection, and transportation industries. The supplier with existing testing capability and long qualification experience can then capitalize on this opportunity.
Expansion of optical communications and electrical infrastructure
The expansion of high-speed telecommunications and electrical infrastructure is broadening the addressable application base for aramid fiber. Optical cables use high-strength aramid yarns to provide mechanical reinforcement while maintaining flexibility and protecting delicate fiber elements. The growth of data centers, broadband connectivity, submarine communications, and power transmission leads to an increase in the need for reinforcement materials which will provide reliable performance. In addition, there is also demand coming from the electrical insulation needs of the transformer industry, cabling, and others. It is especially notable in Asia-Pacific, as there are extensive electronics manufacturing and infrastructure deployment industries in this region. This gives manufacturers of meta-aramid an opportunity to have a source of industrial demand, which will not be based on defense procurement cycles.
Automotive lightweighting and electrification
Automotive manufacturers are increasingly balancing lightweighting, safety, durability, and thermal management as vehicle architectures evolve. Aramid fiber can reinforce tires, hoses, belts, friction materials, battery enclosures, and selected composite components while contributing high strength at relatively low weight. Electrification adds opportunities where electrical insulation and thermal resistance are required around high-voltage systems. Demand is also supported by stricter durability requirements and the need to improve vehicle efficiency without compromising structural performance. Asia Pacific is particularly important because of its large automotive manufacturing base and rapidly expanding EV ecosystem. Suppliers that can provide application-specific fiber formats, pulp, fabrics, and composite-compatible products can capture more value than producers focused solely on filament supply. Partnerships with Tier 1 component manufacturers can further accelerate qualification and commercial adoption.
Aramid Fiber Market Future Trends
Circular and bio-based aramid platforms
The aramid fiber market trends show that sustainability is moving from corporate reporting toward product-level material selection. Future aramid platforms are likely to incorporate recycled fiber, recovered production waste, and bio-based feedstocks while preserving established mechanical and thermal specifications. Teijin Aramid's Twaron Next demonstrates this direction by combining para-aramid performance with circular and bio-based pathways. Such products can support customers facing carbon-footprint requirements without forcing major process changes. Adoption will depend on traceability, independent verification, stable feedstock availability, and consistent fiber quality. Producers are therefore likely to develop mass-balance systems, closed-loop recovery, and product-level environmental declarations. As customers increasingly evaluate lifecycle performance alongside purchase price, sustainable variants could shift from niche offerings toward standard specifications in automotive, industrial, aerospace, and protective applications.
Application-specific high-performance fiber architectures
Future product development is expected to emphasize customized fiber characteristics rather than uniform performance specifications. Manufacturers can differentiate through tenacity, modulus, thermal behavior, surface treatment, filament geometry, staple length, and compatibility with downstream processing. This trend is particularly relevant to advanced protective equipment, aerospace composites, EV components, and electrical insulation. Fiber suppliers are increasingly collaborating with converters and OEMs to optimize material architecture at the system level. Such cooperation can shorten development cycles and improve qualification success. The resulting products may combine aramid with other reinforcement materials, coatings, resins, or engineered textile structures. Over time, application-specific solutions should improve supplier differentiation and reduce direct price competition, particularly in technically demanding markets where switching suppliers requires extensive testing and certification.
Aramid Fiber Market Opportunities
Localized production in emerging Asian markets
India and Southeast Asia present opportunities for localized production and downstream conversion as automotive, telecommunications, defense, and industrial manufacturing capacity expands. Establishing regional spinning, textile conversion, and technical-service capabilities can reduce logistics exposure and improve customer responsiveness. India is particularly attractive because defense localization and manufacturing expansion can increase demand for high-performance protective materials, while telecommunications infrastructure supports optical-fiber reinforcement. Southeast Asian automotive and electronics ecosystems provide complementary opportunities for reinforcement and insulation products. Investors can also target partnerships with local converters rather than developing fully integrated operations immediately. Such strategies can reduce market-entry risk while generating customer qualification data. Over time, local technical centers could support customization, application testing, and product development, strengthening supplier relationships and creating a pathway toward higher-value specialty grades.
Integrated aramid solutions for defense and aerospace
A second opportunity lies in moving beyond fiber sales toward integrated materials and engineered components. Defense and aerospace customers increasingly value predictable system performance, lower weight, certification support, and simplified procurement. Suppliers can respond by developing preforms, fabrics, tapes, coated textiles, composites, and application-specific reinforcement systems around core aramid technologies. This approach can increase the value captured per kilogram while creating stronger technical relationships with OEMs and Tier 1 manufacturers. Strategic partnerships with weaving companies, composite specialists, armor manufacturers, and aerospace suppliers can accelerate commercialization. Product development should prioritize measurable improvements in strength-to-weight ratio, durability, thermal resistance, and manufacturability. Suppliers that successfully combine material science with downstream engineering can build higher entry barriers and reduce exposure to price competition in standard fiber grades.
Recent Developments
- June 16, 2026: Toray Advanced Materials Korea completed the expansion of its Meta-Aramid Fiber Unit 2 at the Gumi Plant 1, adding 3,000 tons of annual capacity and bringing total site capacity to 5,400 tons. The company highlighted demand from power infrastructure, mobility, defense, industrial safety, and data-center-related electrical equipment.
- April 1, 2026: Arclin completed its approximately US$1.8 billion acquisition of DuPont's Aramids business, including the Kevlar and Nomex brands. The transaction added established aramid manufacturing operations and approximately 1,800 employees to Arclin, expanding its presence across aerospace, electrical infrastructure, electric vehicles, personal protection, and defense applications.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for