
Oil and Gas Wireless Sensor Networks Market Size, Demand & Growth by 2034
Coverage: by Application (Upstream, Midstream, Downstream); Technology (Bluetooth, ZigBee, Cellular Based LPWA, Others), and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00013154
- Category : Electronics and Semiconductor
- No. of Pages : 150
- Available Report Formats :


- Last update date : October 13, 2026


2025 Market Size
US$ 6.32 Bn
Base year value
2034 Forecast
US$ 13.12 Bn
Projected by 2034
CAGR 2026-2034
8.45 %
Growth rate
Addressable Market
US$ 87.21 Bn
(2026-2034)
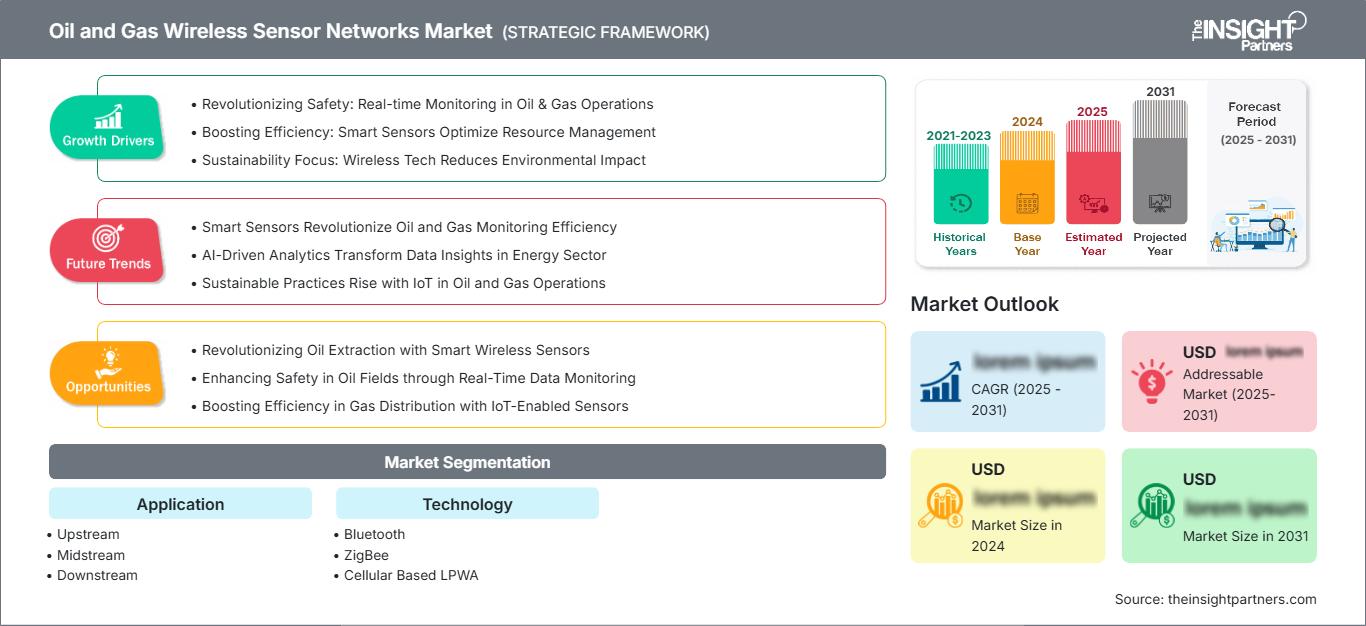
The Oil and gas wireless sensor networks market was valued at US$ 6.32 Billion in 2025 and is projected to reach US$ 13.12 Billion by 2034, registering a CAGR of 8.45% during 2026–2034. The market is benefiting from the increasing deployment of industrial digitalization technologies across upstream, midstream, and downstream operations. Wireless sensing platforms improve real-time asset monitoring, operational visibility, worker safety, and predictive maintenance while reducing installation complexity across geographically dispersed oil and gas facilities.
Across North America, expanding investments in intelligent oilfield infrastructure and modernization of aging pipeline networks continue to strengthen oil and gas wireless sensor networks market size. The regional market is expected to expand at a CAGR of 7.8–8.4% through 2034, supported by industrial IoT adoption, stricter pipeline integrity regulations, and increasing deployment of wireless monitoring solutions for remote production sites, compressor stations, and storage terminals.
Oil and Gas Wireless Sensor Networks Market Assessment and Insights
- North America: The region accounted for 34–38% share in 2025 and is anticipated to grow at a CAGR of 7.8–8.4% during 2026–2034. Strong digital oilfield investments, mature energy infrastructure, and increasing pipeline integrity monitoring continue supporting regional expansion.
- US: The country represented 74–78% of the North American market in 2025 and is projected to register a CAGR of 7.9–8.5% during 2026–2034, driven by shale production activities, refinery modernization, and industrial automation investments.
- Europe: Europe captured 24–28% share in 2025 and is forecast to expand at a CAGR of 7.4–8.0% during 2026–2034. Norway, the UK, Germany, and the Netherlands continue leading digital monitoring deployments across offshore and downstream facilities.
- Asia Pacific: Asia Pacific accounted for 26–30% share in 2025 and is expected to record the fastest regional expansion with a CAGR of 9.2–9.8% during 2026–2034. China, India, Australia, Japan, and South Korea continue investing in refinery modernization and industrial wireless communication technologies.
- Largest Segment: Application – Upstream held a 42–46% market share in 2025 and is projected to grow at a CAGR of 8.3–8.9% during 2026–2034, supported by increasing deployment of remote asset monitoring and predictive maintenance systems.
- High Growth Segment: Technology – Cellular Based LPWA represented 24–28% market share in 2025 and is anticipated to register a CAGR of 10.2–10.8% during 2026–2034, driven by long-range connectivity requirements and expanding industrial IoT deployments.
- Key companies analyzed in detail: Analog Devices, Inc.; ABB Ltd.; Baker Hughes Company; Cisco Systems, Inc.; Emerson Electric Co.; Honeywell International Inc.; Halliburton Company; Huawei Technologies Co., Ltd.; Mettler-Toledo International Inc.; Omega Engineering, Inc.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The increasing needs for wireless connectivity in industries have brought about drastic changes in the oil and gas wireless sensor networks market in the past decade. There has been increased use of wireless sensing solutions to help measure pressure, vibration, temperature, corrosion, emissions, and the health of the equipment without using wires. Advances in low power communication standards, edge computing, battery efficiency, and industrial cybersecurity have enabled operators to increase the deployment of their wireless sensor networks in offshore platforms, pipelines, LNG plants, and refineries. These initiatives will help to boost the production process efficiency while decreasing the maintenance costs and the shutdowns that are unplanned.
There is an expectation that in the future, there will be more investments made in hydrocarbon-producing economies that are new, modernization of the existing energy infrastructure and initiatives by the government to digitize the industry. There will be the increased use of cloud-based asset management solutions, AI-powered predictive maintenance, and industrial private wireless networks that will aid in the long term deployment prospects.
Oil and Gas Wireless Sensor Networks Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 6.32 Billion |
| Market Size by 2034 | US$ 13.12 Billion |
| Global CAGR (2026 - 2034) | 8.45% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Oil and Gas Wireless Sensor Networks Market Analysis
The market growth is now heavily driven by the increasing shift towards smart operations and digital asset management in the oil and gas sector. Oil and gas companies are now focused on constant monitoring of their machinery in order to increase their efficiency, save on maintenance costs, and comply with environmental regulations. Deployment of wireless sensors makes installation in risky and difficult-to-reach environments easy while reducing downtime. As more and more old facilities undergo upgrades, the need for reliable and scalable wireless infrastructures that can provide predictive maintenance, condition monitoring, and process optimization in production networks is increasing.
An additional driver is the shift within the industrial value chain. Increasingly, the cooperation of sensor producers, semiconductor suppliers, communications technologies providers, cloud platform providers, and oilfield services companies leads to the creation of monitoring solutions. Improvements in batteries, energy harvesting, industrial gateways, and edge computing extend the life of the systems and lower their cost.
Competition in the oil and gas wireless sensor networks market report shows growing importance of innovations in products, cybersecurity, industry interoperability, and partnerships. Major players such as Analog Devices, Inc., ABB Ltd., Baker Hughes Company, Cisco Systems, Inc., Emerson Electric Co., Honeywell International Inc., Halliburton Company, Huawei Technologies Co., Ltd., Mettler-Toledo International Inc., and Omega Engineering, Inc. are still growing their ranges of wireless sensors for use in harsh industrial environments.
Capital expenditure in the market is directed at investments in industry IoT platforms, artificial intelligence integration, diagnostics through cloud services, and industrial private wireless communications. Companies are also enhancing their software along with hardware to offer full monitoring solutions. Further mergers and acquisitions, cooperation on technologies, and development of digital services are improving competitiveness and making it possible to meet changing needs of operations in energy facilities.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Oil and Gas Wireless Sensor Networks Market: Strategic Insights
Regional Insights
North America Oil and gas wireless sensor networks Market
North America accounted for 34–38% of the oil and gas wireless sensor networks market share in 2025 and is projected to expand at a CAGR of 7.8–8.4% during 2026–2034. The region benefits from extensive upstream production activities, mature pipeline infrastructure, and high investment in industrial automation. Energy operators continue replacing legacy monitoring systems with wireless sensor networks that enable real-time asset visibility, predictive maintenance, and improved operational safety across geographically dispersed facilities.
The United States and Canada remain the primary contributors to regional demand owing to continued shale development, offshore production, and refinery modernization. Pipeline operators increasingly deploy wireless sensing solutions for leak detection, corrosion monitoring, and equipment diagnostics to improve regulatory compliance and reduce maintenance costs. Growing implementation of industrial Internet of Things platforms and private wireless communication infrastructure further supports regional market expansion.
U.S. Oil and gas wireless sensor networks Market
The U.S. represented 74–78% of the North American market in 2025 and is anticipated to register a CAGR of 7.9–8.5% during 2026–2034. Large-scale shale production, expanding LNG infrastructure, and modernization of refinery assets continue generating sustained demand for wireless monitoring technologies. Major industrial automation providers and energy technology companies maintain strong domestic operations, encouraging continuous innovation and deployment of advanced sensing platforms.
Increasing investments in digital oilfield initiatives have accelerated adoption across upstream drilling operations, midstream transportation assets, and downstream refining facilities. Operators increasingly integrate wireless sensing with cloud analytics, edge computing, and predictive maintenance platforms to improve production efficiency and minimize unplanned downtime. Continued emphasis on worker safety and environmental monitoring further strengthens long-term deployment opportunities throughout the country.
Europe Oil and gas wireless sensor networks Market
Europe held 24–28% market share in 2025 and is expected to grow at a CAGR of 7.4–8.0% during 2026–2034. Norway remains the leading regional market due to extensive offshore production and high adoption of digital asset management solutions. The United Kingdom continues investing in offshore infrastructure modernization while supporting industrial decarbonization through intelligent operational technologies.
Germany emphasizes refinery modernization, process automation, and industrial digitalization, creating favorable conditions for wireless sensor deployment across downstream facilities. France, Italy, and Spain continue strengthening industrial monitoring capabilities through investments in energy infrastructure upgrades, environmental compliance technologies, and advanced industrial communication systems. The combination of operational efficiency objectives and increasingly stringent safety requirements continues supporting regional demand.
APAC Oil and gas wireless sensor networks Market
Asia Pacific accounted for 26–30% of the global market in 2025 and is forecast to register the highest regional CAGR of 9.2–9.8% during 2026–2034. China leads regional deployment through refinery expansion, pipeline construction, and industrial automation investments, while India continues accelerating digital transformation across its petroleum sector.
Japan and South Korea emphasize advanced industrial monitoring for refining operations, whereas Australia supports adoption across LNG facilities and remote upstream assets. Government-backed industrial modernization initiatives and expanding energy infrastructure projects continue creating strong opportunities for wireless sensing technologies throughout the region.
Middle East & Africa Oil and gas wireless sensor networks Market
The Middle East & Africa market is projected to expand at a CAGR of 8.8–9.4% during 2026–2034, supported by large hydrocarbon reserves, increasing digital oilfield investments, and modernization of production infrastructure. Saudi Arabia remains the leading regional market, while the United Arab Emirates continues expanding industrial automation across upstream and downstream operations.
South Africa focuses primarily on refinery modernization and industrial monitoring applications, whereas the Rest of MEA continues investing in pipeline expansion, storage facilities, and intelligent production systems. Growing emphasis on operational efficiency, predictive maintenance, and environmental monitoring is expected to strengthen regional adoption of wireless sensor network technologies over the forecast period.
Segmentation Analysis
Application
The Application segment accounted for the largest contribution to the market, with the Upstream category remaining the primary revenue generator. The segment is projected to grow at a CAGR of 8.3–8.9% during 2026–2034. Expanding deployment of digital monitoring platforms across exploration, production, transportation, and refining activities continues improving operational efficiency, safety, and predictive maintenance capabilities. The oil and gas wireless sensor networks market scope continues expanding as operators prioritize wireless connectivity across increasingly complex industrial environments.
- Upstream: Dominates market demand owing to extensive use of wireless sensors for wellhead monitoring, drilling optimization, equipment diagnostics, reservoir surveillance, and predictive maintenance across remote production environments.
- Midstream: Increasing deployment supports pipeline integrity management, leak detection, pressure monitoring, compressor station optimization, and storage facility surveillance while reducing inspection costs across extensive transportation networks.
- Downstream: Wireless monitoring solutions improve refinery automation, process optimization, emissions monitoring, equipment reliability, and operational safety while enabling continuous data collection from critical production assets.
Technology
The Technology segment is expected to expand at a CAGR of 9.0–9.6% during 2026–2034, driven by improvements in industrial communication reliability, power efficiency, cybersecurity, and long-range connectivity. Technology selection increasingly depends on operational environments, communication distance, battery life requirements, and compatibility with industrial automation platforms across oil and gas operations.
- Bluetooth: Primarily adopted for short-range equipment diagnostics, portable maintenance devices, and localized industrial monitoring applications requiring secure, energy-efficient wireless communication within production facilities.
- ZigBee: Widely implemented for low-power industrial sensor networks where mesh communication enhances coverage, reliability, and continuous monitoring across complex processing plants and storage facilities.
- Cellular Based LPWA: Supports long-distance connectivity, remote pipeline monitoring, distributed production assets, and industrial IoT deployments requiring extensive geographic coverage, high scalability, and efficient power consumption.
Opportunity Snapshot
| Application | Revenue Contribution | Trend Tag | Adoption Stage |
|---|---|---|---|
| Upstream | High | Digital Wells | Mature |
| Midstream | Medium | Pipeline Safety | Scaling |
| Downstream | High | Smart Refining | Scaling |
Oil and Gas Wireless Sensor Networks Market Growth Drivers and Impact Analysis
Expansion of Industrial IoT Across Energy Infrastructure
The growing adoption of Industrial Internet of Things (IIoT) technologies is transforming monitoring and control practices across oil and gas operations. Operators are increasingly deploying wireless sensor networks to capture continuous operational data from wells, pipelines, storage tanks, compressors, and processing facilities. These systems improve asset visibility while enabling predictive maintenance, reducing equipment failures, and minimizing costly production interruptions. Integration with cloud computing, artificial intelligence, and edge analytics supports faster operational decision-making and optimized resource utilization. As digital transformation becomes a strategic priority for energy companies, investments in intelligent sensing technologies are expected to accelerate, creating sustained demand for scalable wireless monitoring solutions throughout upstream, midstream, and downstream environments.
Increasing Focus on Pipeline Safety and Asset Integrity Management
Pipeline operators are strengthening investments in continuous monitoring technologies to improve operational safety, environmental compliance, and infrastructure reliability. Wireless sensor networks provide real-time information on pressure fluctuations, corrosion levels, temperature variations, structural stress, and leak detection across extensive transportation networks. Compared with conventional wired systems, wireless deployments simplify installation in remote locations while reducing maintenance requirements and infrastructure costs. Regulatory attention toward emission reduction, accident prevention, and operational transparency continues encouraging broader adoption of intelligent monitoring systems. The ability to detect abnormalities before failures occur significantly improves maintenance planning and reduces operational risk for energy companies managing critical infrastructure assets.
Growing Automation of Upstream and Downstream Facilities
Automation initiatives across exploration, production, refining, and storage facilities continue driving demand for advanced sensing technologies. Oil and gas companies increasingly integrate wireless sensor networks with distributed control systems, supervisory control platforms, and predictive maintenance software to optimize production efficiency. Automated monitoring reduces manual inspection frequency while providing continuous operational intelligence from equipment operating in hazardous environments. Modern wireless communication technologies also improve scalability, allowing operators to expand monitoring coverage without major infrastructure modifications. These operational advantages encourage long-term investment in intelligent sensing platforms as companies pursue safer, more efficient, and data-driven production strategies across the energy value chain.
Oil and Gas Wireless Sensor Networks Market Future Trends
Artificial Intelligence Enhancing Wireless Asset Monitoring
Artificial intelligence is becoming an essential component of industrial monitoring systems by improving the interpretation of large volumes of sensor-generated data. AI-powered analytics enable early fault detection, predictive maintenance scheduling, and operational optimization across drilling sites, pipelines, and refining facilities. Future deployments are expected to combine machine learning with edge computing, allowing faster local decision-making while reducing communication latency. This oil and gas wireless sensor networks market trends evolution will improve equipment reliability, reduce operational costs, strengthen safety performance, and support increasingly autonomous energy production environments through intelligent wireless monitoring ecosystems.
Private Industrial Wireless Networks Supporting Digital Oilfields
Private wireless communication infrastructure is expected to become increasingly important as energy companies expand connected operations across geographically dispersed assets. Dedicated industrial networks provide secure, reliable, and low-latency connectivity for thousands of wireless sensors operating simultaneously in demanding environments. Future deployments will integrate advanced communication technologies with cloud platforms, digital twins, robotics, and autonomous inspection systems. Growing investment in resilient industrial communication architecture will enhance operational continuity, improve cybersecurity, and support long-term digital transformation strategies across the global oil and gas industry.
Oil and Gas Wireless Sensor Networks Market Opportunities
Expanding Digital Energy Investments Across Emerging Economies
Emerging oil-producing countries continue investing in refinery modernization, pipeline construction, offshore production, and intelligent industrial infrastructure. These projects create substantial opportunities for wireless sensing providers capable of delivering scalable monitoring platforms adapted to harsh operating environments. The increasing availability of industrial cloud platforms, affordable wireless communication technologies, and advanced analytics enables operators to modernize new and existing facilities simultaneously. Oil and gas wireless sensor networks market Forecasts indicate that vendors establishing regional partnerships, localized engineering support, and integrated digital service capabilities will be well positioned to benefit from expanding infrastructure investments across Asia Pacific, the Middle East, Africa, and selected Latin American markets.
Integrated Monitoring Platforms Creating Long-Term Service Revenue
Equipment manufacturers and automation providers have an opportunity to expand beyond hardware sales by delivering comprehensive lifecycle monitoring services. Integrated platforms combining wireless sensors, cloud analytics, cybersecurity, predictive maintenance, and digital asset management provide recurring revenue opportunities while strengthening customer relationships. Companies capable of offering interoperable solutions compatible with existing industrial automation systems can differentiate themselves within an increasingly competitive marketplace. Continued investment in software development, remote diagnostics, and industrial artificial intelligence will enable vendors to support long-term operational optimization while improving reliability and sustainability across energy infrastructure.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners provided valuable market intelligence that supported our global go-to-market strategy. Their team was professional, responsive, and attentive to our feedback, providing thoughtful analysis and helpful methodological clarifications throughout the project.
Junmo Kim Chief Financial Officer (CFO), Enertech Co., Ltd.
The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for