
Utility Drones Market Demand, Trends & Forecast by 2034
Coverage: By Type (Multi-Rotor, Fixed Wing); Services (End-To-End Solution, Point Solution); End-User (Renewable, Power) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00006318
- Category : Electronics and Semiconductor
- No. of Pages : 150
- Available Report Formats :


- Last update date : September 17, 2026


2025 Market Size
US$ 1.04 Bn
Base year value
2034 Forecast
US$ 3.11 Bn
Projected by 2034
CAGR 2026-2034
12.90 %
Growth rate
Addressable Market
US$ 18.02 Bn
(2026-2034)
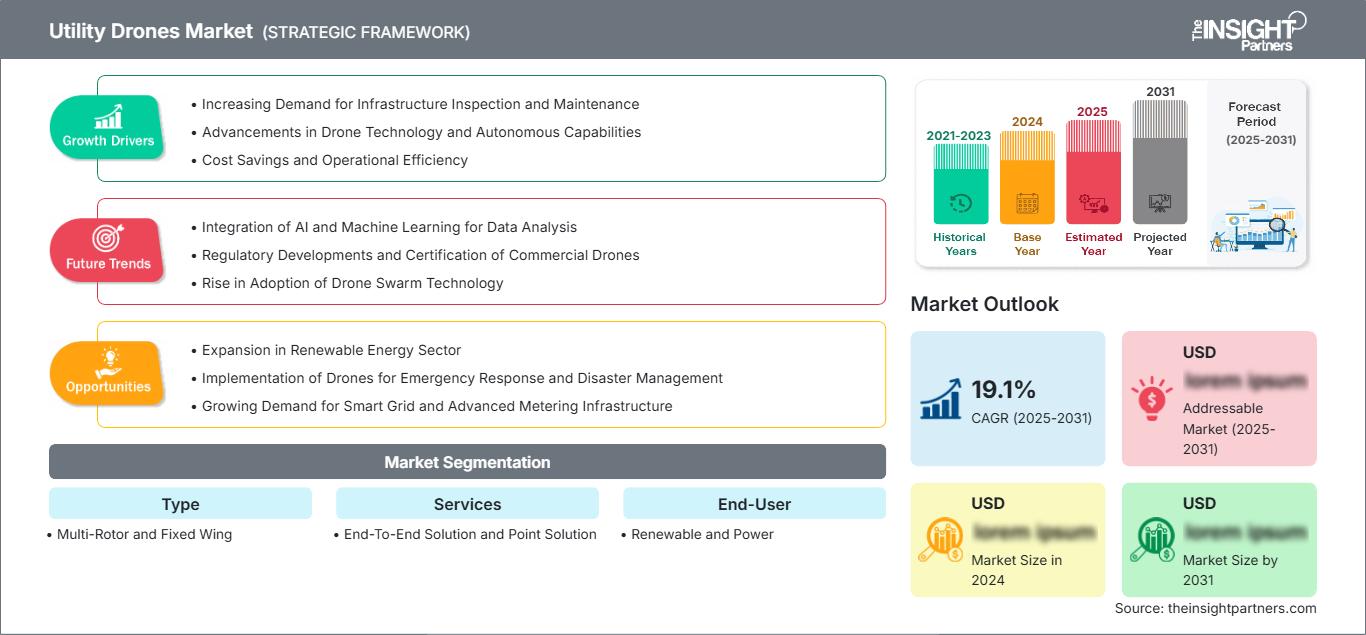
The utility drones market is projected to grow from US$ 1.04 billion in 2025 to US$ 3.11 billion by 2034, registering a CAGR of 12.90% during 2026–2034. Demand is being shaped by electric grid modernization, renewable asset monitoring, remote infrastructure inspection, and the need to reduce worker exposure during power line, substation, wind turbine, and solar farm assessments.
North America remains a major adoption hub as utilities expand aerial inspection programs across transmission, distribution, and renewable assets. The region benefits from large power infrastructure networks, increasing use of thermal and LiDAR payloads, and evolving beyond visual line of sight rules that support wider operating areas for grid inspection drones, contributing significantly to the Utility Drones Market size.
Utility Drones Market Assessment and Insights
- North America: North America accounted for an estimated 34–38% share in 2025 and is expected to grow at a CAGR of 11.8–13.2% during 2026–2034, supported by grid resilience programs, wildfire risk management, and utility-scale renewable monitoring.
- U.S.: The U.S. represented nearly 72–78% of North America in 2025 and is projected to grow at a CAGR of 12.0–13.5%, driven by transmission inspection demand and BVLOS readiness.
- Europe: Europe held an estimated 24–28% share in 2025 and is forecast to expand at a CAGR of 10.8–12.4%, led by the UK, Germany, France, Italy, and Spain.
- Asia Pacific: Asia Pacific represented about 22–26% share in 2025 and is expected to grow at a CAGR of 13.6–15.2%, with China, Japan, India, South Korea, and Australia leading deployments.
- Largest Segment: Multi-rotor drones held an estimated 58–64% market share in 2025 and are projected to grow at a CAGR of 12.1–13.4% because of stable hovering, camera precision, and inspection flexibility.
- High Growth Segment: End-to-end solutions held about 46–52% share in 2025 and are expected to grow at a CAGR of 13.8–15.1%, reflecting demand for integrated flight, analytics, and reporting workflows.
- Key companies analyzed in detail: Aerodyne Group, ABJ Drones, Asset Drone, Cyberhawk Innovations Limited, Delair, HEMAV S.L., PrecisionHawk, Sharper Shape Inc., Sky Futures, Terra Drone Corporation.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
Utility drone implementation has progressed from single inspection trials to recurring asset management projects. Previous implementations were based on pole and corridor inspection through visual surveys, whereas the recent ones include autonomous flights, thermal imagery, LiDAR technology, and artificial intelligence-driven defect analyses. Market growth is now becoming associated with regular data collection, timely fault discovery, and seamless integration into enterprise maintenance systems.
Additionally, utility companies are starting to favor aerial data due to aging infrastructure and expanding renewable power generation that need regular inspection but do not require proportional workforce increase. With the increasing reliability of drones and analytics, they will be used for purposes of prediction and condition assessment, besides emergency and vegetation inspection.
Utility Drones Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 1.04 Billion |
| Market Size by 2034 | US$ 3.11 Billion |
| Global CAGR (2026 - 2034) | 12.90% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Utility Drones Market Analysis
Demand in the utility drones market is being driven by the need to inspect high-voltage corridors, substations, solar farms, wind turbines, and remote assets at lower cost and lower risk. Drone technology is beneficial because it lowers reliance on physically climbing poles and manned helicopter flights while ensuring consistency in the images taken during inspections. Other benefits that utilities find attractive include near real-time data collection following storm events, vegetation growth, and equipment malfunctions.
The value chain consists of drone manufacturers, payload manufacturers, software analytics companies, mapping organizations, service providers, and utility asset management teams. Multirotor drones lead the market in close inspections, while fixed-wing drones play an important role in corridor mapping. Market analysis shows that services are becoming increasingly relevant as utilities demand validated data output.
Competition arises on account of platform dependability, integration of sensors, pilot network certification, analysis through AI, and regulations. Companies such as Cyberhawk Innovations Limited, Delair, Terra Drone Corporation, Aerodyne Group, and Sharper Shape Inc. create competition through their inspection expertise and software solutions. PrecisionHawk, HEMAV S.L., ABJ Drones, Asset Drone, and Sky Futures contribute to the industry through their unique aerial intelligence and inspection models.
Investment patterns show a shift toward scalable operations, especially as BVLOS frameworks progress in key countries. Vendors able to combine aircraft, compliance, secure data management, and actionable maintenance insights are better positioned than providers focused only on flight services. This competitive shift is increasing demand for integrated inspection programs across power and renewable assets, according to the Utility Drones Market report.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Utility Drones Market: Strategic Insights
Regional Insights
North America utility drones market
North America represented an estimated 34–38% utility drones market share in 2025 and is projected to grow at a CAGR of 11.8–13.2% during 2026–2034. Demand is supported by large transmission networks, wildfire mitigation needs, and increasing utility interest in automated inspection workflows. The U.S. and Canada are expanding drone use for power line inspection, storm response, vegetation assessment, and renewable asset monitoring.
Regulatory momentum is important for regional deployment. The FAA’s 2025 BVLOS proposal outlined requirements for operations, aircraft manufacturing, aircraft separation, authorizations, security, and reporting. This supports broader commercial drone use in infrastructure inspection and strengthens long-term utility drones market Forecasts.
U.S. utility drones market Market
The U.S. accounted for an estimated 72–78% of North American demand in 2025 and is expected to grow at a CAGR of 12.0–13.5% during 2026–2034. Electric utilities are increasing drone usage to inspect transmission lines, poles, substations, and solar farms, particularly where physical access is costly, hazardous, or delayed by weather-related outages.
Commercial authorization is improving operational scale. In April 2025, Osmose Utilities Services announced an FAA BVLOS waiver for aerial data collection across Class G airspace in the U.S., enabling larger inspection areas and more efficient infrastructure monitoring. Such developments reinforce utility drone adoption for proactive grid resilience.
Europe utility drones market Market
Europe accounted for an estimated 24–28% share in 2025 and is projected to grow at a CAGR of 10.8–12.4%. The UK remains a leading country due to utility inspection maturity, offshore wind monitoring, and established specialist service providers. Germany is expanding drone use around grid modernization and renewable integration, while France, Italy, and Spain are adopting drones for transmission, distribution, and solar asset management.
European utilities focus on safety, emissions reduction, and standardized inspection records. Drone operations are increasingly paired with AI image analysis and digital asset platforms. Demand is strongest where grid operators face aging infrastructure, growing renewable interconnections, and pressure to reduce inspection downtime.
APAC utility drones market Market
Asia Pacific held an estimated 22–26% share in 2025 and is forecast to register a CAGR of 13.6–15.2%. China leads regional deployment because of extensive grid infrastructure and renewable capacity, while Japan and South Korea emphasize high-reliability inspection technologies. India and Australia are adopting drones for remote line inspection, solar monitoring, and vegetation mapping.
Regional growth is supported by large utility networks, industrial automation, and policy interest in safer infrastructure monitoring. The region is expected to post the highest growth rate as utilities scale drone programs beyond pilots into structured inspection and maintenance cycles.
Middle East & Africa utility drones market Market
The Middle East and Africa market is forecast to expand at a CAGR of 10.2–11.8% during 2026–2034. Saudi Arabia and the UAE lead adoption due to power infrastructure expansion, solar project development, and smart city programs. South Africa is using aerial inspection to support grid reliability and reduce field risks in difficult operating environments.
Utilities in the region are adopting drones for transmission corridors, substations, solar farms, and oilfield power infrastructure. Growth remains below Asia Pacific but is becoming more structured as large energy projects require recurring aerial inspection and asset verification.
Segmentation Analysis
Type
Type segmentation includes Multi-Rotor and Fixed Wing. The segment is projected to grow at a CAGR of 12.1–13.4% during 2026–2034. The market scope remains strongest in multi-rotor inspection because these systems provide stable hovering, high-resolution imaging, and safe operation around towers, substations, and turbine components.
- Multi-Rotor: Multi-rotor drones dominate close inspection because they can hover around insulators, conductors, wind blades, and solar panels while carrying thermal, optical, and LiDAR payloads for detailed condition assessment.
- Fixed Wing: Fixed-wing drones are preferred for long corridors, high-volume mapping, and broad-area inspection, where endurance, range, and coverage efficiency are more important than stationary close-up imaging.
Services
Services include End-To-End Solution and Point Solution. The services segment is expected to grow at a CAGR of 13.8–15.1% during 2026–2034. Integrated programs are gaining traction as utilities seek flight planning, data acquisition, analytics, reporting, and maintenance recommendations within one workflow.
- End-To-End Solution: End-to-end solutions support utilities that need complete inspection execution, data processing, defect classification, and reporting without building large internal drone operations teams.
- Point Solution: Point solutions remain important for utilities with existing drone teams that need specific capabilities such as thermal payloads, LiDAR processing, vegetation analytics, or inspection software.
End-User
End-User segmentation includes Renewable and Power. This segment is expected to grow at a CAGR of 12.6–14.0% during 2026–2034. Power utilities currently account for the largest use cases, while renewable operators are increasing demand for solar panel imaging, wind blade inspection, and site performance monitoring.
- Renewable: Renewable operators use drones to inspect wind blades, solar modules, inverters, and large project sites, improving fault detection and reducing downtime across distributed generation assets.
- Power: Power utilities use drones for transmission, distribution, substation, and vegetation inspections, making the segment central to grid reliability, outage response, and preventive maintenance initiatives.
Opportunity Snapshot
| End-User | Revenue Contribution | Trend Tag | Adoption Stage |
| Renewable | Medium | Blade Analytics | Scaling |
| Power | High | Grid Resilience | Mature |
Utility Drones Market Growth Drivers and Impact Analysis
Grid reliability programs increase aerial inspection demand
As older systems and harsh weather conditions add strain to the reliability of the network, utilities have focused their efforts on quicker defect detection. With the aid of drones, utilities are able to assess their conductors, poles, insulators, substations, towers, and vegetation management areas without disrupting the services being provided. Their impact would be felt most where the process of inspecting manually is lengthy, dangerous, or inconsistent.
Renewable energy expansion creates recurring inspection workloads
Wind and solar farms need regular inspections since there could be reduced power generation due to blade damage, defective panels, dirt, faulty inverters, and weather conditions. Drones make it possible to inspect vast renewable energy farms at a very high speed, and the images captured are repetitive. With the increasing renewable energy capacity, there is a need for scalable solutions to ensure site integrity and operational uptime.
Regulatory progress supports scalable commercial operations
BVLOS policy developments are making economic sense for utility inspections over large areas. With BVLOS-capable drones flying over long distances with proper permissions and safety features, utilities are saving on man-hours, driving and crew deployments. Also, such policies make it worthwhile to invest in certified drones, data security processes and qualified drone flight crews. Such a driver is especially useful in transmission lines, substations and post-storm damage assessments.
Utility Drones Market Future Trends
AI-led defect classification and predictive maintenance
Utility drones market trends are shifting toward automated interpretation of inspection data. Rather than just providing images, the companies are now developing AI processes that classify cracked insulators, hotspots, vegetation incursion, corrosion, blade damage, and panel damage. This will help in clearing up the inspection backlog and improving the use of drone data for maintenance prioritization. With time, as historical data sets increase, predictive modeling will aid risk scores for grid and renewable assets.
BVLOS-enabled corridor inspection networks
Drones operating long distances are forecasted to change inspection in transmission and distribution operations. Network BVLOS will allow utilities to conduct monitoring on a regular basis along vast corridors, without having to use aircraft and repeat patrols on foot. Utilities will integrate stationary sites for launching drones, remote pilots, detect-and-avoid technology, and automated reporting to establish an inspection route that can be performed repeatedly.
Utility Drones Market Opportunities
Integrated drone-data platforms for utility maintenance teams
The most lucrative commercial angle comes from technology that transforms drone images into maintenance-ready data. It is not just aerial images that utilities want; they want to know where the problems are, how bad they are, the history of each asset, and how to integrate with their work orders. The vendors who can bridge their flight information with enterprise asset management systems will win bigger deals.
Renewable asset lifecycle inspection services
The renewable operators offer an emerging opportunity as the portfolios of solar and wind expand in different geographic locations. The drone technology can be used to help in the commissioning process, performance monitoring, warranty management, damage assessments, and decommissioning. The service providers could come up with a repeatable inspection service package based on the weather season, blade health, panel efficiency, and insurance management.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners provided valuable market intelligence that supported our global go-to-market strategy. Their team was professional, responsive, and attentive to our feedback, providing thoughtful analysis and helpful methodological clarifications throughout the project.
Junmo Kim Chief Financial Officer (CFO), Enertech Co., Ltd.
The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for