
공기 서스펜션 시장: 시장 점유율·성장·수요·전망 2034
에어 서스펜션 시장 규모 및 전망(2021년~2034년), 글로벌 및 지역별 점유율, 트렌드 및 성장 기회 분석 보고서 범위: 차량 유형별(승용차, 경상용차, 중형상용차, 대형상용차 및 트레일러), 구성 요소별(압축기, 에어 스프링 어셈블리, 공기 저장 탱크, 공기 압축기, 전자 제어 장치, 센서, 밸브 및 기타), 시스템 유형별(전자식 및 비전자식), 지역별(북미, 유럽, 아시아 태평양, 중동 및 아프리카, 남미 및 중앙아메리카)
- 상태 : 게시됨
- 보고서 코드 : TIPTE100000667
- 범주 : 자동차 및 운송
- 페이지 수 : 220
- 사용 가능한 보고서 형식 :


- 최종 업데이트 일자 : September 09, 2026


2025 Market Size
US$ 19.86 Bn
Base year value
2034 Forecast
US$ 47.45 Bn
Projected by 2034
CAGR 2026-2034
10.16 %
Growth rate
Addressable Market
US$ 299.10 Bn
(2026-2034)
The air suspension market was valued at US$ 19.86 billion in 2025 and is expected to reach US$ 47.45 billion by 2034; it is estimated to record a CAGR of 10.16% during 2026-2034.
Air Suspension Market Assessment and Insights
- North America held 27.51% share in 2025 and is growing at a CAGR of 10.08% between 2026–2034, driven by Class 8 fleet renewal, trailer telematics, and premium light truck demand.
- US represented 81.18% of North America in 2025 and is growing at a CAGR of 9.73% between 2026–2034, supported by long-haul trucking and luxury SUV platforms.
- Europe accounted for 25.96% share in 2025 and is growing at a CAGR of 8.90% between 2026–2034, led by Germany, the UK, France, Italy, and Spain.
- Asia Pacific captured 46.52% share in 2025 and is growing at a CAGR of 46.52% between 2026–2034, with China, Japan, South Korea, and India leading volume adoption.
- Largest Segment Passenger Cars held 41.39% market share in 2025 and is growing at a CAGR of 10.82% between 2026–2034.
- High Growth Segment LCV type held 26.55% market share in 2025 and is growing at a CAGR of 11.66% between 2026–2034.
- Key companies analyzed in detail: Hendrickson Holding LLC, Cummins Inc., ZF Friedrichshafen AG, Continental AG, thyssenkrupp AG, SAF-HOLLAND SE, Hitachi Astemo Americas, Inc., BWI Group, Boss Air Suspension, and Arnott Suspension Products.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
Technology migration is changing how OEMs specify suspension architecture. Conventional pneumatic systems are being upgraded with compact actuators, pressure sensing, height sensors, and software-managed valves, reducing component count while improving ride control. Production dynamics are also shifting toward modular assemblies that serve trucks, buses, premium SUVs, and trailers with shared platforms. These changes support Air Suspension Market growth as suppliers compete on weight reduction, installation simplicity, and lifecycle maintenance economics.
Future demand will be shaped by electrified commercial vehicles, urban buses, and export-oriented trailer manufacturing in emerging economies. Regulatory focus on axle load compliance, road safety, and lower driver fatigue is expected to favor electronically controlled systems. Asia-based vehicle production scale, North American freight intensity, and European comfort standards will collectively expand addressable demand while aftermarket replacement grows with aging fleets.
Air Suspension Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 19.86 Billion |
| Market Size by 2034 | US$ 47.45 Billion |
| Global CAGR (2026 - 2034) | 10.16% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Air Suspension Market Analysis
Demand is growing as air suspension enhances comfort, cargo care, and stability for the vehicle under changing load conditions. The Air Suspension Market growth profile is intricately linked to high-end vehicle content, commercial fleet operating time limits and trailer load management. Statistically, plus VANS/Minivans/ Large Buses, populated large commercial vehicles that provide a sales base for the US China Canada India augmented by public vehicle data from OICA should cater to the addressable installed fleet for replacement and OEM systems. The supply chain is anticipated to include: suppliers of rubber compound compressors ECU manufacturers, axle experts and vehicle OEMs.
The importance of component integration is growing as electronic control reduces mechanical complexity and enables predictive diagnostics. Suppliers with capabilities in pneumatics, sensing and software can capture a higher value per vehicle. Aftermarket specialists gain from the presence of failure-prone compressors and air springs in aging premium vehicles.
The competitive niches are unevenly divided between the chassis specialists and the broad-based automotive technology groups. ZF Friedrichshafen AG is expanding ECAS architectures, Hendrickson Holding LLC specializes in durable commercial suspension, Continental AG has controls and material know-how, and SAF-HOLLAND SE supplies trailer and axle systems. The AIR SUSPENSION MARKET study shows that suppliers that can mix reliability electronics OEM cycles will retain pricing-power.
Investment is shifting toward high-performance small-diameter pneumatic struts and dampers, lightweight air suspension modules, and electronics control software that reduces vehicle integration time. Arnott Suspension Products and BOSS air suspension improve aftermarket access, while Hitachi, BWI Group, thyssenkrupp AG, and Cummins support car control, chassis, and vehicle system engineering adjacent capabilities. Success is bid platform wins, service footprint, and validated durability.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Air Suspension Market:
요구 사항에 맞게 이 보고서를 사용자 정의하십시오.
이 보고서의 일부, 국가 수준 분석, Excel 데이터 팩을 포함하여 모든 보고서에 대한 사용자 정의를 무료로 받을 수 있을 뿐만 아니라 스타트업 및 대학을 위한 훌륭한 제안 및 할인을 이용할 수 있습니다
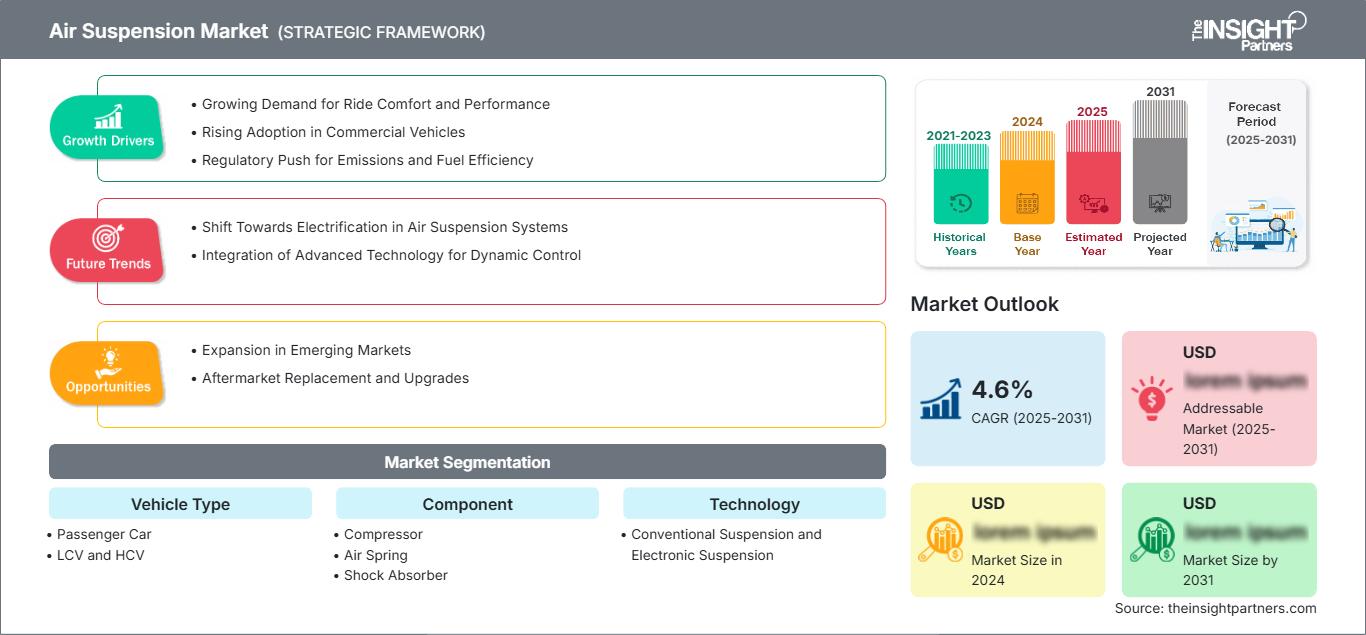
에어 서스펜션 시장: 전략적 통찰력
-
이 보고서의 주요 주요 시장 동향을 확인하세요.이 무료 샘플에는 시장 동향부터 추정 및 예측에 이르기까지 데이터 분석이 포함됩니다.
Regional Insights
North America Air Suspension Market
North America held 27.51% share in 2025 and is expected to grow at a CAGR of 10.08% during 2026–2034. The region benefits from high commercial vehicle utilization, large trailer fleets, and replacement demand for compressors, air springs, and electronic height sensors. Air Suspension Market share is supported by freight operators seeking cargo protection and predictable axle load management.
OEM adoption is highest in heavy trucks buses luxury pickups and SUVs, where ride comfort and load leveling are factors influencing buyer decisions. OICA commercial vehicle sales figures show the size of installed base in the US and Canada. At the same time, e-commerce logistics is pushing trailers to work harder. OEMs with local manufacturing and service centres will likely be the first to get fleet orders, Mainly because operators are shifting from cheapest cost to higher availability and fewer breakdowns..
U.S. Air Suspension Market
The US accounted for 80–84% of North America in 2025 and is projected to grow at a CAGR of 9.5–9.10% from 2026–2034. Demand is concentrated in Class 8 tractors, vocational trucks, trailers, luxury SUVs, and performance aftermarket applications. Domestic fleet operators value electronically managed ride height because it improves loading, unloading, and stability across long-distance routes.
Hendrickson Holding LLC, Arnott Suspension Products Inc. and Hitachi Astemo Americas, Inc. have become known as visible regional brands in the OEM, trailer and replacement markets. Trends of applications cover a trailer tire monitoring feature integrated, premium vehicle repairs adaptively carried out, and suspension packages for emergency and specialty vehicles. In addition, the market gets a boost from the increased miles traveled by commercial vehicles as well as maintenance outsourcing by big national fleets..
Europe Air Suspension Market
Europe represented 25.96% share in 2025 and is forecast to grow at a CAGR of 8.90% through 2034. Germany is the leading country because premium OEM platforms, trailer engineering, and commercial vehicle exports support higher adoption. The UK is advancing through fleet renewal and bus accessibility programs, while France benefits from logistics corridors and urban transport modernization.
Italy and Spain are responsible for trailer manufacturing, coach transportation, cross-border freight networks, and related activities. European regulation on vehicle safety, emissions, and driver working conditions ultimately drives the demand for comfortable, stable, and efficient suspension system. Continental AG, ZF Friedrichshafen AG, thyssenkrupp AG, and SAF-HOLLAND SE contribute to a strong supplier community that the region houses. These companies enjoy close relationships with OEMs, and have in-depth engineering capabilities..
APAC Air Suspension Market
APAC held 46.52% share in 2025 and is expected to grow at a CAGR of 10.86% during 2026–2034. China leads due to commercial vehicle scale, EV output, and bus production, while Japan and South Korea contribute advanced passenger vehicle platforms and supplier technology.
India together with Australia, increase demand by way of expanded logistics, freight on the national highway, mining support vehicles, and sales of premium SUVs. From IEA's electric mobility dataset comes a picture of increasing EVs being deployed, that is prompting changes in suspension for battery weight and ride control. Policies supporting clean transport and local industrial production, have a reinforcing effect regional sourcing and system integration.
Segmentation Analysis
Vehicle Type
Vehicle Type, Passenger Cars is expected to grow at a CAGR of 10.82% during 2026–2034. The Air Suspension Market scope across vehicle categories is widening as OEMs adapt pneumatic systems to premium passenger comfort, LCV payload flexibility, HCV stability, and trailer cargo protection. Heavy-duty platforms remain the anchor, but SUVs and electrified vans are lifting content per vehicle.
- Passenger Cars show demand in luxury sedans, SUVs, and electric models where ride comfort, adjustable height, and brand differentiation justify higher system cost.
- Light Commercial Vehicles (LCV) use pneumatic support for variable payloads, last-mile delivery stability, and driver comfort across dense urban routes with frequent loading cycles.
- Heavy Commercial Vehicles (HCV) dominate adoption because long-haul trucks, buses, and vocational fleets require axle load control, reduced fatigue, and stronger cargo protection.
- Trailers rely on air suspension to protect freight, reduce vibration, improve dock height matching, and support telematics-enabled maintenance programs.
Component
Component, Air Spring Assembly is projected to grow at a CAGR of 10.38% from 2026–2034. Demand is moving from isolated replacement parts toward integrated modules combining compression, storage, sensing, and control. Suppliers gain margin when they package validated assemblies, while service networks benefit from wear-related replacement of air springs, compressors, reservoirs, valves, and sensors.
- Compressors are critical for pressure generation and remain replacement-intensive because duty cycles, contamination, and heat exposure affect long-term performance in premium and commercial vehicles.
- Air Spring Assembly carries core load-bearing value, with demand tied to durability, rubber reinforcement quality, and compatibility with electronic height-control systems.
- Air Reservoir supports pressure storage and faster leveling response, especially in buses, trailers, and trucks that face repeated loading and unloading events.
- Air Compressor demand is sustained by OEM fitment and aftermarket repair, where performance consistency directly affects ride height, comfort, and system reliability.
- Electronic Control Unit enables adaptive ride management, fault detection, and integration with stability systems, making it central to higher-value electronic architectures.
- Sensors measure height, pressure, acceleration, and load conditions, supporting real-time adjustments and predictive maintenance across commercial and premium vehicle applications.
- Valves regulate air flow between springs, reservoirs, and compressors, influencing response time, ride balance, and system efficiency under changing road conditions.
System Type
System Type, Non-Electronic is forecast to grow at a CAGR of 9.55% during 2026–2034. Electronic systems are gaining preference as OEMs seek software-defined ride behavior, better integration with safety controls, and diagnostic visibility. Non-electronic systems remain relevant where cost, ruggedness, and simpler serviceability are more important than adaptive performance.
- Electronic systems lead value creation by combining sensors, software, and actuators to deliver adaptive ride height, stability support, and fleet-level diagnostic intelligence.
- Non-Electronic systems retain demand in price-sensitive fleets, rugged trailers, and markets where repair simplicity and mechanical reliability outweigh advanced control features.
Opportunity Snapshot
|
Vehicle Type |
Revenue Contribution |
Trend Tag |
Adoption Stage |
|
Passenger Cars |
Medium |
Luxury Ride |
Scaling |
|
Light Commercial Vehicles (LCV) |
Medium |
Payload Flex |
Scaling |
|
Heavy Commercial Vehicles (HCV) |
High |
Fleet Uptime |
Mature |
|
Trailers |
High |
Cargo Care |
Scaling |
Air Suspension Market Growth Drivers and Impact Analysis
Fleet uptime and cargo protection economics
Commercial fleets are now evaluating the cost of use instead of just the price when considering their trucks. A suspension system made of air can protect palletized freight, refrigerated cargo, electronics, and valuable parcels from vibrations This way reducing damage and the carrier will be able to fulfill the service-level agreement. And, varying the ride level helps with aligning the truck with the dock and Because of this faster loading is possible In particular for trailers used in different kind of distributions. In countries with a very well developed logistics industry and still no signs of improvement in driver shortages, the ability of the truck to be more comfortable and the lack of driver tiredness have become reasons for keeping drivers. The result is that nowadays when they buy new trucks and trailers, they tend to go for air suspension sets compressors air tanks, valves, and so on, as well the need to do some replacements in the field after some years of vehicle use.
Electrification changes suspension design requirements
New mass distribution, underbody packaging and different ride behavior of battery packs are the main reasons why battery-electric vehicles bring new requirements for chassis. Thanks to pneumatic systems it is possible in some cases to compensate for weight differences between empty and loaded conditions. This helps keep vehicl eattitude constant and improves ride comfort by not only relying on conventional springs. Kneeling and curb alignment to improve passenger accessibility are reasons why electric vehicles are becoming popular Mostly for buses and vans. Mobility reports made by IEA show that electricity is replacing other modes of power in different types of vehicles including cars vans buses, and trucks. As a result Original Equipment Manufacturers are redesigning suspension systems to suit battery-powered vehicles better. As more and more companies go electric, a higher number of height-controlled and pressure regulating systems equipped with advanced ride comfort software will be required.
Premium comfort expectations move into broader vehicle classes
Air suspension was initially popular in luxury sedans and executive coaches, but lately, the demand for such features is transferring to SUVs, pickups, and performance-oriented crossovers. People nowadays equate adjustableness of the height of the car, smooth riding over bumps, and minimization of body sway with luxury price tags. While, at the same, manufacturers employ these features to make model trims different without the need of a total vehicle platform redesign. The combination of a pneumatic suspension with adaptive damping and electronic stability functions is now the standard. The change will result that the number of components and parts per car is increasing. That means, the need to replace compressor, air struts, valve blocks, or sensors will be a growing part of the independent repair services due to In reality older premium cars are now moving to such channels.
Air Suspension Market Future Trends
Software-defined ride and predictive suspension health
Air Suspension market trends will mainly be about software-defined tuning alongside hardware alone. Future suspensions will make the necessary adjustments with the help of data like pressure height acceleration, and road-input so that the ride experience can be changed not only with the terrain but also with the payload and driven in different modes of driving. Combinations of suspension diagnostics and telematics can help fleet operators detect problems in the compressor and leakage patterns, and how the valves are responding before roadside failure happens. OEMs can update the different ride characteristics during the life of a car by way of the software change which makes a space for differentiators based not only on products but also on the provision of services. This way, more and more, only the companies with embedded electronics, high degree of attention to cybersecurity, and well-proven control algorithms that can be executed reliably in high-vibration conditions of commercial environments will benefit.
Modular pneumatic platforms for multi-vehicle architectures
Suppliers should focus on developing modular pneumatic systems that truck bus van, SUV, and trailer platforms will all be able to benefit from with minimum engineering change. By having a shared compressor, using smart actuators, and having expandable or shrinking (up/down scaling) air tank, you end up with one platform that covers vehicle lines and families of different OEMs. The service market benefit also comes from not needing to hold different stocks. The service parts networks can cover more with fewer parts families. For international suppliers, having a modulaire platform makes easier production in a region and sourcing to meet local regulations. The main result will definitely be quicker platform deployment, lessening the risk through integration, and having more steady income through standardized replacement parts and diagnostics-based service programs.
Air Suspension Market Opportunities
Aftermarket digitization and premium vehicle repair networks
Independent repair channels can extract significant value from air suspensions by offering replacement components and diagnosis, training and application support. Air suspension-equipped luxury vehicles with air struts, compressors and ride-height sensors usually enter cost-conscious repair cycles after warranty expiry. Because of this, these vehicles need a dependable source of aftermarket spare components. Suppliers who offer technician training, fitment data and air compressor/valve/sensor kits enables local workshops to reduce installation-related warranty claims. E-commerce parts catalogs and regional distribution facilities further make component procurement convenient. The best opportunity would be for a firm that simplifies complicated air suspension repairs into ready-formed installation procedures for workshop or fleet service providers.
Localized systems for emerging commercial vehicle production
New production locations in Asia, Middle-East & selected African markets provide an opportunity for localized assembly of vehicles suited to local road conditions, service levels and price expectation. Original Equipment Manufacturers (OEMs) and fleets require systems that are tolerant of heat dust overloading and rough roads while enhancing the safety & comfort levels of vehicles. Cost-effective localized sourcing will enhance project economics by replacing imports and reducing time-to-market. Joint programs with trailer builders, bus OEMs and logistics fleets can deliver specifications in a fast timeframe. Suppliers that operate on a global engineering platform yet take advantage of regional cost structure can establish early platform positions before widespread electronic suspension penetration.
Recent Developments
- June 2026: Hendrickson Holding LLC highlighted its trailer air suspension solutions for modern fleets, emphasizing proven ride technologies for cargo protection, durability, and operational reliability in trailer applications. The update reinforced the company’s focus on fleet productivity and suspension systems for commercial transportation.
- June 2025: ZF’s Commercial Vehicle Solutions (CVS) division announced the series production of the latest, fifth generation of its market leading Electronically Controlled Air Suspension (ECAS) technology, OptiRide ECAS for Hyundai Motor Company (HMC). The series production for HMC follows the start of production for one of the leading European commercial vehicle manufacturers in 2024.
- March 2026: Arnott introduced two new air suspension compressors engineered for European luxury and performance models, including Audi, BMW, Bentley, Lamborghini, and Rolls-Royce. These OE-style replacements are built to restore proper system function, helping installers complete repairs and return vehicles to the road.
Frequently Asked Questions

나빈은 맞춤형, 신디케이트 및 컨설팅 프로젝트 전반에 걸쳐 9년 이상의 전문 지식을 보유한 시장 조사 및 컨설팅 전문가입니다. 현재 부사장으로 재직 중이며, 프로젝트 가치 사슬 전반의 이해관계자들을 성공적으로 관리해 왔으며, 100편 이상의 연구 보고서와 30건 이상의 컨설팅 업무를 수행했습니다. 그는 산업 및 정부 프로젝트 전반에 걸쳐 다양한 업무를 수행하며 고객 성공과 데이터 기반 의사 결정에 크게 기여하고 있습니다.
나빈은 카르나타카주 VTU에서 전자통신 공학 학위를, 마니팔 대학교에서 마케팅 및 운영 MBA를 취득했습니다. 그는 9년 동안 IEEE 회원으로 활발하게 활동하며 컨퍼런스, 기술 심포지엄에 참여하고 지역 및 지역 차원에서 자원봉사 활동을 해왔습니다. 현재 직책을 맡기 전에는 IndustryARC에서 준전략 컨설턴트로, 휴렛팩커드(HP Global)에서 산업용 서버 컨설턴트로 근무했습니다.
- 포괄적인 시장 규모 산정 및 전망 분석
- 상세 시장 세분화 분석
- 심층적인 시장 동향 및 요인 분석
- 지역 및 국가별 인사이트
- 경쟁 구도 및 기업 벤치마킹
- 전략적 비즈니스 인텔리전스
사용 후기

The Insight Partners는 당사의 글로벌 시장 진출 전략을 뒷받침하는 가치 있는 시장 정보를 제공했습니다. 담당 팀은 전문적이고 신속하게 대응했으며 당사의 의견을 세심하게 반영했습니다. 또한 프로젝트 전반에 걸쳐 깊이 있는 분석과 유용한 방법론적 설명을 제공했습니다.
Junmo Kim 최고재무책임자(CFO), Enertech Co., Ltd.
Insight Partners의 SCADA 시스템 시장 보고서는 포괄적이며, 현재 동향과 미래 전망에 대한 귀중한 통찰력을 제공합니다. 팀은 매우 전문적이고, 신속하게 대응하며, 처음부터 끝까지 지원해 주었습니다. 저희는 매우 만족하며 Insight Partners의 서비스를 적극 추천합니다.
란 케뎀 파트너, Reali Technologies LTDs
아주 구체적인 소프트웨어 시장에 대한 보고서를 요청했는데, 팀에서 며칠 만에 보고서를 작성해 주셨습니다. 정보는 매우 관련성이 높고 잘 정리되어 있었습니다. 그 후 보고서에 몇 가지 수정과 추가 사항을 요청했습니다. 팀원들의 응답도 매우 빨랐고, 일주일도 채 되지 않아 최종 보고서를 받았습니다.
장-에르브 젠 의장, 퓨처 애널리티카
The Insight Partners와 함께 중요한 시장 조사 및 예측 작업을 진행했습니다. Insight Partners는 기회와 위험에 대한 명확한 통찰력을 제공하여 계획을 세우는 데 큰 도움이 되었습니다. The Insight Partners의 조사는 사용하기 쉬웠고, 탄탄한 데이터를 기반으로 했습니다. 덕분에 현명하고 자신 있는 결정을 내릴 수 있었습니다. The Insight Partners를 강력 추천합니다.
피유시 나그팔 수석 부사장, 하이빔 글로벌
Insight Partners는 탄탄한 분야 전문성을 바탕으로 통찰력 있고 체계적인 시장 조사를 제공했습니다. Insight Partners 팀은 처음부터 끝까지 전문적이고 신속하게 대응했습니다. 사용자 친화적인 웹사이트 덕분에 업계 보고서에 쉽게 접근할 수 있었습니다. 신뢰할 수 있고 고품질의 조사 서비스를 원하신다면 Insight Partners를 강력 추천합니다.
아다치 유키히코 대표이사, 딥블루 주식회사
The Insight Partners에서 시장 보고서를 구매한 것은 이번이 처음입니다. 처음에는 확신이 없었지만, 웹사이트를 방문하고 나서 위험을 감수하고 시장 보고서를 구매하는 것이 더 편하다는 것을 알게 되었습니다. 보고서의 품질과 고객 서비스에 매우 만족합니다. 처음 보고서를 보고 몇 가지 질문과 의견이 있었지만, 분석가와 이메일로 몇 차례 대화를 나눈 후, 전략 기획 과정에 참고할 수 있는 보고서를 확보했다고 생각합니다. 시간을 내어 긍정적인 경험을 선사해 주셔서 정말 감사합니다. 다른 사람들에게도 귀사의 서비스를 적극 추천할 것이며, 추가적인 시장 데이터가 필요할 때면 가장 먼저 귀사에 연락하겠습니다.
존 스즈키 사장 겸 최고 경영자, 이사회 이사, BK 테크놀로지스
나이지리아 감염성 질환 IVD 시장 관련 정보 요청에 응해 주신 귀사의 지원과 전문성에 감사드립니다. 귀사의 인내심과 지도, 그리고 할인 혜택을 기꺼이 제공해 주셔서 결국 계약을 성사시킬 수 있었습니다. 첫 만남을 통해 귀사가 저에게 심어주신 좋은 인상을 바탕으로 앞으로도 The Insight Partners와 함께할 수 있기를 기대합니다.
치지오케 박사 오니아 전무이사, 파인크레스트 헬스케어 유한회사구매 이유
- 정보에 기반한 의사 결정
- 시장 역학 이해
- 경쟁 분석
- 고객 인사이트
- 시장 예측
- 위험 완화
- 전략 기획
- 투자 타당성 분석
- 신흥 시장 파악
- 마케팅 전략 강화
- 운영 효율성 향상
- 규제 동향에 발맞춰 대응




















 무료 샘플 받기 -