
Pet Supplements Market Size, Share & Forecast 2034
Coverage: By Form (Chewable, Powder, and Others), Function (Joint Support and Mobility, Skin and Coat, Digestion and Gut Support, Weight Management, Brain Health and Calming, Multifunctional, and Others), Pet Type (Dogs, Cats, and Others), Distribution Channel (Supermarkets and Hypermarkets, Pet Specialty Stores, Pharmacies and Drugstores, Online Retail, and Others), and Geography (North America, Europe, Asia Pacific, the Middle East and Africa, and South and Central America)
- Status : Published
- Report Code : TIPRE00019974
- Category : Food and Beverages
- No. of Pages : 437
- Available Report Formats :


- Last update date : October 06, 2026


2025 Market Size
US$ 11.74 Bn
Base year value
2034 Forecast
US$ 19.74 Bn
Projected by 2034
CAGR 2026-2034
5.9 %
Growth rate
Addressable Market
US$ 142.28 Bn
(2026-2034)
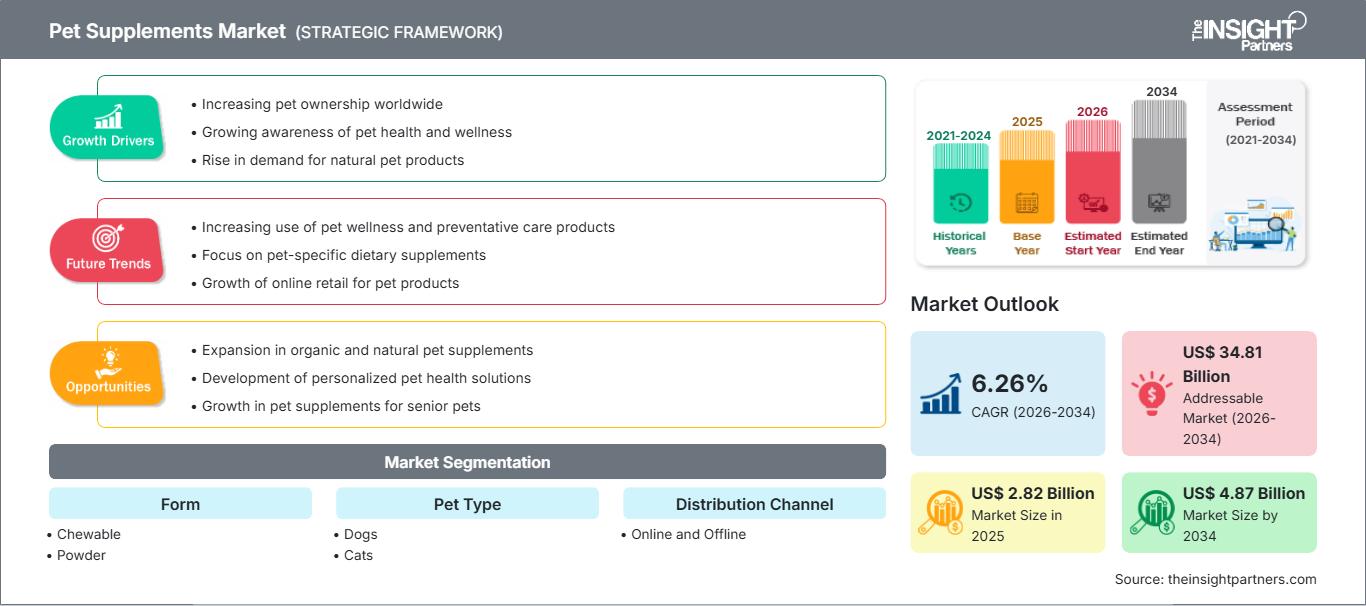
Pet Supplements Market is valued at US$ 11.74 billion in 2025 and is projected to reach US$ 19.74 billion by 2034, registering a CAGR of 5.9% during 2026–2034. The market includes a range of products designed to give companion animals nutritional, functional, and wellness support in various forms, for different types of pets, and through a variety of distribution channels. Today's demand is more and more influenced by preventive pet care, specialized nutrition, convenient methods of administration, and greater consumer concern about animal health and longevity.
North America continues to act as a major commercial centre in the pet supplements market, with a projected compound annual growth rate of about 5% up to 2034. This steady demand is due to the fact that pet ownership is well established, that spending on veterinary and wellness products is high, and that specialized supplements are readily available. The region also has advantages with well-developed specialist retail channels, veterinary distribution channels, direct-to-consumer brands, and general consumer awareness of functional pet products.
Pet Supplements Market Assessment and Insights
Regional Outlook
- North America: ~42% of the global market in 2025 | ~5% CAGR through 2034. Market position: North America holds the largest regional position, supported by high pet-care expenditure, mature specialty retail, strong veterinary participation, and broad adoption of preventive wellness products across dogs and cats
- US: ~84% of North American market revenue in 2025 | ~5% CAGR through 2034. Market position: The US represents the dominant country market within North America, supported by extensive pet ownership, established supplement brands, veterinary distribution, direct-to-consumer channels, and demand for joint, digestive, skin, and calming products
- Europe: ~25% of the global market in 2025 | ~5% CAGR through 2034. Market position: Europe represents a mature market characterized by established pet ownership and nutritional standards. Germany is the leading country in Europe, while the UK, France, Italy, and Spain provide substantial demand
- Asia Pacific: ~21% of the global market in 2025 | ~8% CAGR through 2034. Market position: Asia Pacific is the fastest-growing region, supported by rising pet ownership, urbanization, premiumization, online retail, and increasing interest in functional nutrition across China, Japan, South Korea, India, and Australia
Segment Outlook
- Dogs: ~50% Share in 2025 | ~6% CAGR through 2034. Market position: Dogs account for the largest product demand base because supplementation is widely associated with mobility, skin and coat maintenance, digestion, calming, and general wellness, while chewable formats make routine administration convenient
- Online Retail: ~30% Share in 2025 | ~8% CAGR through 2034. Market position: Online retail is expanding rapidly because digital channels provide broad product assortment, subscription purchasing, direct brand access, consumer reviews, personalized recommendations, and convenient recurring delivery for daily-use supplements
Competitive Coverage
H&H Group, Nutramax Laboratories, Nestlé S.A., Mars, Incorporated, FoodScience LLC, Virbac SA, Vetoquinol SA, NOW Health Group, Inc., PetHonesty LLC, Ark Naturals, Nordic Naturals, NaturVet, Ferra Pets, PetLab Co. Inc., and PetIQ, Inc.
Methodology
The Insight Partners follows Data Collection & Secondary Research, Primary Research, Data Analysis, and Data Triangulation & Final Review to validate market estimates and insights.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The market for pet supplements has moved from offering a general range of nutritional products to focusing on formulations designed for specific functions such as mobility, digestive health, the condition of the skin and coat, weight management, cognitive function, calming effects, and overall well-being. In the development of products there is a growing trend of combining well-known nutrients with functional ingredients and more convenient methods of delivery. Chewable tablets have become especially important since they incorporate supplementation into regular feeding routines, whereas powders and other forms offer greater flexibility when it comes to formulation. The different regulatory status of animal food and animal drugs also affects the claims made, the labelling, the choice of ingredients, and the strategies used in bringing products to market.
In the future, the market is expected to extend beyond the current levels of demand in North America and Europe. There is considerable potential in the Asia Pacific region as urban pet ownership and the trend towards high-end pet care grows, alongside improvements in digital commerce which enhances access to specialist brands. Manufacturers will probably raise their investment in formulation based on scientific evidence, in terms of palatability, the traceability of ingredients, and products targeted at specific life stages. Increased regulatory scrutiny of product claims and ingredient safety should also promote more transparent positioning and greater differentiation between nutritional support and therapeutic uses.
Pet Supplements Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 11.74 Billion |
| Market Size by 2034 | US$ 19.74 Billion |
| Global CAGR (2026 - 2034) | 5.9% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Pet Supplements Market Analysis
The market for pet supplements is based on the demand for preventive care and specific nutritional support rather than simply depending on regular pet food. Nowadays, pet owners are more likely to look for products which meet identifiable needs such as improving mobility, achieving a balanced digestion, addressing skin problems, controlling weight, and managing stress. When making a purchase, pet parents take into account veterinary advice, those who sell pet specialty products, information available through digital channels, and product reviews. This market ecosystem includes ingredient suppliers, experts in product formulation, contract manufacturers, branded product makers, veterinary networks, retailers, online platforms, and consumers.
The availability of products is influenced by access to vitamins, minerals, fatty acids, probiotics, botanical ingredients, proteins, and various special functional compounds. In the competitive landscape, manufacturers focus on the quality of their formulations, how pleasant the products are to take, their stability, the effectiveness of their manufacturing processes, and the support they provide for their claims. The use of private-label manufacturing also reduces the entry barriers for retailers and for new brands. The supply structure that results is a mix of large pet-care companies that have vertical integration, specialized supplement firms, and contract manufacturers, leading to a market in which large scale and scientific formulation abilities exist alongside a high degree of niche product specialization.
The competitive activity in the pet supplements market involves a range of pet-care companies and specialists in animal wellness. Companies such as Nutramax Laboratories, FoodScience LLC, Virbac SA, Vetoquinol SA, and PetIQ, Inc. have expertise in animal health or supplements, whereas Nestlé S.A. and Mars, Incorporated can make use of their large pet nutrition portfolios and well-established distribution networks. The H&H Group as well as specific brands like PetHonesty LLC, NaturVet, PetLab Co. Inc., Ark Naturals, and Ferra Pets offer focused propositions within particular categories. Nordic Naturals and NOW Health Group, Inc. on their part provide knowledge of ingredients and nutrition.
More of the investment is now being focused on formulation innovation, clinical support, digital customer acquisition, expanding manufacturing capacity, and increasing distribution reach. There is a growing shift in strategic positioning towards condition-specific products, the use of premium ingredients, subscription sales, and building up veterinary credibility. Acquisitions can help speed up access to proprietary ingredients and to established supplement brands, while partnerships offer the chance to expand geographic reach without having to set up manufacturing and distribution facilities again.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Pet Supplements Market: Strategic Insights
Regional Insights
North America Pet Supplements Market
In 2025 North America will make up about 42% of the global pet supplements market and is expected to grow at a compound annual growth rate of about 5% until 2034. The region enjoys mature pet ownership, high expenditure on the care of companion animals, a wide range of specialty retail outlets, and a well-established veterinary care system. Since consumers are familiar with functional supplements, demand has developed in a number of areas including mobility, digestive health, skin care, calming effects, and general wellness.
The United States is the main demand centre in the area, whereas Canada and Mexico offer further possibilities via the expansion of premium pet-care channels. The competitive situation in the region involves specialized supplement producers as well as those who produce a range of animal-health and pet-care products. Continued market growth is supported by direct-to-consumer sales, subscription schemes, recommendations from veterinarians and personalized products; yet regulatory requirements concerning the safety of ingredients and health-related claims are still significant issues for manufacturers.
U.S. Pet Supplements Market
In 2025 the United States accounts for about 84 percent of the revenue in the North American pet supplements market and is expected to grow at a rate of about 5% per year over the period to 2034. This demand is due to the large number of dogs and cats already in existence, the presence of established pet specialty retailers, veterinary clinics, large retail chains, and well-developed online channels. There is widespread consumer awareness of daily supplements as well as those designed for specific conditions.
The product offers support in areas such as joint mobility, digestive health, skin and coat, calming, weight management, and general nutritional needs. Companies including Nutramax Laboratories, FoodScience LLC, PetHonesty LLC, PetIQ, Inc., and NaturVet operate together with a number of other diversified pet-care organizations. Chewable formulations are still commercially viable since they combine a strong market position with ease of administration, and digital channels help to facilitate regular purchases as well as direct relationships between brands and pet owners.
Europe Pet Supplements Market
In 2025 Europe will account for about 25% of the global pet supplements market and is expected to grow at a rate of about 5% per year until 2034. The region benefits from a well-developed pet-care environment due to high levels of household pet ownership, an established pet food manufacturing sector, existing veterinary services, and comprehensive nutritional advice. Germany is the top country in Europe, with the UK, France, Italy and Spain also serving as major demand areas.
Germany has a big domestic pet-care sector and a well-developed retail infrastructure. The UK benefits from a long-standing specialist retail sector as well as a strong tendency to buy online, whereas in France and Italy opportunities are available through premium nutrition and products aimed at veterinary use. In the case of Spain, the country is aided by the growing number of pet owners and by the increasing availability of specialist products. Throughout the region, the extent to which products are differentiated is increasingly based on formulation transparency, the quality of the ingredients, the product's functional positioning, and compliance with the relevant feed and labelling requirements.
APAC Pet Supplements Market
The APAC region will account for about 21 per cent of the global pet supplements market in 2025 and is expected to grow at a rate of about 8 per cent per year on average until 2034, which means it is the fastest-growing region. China leads in the Asia Pacific area, thanks to a large consumer base for companion animals, the trend towards premium products, the increasing demand for functional nutrition, and the rapid development of digital commerce.
In Japan, there is a well-established tradition of owning pets together with a growing demand for care as animals age, and in South Korea there is a sophisticated market for high-end pet care and online retail. In India, greater awareness of pet nutrition and higher spending by urban households are providing benefits, and in Australia there is a fully developed pet care system coupled with strong demand for premium products. Regional growth is thus being caused by both mature markets and those in which penetration is still low.
Middle East & Africa Pet Supplements Market
The market for pet supplements in the Middle East and Africa is expected to expand at a compound annual growth rate of about 7% until 2034; this demand is due to urbanization, higher disposable incomes in some of the Gulf states, the growing veterinary infrastructure, and the increased availability of high-end imported pet products. Within the market structure that has been modelled, Saudi Arabia is regarded as the leading country in the Middle East and Africa region.
The UAE serves as a major centre for premium retail and for veterinary services, and South Africa has a relatively well-developed range of products for companion animals. Both Saudi Arabia and the UAE enjoy concentrated urban demand together with increasing access to specialized pet-care services. South Africa has a more extensive regional distribution network, whereas the rest of the Middle East and Africa remains more fragmented and relies on local retail development and the availability of imports.
Segmentation Analysis
Form
The Form section is expected to grow at a rate of about 6% per year up to 2034. The format chosen has a direct impact on palatability, the convenience of administration, dosage flexibility, portability, and the likelihood of customers buying it again. Chewable products are especially appropriate for incorporating into daily routines, whereas powders offer formulation versatility and can be mixed with food. Manufacturers are becoming more inclined to use innovations in format in order to differentiate their products from other similar functional ones.
- Chewable: Chewables occupy a strategically important position because they combine supplementation with an easy feeding experience. Demand is strong for joint, calming, skin, digestive, and general wellness applications where consistent daily administration influences repeat purchasing
- Powder: Powders provide flexible dosing and can be incorporated into regular food. Their importance is supported by formulations requiring customized quantities, functional blends, probiotics, and ingredients that are more difficult to incorporate into solid formats
Function
The Function segment is expected to grow at a rate of about 6% compound annual growth rate until 2034, and functional specialization allows brands to focus on specific consumer concerns rather than just offering supplements as a means of general nutrition; clear application areas such as joint support, digestive health, skin and coat, calming, and weight management help to support a range of differentiated products.
- Joint Support and Mobility: Joint products address mobility and life-stage concerns, particularly among aging and active animals. Glucosamine, chondroitin, omega fatty acids, and related ingredients support differentiated formulations and veterinary-oriented positioning
- Skin and Coat: Skin and coat products benefit from visible outcomes that are readily recognized by pet owners. Omega fatty acids, vitamins, minerals, and targeted nutritional blends are commonly positioned around coat appearance and skin condition
- Digestion and Gut Support: Digestive products are strategically important as consumers increasingly associate gastrointestinal health with broader pet wellness. Probiotic, prebiotic, fiber, enzyme, and synbiotic formulations allow brands to create specialized digestive propositions
- Weight Management: Weight-management products complement changing feeding routines and activity patterns. Formulations can combine nutritional ingredients with controlled-calorie approaches, creating opportunities for products positioned around healthy body condition and long-term wellness
- Brain Health and Calming: Cognitive and calming products address behavioral and life-stage concerns. Demand is supported by interest in stress management, aging, travel, separation, and daily behavioral wellness, particularly where owners seek non-pharmaceutical nutritional support
- Multifunctional: Multifunctional products combine several wellness objectives in one formulation, reducing administration complexity. They can appeal to consumers seeking convenient daily routines and enable brands to increase basket value through broader nutritional positioning
Pet Type
The Pet Type segment is expected to grow at a rate of about 6% per year up to 2034, with dogs still representing the largest demand area since they make use of a wide range of supplements relating to mobility, digestion, skin and coat, calming, and general wellness. Supplementation for cats is also increasing as specialized feline nutrition becomes more accessible.
- Dogs: Dogs represent the principal product base because owners commonly purchase supplements for mobility, skin, digestion, calming, and general nutritional support. Their broader acceptance of chewable formats also supports routine supplementation
- Cats: Cats offer growing opportunities through products addressing digestion, urinary wellness, skin and coat, calming, and senior-life-stage needs. Palatability and administration convenience remain particularly important because feline feeding behavior can limit product acceptance
Distribution Channel
The Distribution Channel segment is expected to grow at a rate of about 7% per year until 2034; channel development is becoming more and more important in relation to product discovery, repeated purchases, consumer education, and access to specialized formulations. Online retail is becoming more important together with purchases made at pet specialty stores and those linked to veterinary services, although physical channels still remain important for building trust and for providing product advice.
- Supermarkets and Hypermarkets: These channels provide broad geographic reach and high consumer visibility. They are particularly relevant for mainstream wellness products and established brands that benefit from frequent household shopping and accessible pricing
- Pet Specialty Stores: Specialty stores provide category depth and staff knowledge, making them important for functional and premium supplements. Their assortment supports comparison across conditions, formats, ingredients, and brands
- Pharmacies and Drugstores: Pharmacies and drugstores can connect supplements with broader health and wellness purchasing. Their relevance is stronger where consumers seek professionally positioned products and convenient access to established brands
- Online Retail: Online retail supports extensive assortment, recurring delivery, direct-to-consumer models, reviews, educational content, and targeted advertising. Its strategic importance is increasing as consumers become more comfortable purchasing specialized pet-health products digitally
- Others: Other channels include veterinary clinics, breeders, independent stores, and specialized service providers. These outlets can influence product selection through professional recommendations and direct relationships with pet owners
Opportunity Snapshot
| Distribution Channel | Revenue Contribution | Trend Tag | Adoption Stage |
|---|---|---|---|
| Supermarkets and Hypermarkets | Medium | Mass Reach | Mature |
| Pet Specialty Stores | High | Expert Retail | Mature |
| Pharmacies and Drugstores | Low | Health Access | Scaling |
| Online Retail | High | Digital Subscription | Scaling |
| Others | Medium | Vet Access | Scaling |
Pet Supplements Market Growth Drivers and Impact Analysis
Preventive Pet Health Spending and Longer Wellness Journeys
The growing availability of preventive pet care is leading to a rise in the use of supplements beyond just dealing with acute nutritional deficiencies. Nowadays, pet owners tend to see mobility, digestive function, skin condition, body weight, stress levels, and healthy ageing as ongoing wellness goals. As a result, their behavior when it comes to buying supplements is shifting from occasional use to regular consumption. For manufacturers, frequent use improves their ability to predict demand and enables them to adopt subscription-based business models. It also promotes the development of product ranges that are organized according to different life stages and specific health needs. Where supplementation is appropriate, involvement from veterinarians can help to enhance the credibility of the products, while retailers can use educational efforts to link particular functional requirements with the relevant products. The commercial implications are therefore not merely due to higher demand per unit; they also include opportunities for premium formulations, multifunctional products, and replenishment programmes which in turn boost customer retention.
Functional Nutrition Is Expanding Beyond Basic Vitamin Supplementation
The range of functional products is extending the category beyond simple vitamins and minerals to include those designed with specific physiological or behavioral aims in mind. Examples such as digestive support, mobility, skin and coat care, calming effects, and promoting healthy ageing give consumers more definite reasons for making a purchase than does general nutritional supplementation. This in turn offers business opportunities for suppliers of probiotics, omega fatty acids, botanical ingredients, special proteins, and other functional compounds. At the same time, the importance of formulation science, ingredient stability, palatability, and claims that are backed by evidence increases. Companies that can explain a particular use case without violating regulatory limits are able to stand out in the increasingly competitive market. The change is leading to portfolio segmentation according to condition and stage of life, while contract manufacturers can assist smaller brands that do not have their own formulation or production capabilities.
Expansion of Digital Commerce and Direct Brand Relationships
The way in which consumers discover, assess and restock pet supplements is being altered by digital commerce. Since online platforms can display detailed information about ingredients, dosage instructions, comparisons between products, educational content and customer reviews in a manner that physical shelves are unable to achieve, this is a major advantage. Subscription buying also matches well with supplements that need to be given repeatedly. This model enables new companies to access customers without having to set up large physical distribution systems. In response, established manufacturers can use omnichannel strategies which combine specialty stores, veterinary channels, marketplaces and their own direct websites. As competition grows, customer acquisition costs, product ratings, fulfilment reliability and customer retention will become ever more important commercial factors. Moreover, data from repeated purchases can be used to make targeted product recommendations and to assist with portfolio development.
Pet Supplements Market Future Trends
Precision Formulation Based on Life Stage and Individual Pet Needs
Product development in the future is likely to focus more on greater precision when it comes to formulation than on making general wellness claims that apply to all. It will be possible for manufacturers to divide their products according to age, the breed's characteristics, the level of activity, the animal's body condition, and specific nutritional goals. This shift could lead to smaller dosage forms, more focused combinations of ingredients, and more clear instructions for use. It also opens the possibility of offering personalized recommendations via digital platforms and through programmes supported by veterinarians. Since consumers are becoming more concerned about the quality of the ingredients, transparency regarding where they are sourced and the reasons for the formulation should become a more important factor in distinguishing one product from another. The final product structure could be similar to a portfolio of targeted nutritional interventions, with the clear distinction still being maintained between nutritional support and products that are subject to therapeutic or drug-related regulatory treatment.
Science-Backed Claims and Transparent Ingredient Positioning
As the range of products in this category grows, scientific support is likely to become more important. Since consumers, veterinarians, retailers, and regulators all have different requirements regarding evidence, safety, labelling, and the claims made about products, manufacturers will probably place a strong focus on the origin of their ingredients, on standardized formulations, quality testing, studies into palatability, and on having a well-documented functional reason for the product. Clear and open communication can also be used to distinguish nutritional products from those which make claims related to disease. While this trend may raise development costs for smaller brands, it can at the same time set up obstacles to entry that are favorable to companies that have the capabilities in terms of formulation, testing, and regulatory matters. In the long term, a position based on evidence should support those products which have clear functional aims, and which are produced with consistent quality rather than those that are mainly distinguished by their packaging or by general wellness statements.
Pet Supplements Market Opportunities
Scaling Premium Supplements Through Emerging Asia Pacific Markets
The Asia Pacific region presents an opportunity for expanding specialized supplement ranges since pet ownership, the demand for premium nutrition and digital commerce are all growing in the emerging economies. China provides scale together with an already existing demand for premium products, whereas India offers a market with comparatively low penetration but one in which awareness of pet nutrition is increasing. Regional strategies should involve using local formulations in combination with the proven global ingredient platforms and a digital-first method of distribution. Forming partnerships with veterinary networks, specialist retailers and e-commerce platforms will help to reduce the difficulties associated with entering the market and at the same time improve consumer education. Manufacturers should also adjust their product formats to match local feeding habits and purchasing behaviors. The greatest opportunity lies in offering products that deal with well-recognized functions such as digestion, skin and coat, mobility, calming and general nutritional support rather than with more complex propositions that require a great deal of consumer education.
Integrated Veterinary and Omnichannel Supplement Platforms
There is also the possibility of combining veterinary advice with retail and digital resupply methods. Since veterinary channels can build up trust in functional products, while specialist shops and online services offer wider availability and repeated purchases, companies could create linked ranges in which a pet owner gets a product recommendation, buys the supplement through their favorite channel, and then receives automatic resupply according to the expected usage cycle. This kind of approach can enhance continuity and give manufacturers better insight into repeated demand. Strategic partnerships among supplement brands, veterinary organizations, retailers, and digital platforms can thus lead to distinct routes to market. This strategy is especially applicable to products relating to mobility, digestion, skin, calming, and those for older pets, since in each of these cases continued administration is often a key part of the way the product is marketed.
Recent Developments
- January 2026: Zesty Paws, a brand under H&H Group, launched Zesty Paws Professional, its first product line developed exclusively for veterinary use, marking its entry into the veterinary channel. The debut includes two products: Native Canine Probiotic for digestive support and Healthy Aging NAD+ Precursor for longevity, both backed by veterinary distribution partnerships
- January 2026: Epiq Animal Health partnered with Zesty Paws to distribute veterinary-exclusive products, marking Zesty Paws' entry into the veterinary market. The agreement includes the distribution of two canine-native probiotic products developed from healthy dogs' digestive systems, targeting therapeutic use and ongoing digestive health maintenance
- November 2025: Native Microbials, Inc. partnered with Zesty Paws to launch a new line of pet health products featuring a novel microbial species derived from healthy dogs. This collaboration combines Native Microbials' expertise in microbial genomics with Zesty Paws' established reputation in the pet supplement industry, aiming to alleviate gastrointestinal dysbiosis in dogs. The products will be exclusively distributed through Zesty Paws' network in the US, focusing on enhancing canine digestive health
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners provided valuable market intelligence that supported our global go-to-market strategy. Their team was professional, responsive, and attentive to our feedback, providing thoughtful analysis and helpful methodological clarifications throughout the project.
Junmo Kim Chief Financial Officer (CFO), Enertech Co., Ltd.
The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for