
Anhydrous Aluminum Chloride Market Size, Growth & Demand by 2034
Coverage: By Form (Granule, Powder); Application (Dyes and Pigments, Pesticides, Pharmaceuticals and Cosmetics, Hydrocarbon Resins, Fumed Alumina, Others) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00009409
- Category : Chemicals and Materials
- No. of Pages : 150
- Available Report Formats :


- Last update date : August 24, 2026


2025 Market Size
US$ 1,039.57 Mn
Base year value
2034 Forecast
US$ 1,466.90 Mn
Projected by 2034
CAGR 2026-2034
3.90 %
Growth rate
Addressable Market
US$ 11,383.89 Mn
(2026-2034)
The anhydrous aluminum chloride market was valued at US$ 1,039.57 Million in 2025 and is projected to reach US$ 1,466.90 Million by 2034, expanding at a CAGR of 3.90% during 2026–2034. The demand will be boosted on account of the compound's utility as a Lewis acid catalyst and intermediate in the production of dyes, pigments, pesticides, pharmaceuticals, cosmetics, hydrocarbon resins, and fumed alumina. The growing importance of purity and reliability of supply has become an important factor influencing the purchasing decisions of industrial customers.
Anhydrous aluminum chloride market size in North America is driven by the production of specialty chemicals, synthesis of pharmaceuticals, manufacture of pigments, and hydrocarbons. It is anticipated that the compound will witness moderate growth at a rate of approximately 3.1% to 3.8% CAGR until 2034.
Anhydrous Aluminum Chloride Market Assessment and Insights
- North America: North America is estimated to account for a 18–22% share in 2025 and expand at a 3.1–3.8% CAGR during 2026–2034, supported by pharmaceutical synthesis, specialty chemicals, pigments, and domestic sourcing strategies.
- US: The US represents approximately 76–81% of North America's 2025 demand and is expected to grow at a 3.0–3.7% CAGR through 2034, led by pharmaceuticals, chemical processing, and advanced materials.
- Europe: Europe is estimated at a 22–26% share in 2025 and is projected to grow at a 2.8–3.5% CAGR, with Germany, France, Italy, the UK, and Spain supported by specialty chemicals, pharmaceuticals, pigments, and industrial processing.
- Asia Pacific: Asia Pacific is estimated to hold a 42–47% share in 2025 and grow at a 4.2–5.0% CAGR, led by China, India, Japan, and South Korea, where chemical manufacturing, agrochemicals, pharmaceuticals, and pigment production remain substantial.
- Largest Segment: Powder is estimated to hold a 58–63% share in 2025 and expand at a 3.5–4.2% CAGR through 2034, benefiting from broad industrial catalyst and synthesis applications.
- High Growth Segment: Pharmaceuticals and Cosmetics is estimated at a 15–19% share in 2025 and is expected to register a 4.5–5.2% CAGR through 2034, driven by expanding specialty synthesis requirements.
- Key companies analyzed in detail: Aditya Birla Chemicals (India) Limited, Base Metal Group, BASF SE, Dongying Kunbao Chemical, Gujarat Alkalies and Chemicals Limited, Gulbrandsen Chemicals, Juhua Group Corporation, Kanto Denka Kogyo Co., Ltd., Kemira Oyj, Nippon Light Metal Company, Ltd.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
There has been a trend towards greater control in terms of moisture content, particle size, purity, and packaging as this form of aluminum chloride is very hygroscopic and reactive. There has also been an increasing preference for screened or ground forms of the chemical which allows for controlled application whereas integrated production facilities for chlor-alkali could bring improvements in terms of sourcing raw material.
The future will be defined by the issues of capacity utilization, regional diversification of supply, and increased value-added products. Up-and-coming regions for chemical manufacturing such as India and Southeast Asia might become new customers whereas existing regions will probably focus on the stability of the supply chain. Regulatory concerns related to occupational exposure, transportation, storage, and emission of the product could motivate better practices.
Anhydrous Aluminum Chloride Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 1,039.57 Million |
| Market Size by 2034 | US$ 1,466.90 Million |
| Global CAGR (2026 - 2034) | 3.90% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Anhydrous Aluminum Chloride Market Analysis
Demand is related to downstream chemical conversions due to the catalytic and catalyst properties of aluminum chloride in various organic reactions. The value chain starts with raw materials of chlorine and aluminum, followed by the processes of synthesis, purification, drying, particle size adjustment, packaging, and delivery. Chlor-alkali producers can minimize the exposure of feed stocks; others specialize in purity, grade uniformity, logistics, and technical services.
Diversification of applications in Anhydrous Aluminum Chloride Market Report means less dependence on any single downstream industry. Catalytic activity and regular reaction characteristics are important for the dyes and pigments industry; pharmaceutical and agrochemical manufacturing may need specific impurity characteristics. Petrochemical cycle is exposed in hydrocarbon resins manufacturing; fumed alumina is the smaller market with higher technology content. Therefore, supply conditions are influenced by both chemistry feedstock costs and downstream industry utilization.
The competition is moderately consolidated where the competition is between the existing chemical manufacturers and the regional specialists. The global chemical facilities are present in the firm called BASF SE and the firm uses ground and screened anhydrous grades of chemical while the Indian firm Aditya Birla Chemicals (India) Limited and Gujarat Alkalies and Chemicals Limited has the advantage of India's chlor-alkali complex. There are Japanese firms Kanto Denka Kogyo Co., Ltd. and Nippon Light Metal Company, Ltd. which have specialization in inorganic chemistry.
The investment considerations tend to be more towards reliability of production, purity considerations, packaging efficiency and supply resilience as against just the expansion of the production capacity of a commodity type of chemical. The companies involved in regional network of supplies are Gulbrandsen Chemicals, Juhua Group Corporation, Dongying Kunbao Chemical, Base Metal Group and Kemira Oyj.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
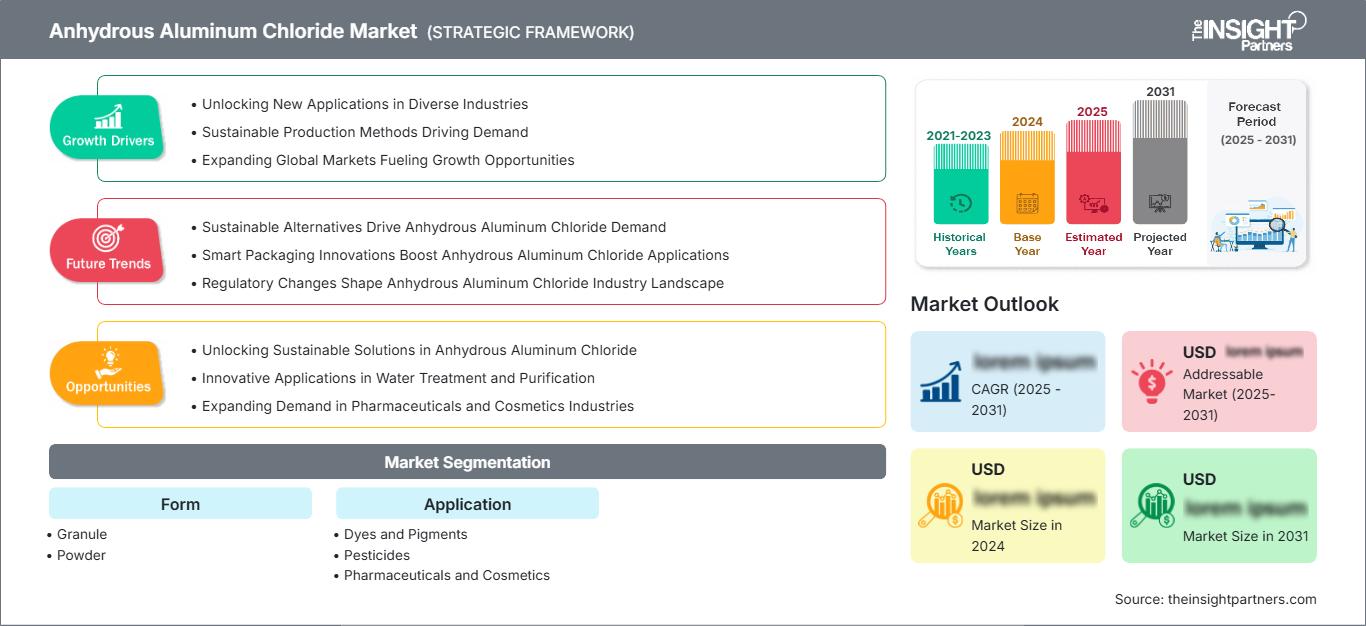
Anhydrous Aluminum Chloride Market: Strategic Insights
Regional Insights
North America anhydrous aluminum chloride market
North America is anticipated to contribute 18-22% of the Anhydrous Aluminum Chloride Market Share in 2025 and is expected to grow at a CAGR of 3.1-3.8% till 2034. The US dominates regional consumption, underpinned by the use of pharmaceutical intermediates, specialty chemicals, pigments, petrochemical processing, and resins. Chemical manufacturers prefer domestic sources for moisture-sensitive products.
Canada makes its contribution by specialty chemicals and resources-based processing, while Mexico adds to the demand through further downstream consumption with growing investments in chemicals and manufacturing. Modernizing chemical facilities and growing focus on resilience in the supply chain are key drivers of regional growth. Specifications of the product, integrity of the packing, and reliable deliveries continue to be critical purchasing factors as moisture exposure can compromise the performance of the product.
U.S. anhydrous aluminum chloride Market
USA constitutes about 76–81% of total demand in North America in 2025 and is forecasted to record a CAGR of 3.0–3.7% until 2034. In-country consumption occurs in areas like chemical synthesis, pharmaceuticals, pigments, hydrocarbon resins, among others which involve the use of catalysts. There are favorable conditions of having an extensive specialty chemical manufacturing industry and efficient distribution network.
Aditya Birla Chemicals (India) Limited, BASF SE, Gulbrandsen Chemicals, along with other international players, participate in international supply chains catering to USA-based clients while domestic distributors take care of industrial customers. Trends in the pharmaceuticals and advanced chemical manufacturing industries are creating more need for reliable sources of catalysts, while industrial consumers focus on purity, packaging, and batch consistency.
Europe anhydrous aluminum chloride Market
Europe is estimated to account for 22–26% of global demand in 2025 and is projected to expand at a 2.8–3.5% CAGR. Germany is the leading country because of its large chemical manufacturing base, followed by France, Italy, the UK, and Spain. Demand remains linked to pharmaceuticals, pigments, specialty chemicals, and hydrocarbon processing.
Germany has advantages of having an integrated chemical manufacturing process and high value-added synthesis process, while France integrates its pharmaceutical and specialty chemical demand. Italy and Spain have their consumption supported by dyes, pigments, chemicals intermediaries, and industrial processing. The UK is still relevant in pharmaceutical and specialty synthesis. Both producers and consumers in Europe are becoming more concerned about safety in handling, emissions, availability, and effective use of materials.
APAC anhydrous aluminum chloride Market
According to estimates, APAC is anticipated to account for 42–47% of global consumption by 2025 and is expected to register a growth rate of 4.2–5.0% CAGR and be the major regional market. China still retains its position as the dominant country, followed by India, Japan, South Korea, and Australia. Growth in chemical, pharmaceutical, agrochemical, pigment, and resin manufacturing drives demand.
China enjoys an extensive chemical manufacturing base, and India is becoming increasingly significant owing to its increasing capacities in pharmaceutical and specialty chemicals sectors. Japan and South Korea focus on premium quality inorganic chemicals and advanced synthesis capabilities. Australia makes for a smaller center of demand. Industrial investments, pharmaceutical localization, agrochemical manufacturing, and chemical sector growth are expected to drive demand.
Middle East & Africa anhydrous aluminum chloride Market
MEA is expected to witness a 2.9–3.7% CAGR till 2034. Saudi Arabia & UAE are some of the key regional centers for reasons like integration of the petrochemical industry and diversification of the industry; South Africa makes its contribution through chemicals, mining-related processing, and manufacturing industries.
The development of petrochemical industry forms a crucial demand base in cases of increased synthesis and resin manufacture based on hydrocarbons. The diversification of the industry in the Gulf economies can lead to higher use of specialty chemicals while infrastructure and manufacturing help in chemical processing. Availability, logistics, storage, and handling of the substance form crucial factors since it is moisture-sensitive.
Segmentation Analysis
Form
Form influences handling efficiency, dosing accuracy, packaging requirements, and customer-specific processing conditions. Powder is expected to remain the leading commercial form because of its broad suitability across chemical synthesis and pigment applications, while granules can provide advantages in controlled handling and reduced dust generation. Overall form demand is projected to expand at a 3.6–4.1% CAGR during 2026–2034.
- Granule: Granular material supports controlled feeding, reduced airborne dust, and easier industrial handling. Demand is particularly relevant where automated dosing, worker exposure management, and consistent feed characteristics influence process design.
- Powder: Powder remains the dominant form because it offers broad compatibility with catalyst-intensive synthesis and pigment processing. Producers compete through particle-size consistency, purity, packaging integrity, and moisture protection.
Application
Application diversity supports steady consumption because the material serves different chemical conversion pathways rather than relying on a single downstream industry. The application segment is expected to expand at a 3.8–4.4% CAGR during 2026–2034, with pharmaceutical, agrochemical, pigment, and resin manufacturing providing differentiated demand opportunities.
- Dyes and Pigments: Dyes and pigment manufacturing remains an important outlet because aluminum chloride supports catalytic and intermediate-production chemistry. Demand is linked to textile, coatings, printing, and colorant production, particularly in Asia.
- Pesticides: Agrochemical synthesis uses aluminum chloride in selected intermediate and catalytic pathways. Demand is influenced by crop protection manufacturing, regional agricultural output, and continued development of more specialized pesticide chemistries.
- Pharmaceuticals and Cosmetics: Pharmaceutical and cosmetic synthesis requires controlled chemical inputs for selected intermediates and formulation-related processes. This application benefits from specialty chemical localization, pharmaceutical capacity expansion, and greater emphasis on consistent raw-material quality.
- Hydrocarbon Resins: Hydrocarbon resin production represents a specialized industrial application where catalytic performance influences polymerization and product characteristics. Demand follows adhesive, rubber, road-marking, and coatings industries and remains sensitive to petrochemical feedstock cycles.
- Fumed Alumina: Fumed alumina production represents a technically specialized outlet associated with high-performance materials. Demand is supported by applications requiring controlled surface properties, including coatings, polymers, ceramics, and advanced industrial formulations.
Opportunity Snapshot
| Application | Revenue Contribution | Trend Tag | Adoption Stage |
| Dyes and Pigments | High | Color Chemistry | Mature |
| Pesticides | Medium | Crop Protection | Scaling |
| Pharmaceuticals and Cosmetics | High | Specialty Synthesis | Scaling |
| Hydrocarbon Resins | Medium | Resin Catalysis | Mature |
| Fumed Alumina | Low | Advanced Materials | Emerging |
Anhydrous Aluminum Chloride Market Growth Drivers and Impact Analysis
Expansion of specialty chemical and intermediate manufacturing
Growth in specialty chemical manufacturing creates structural demand because aluminum chloride participates in catalytic and intermediate-forming reactions across multiple chemical chains. Its role is particularly relevant where reaction selectivity, process efficiency, and controlled material quality influence output economics. Expansion of pharmaceutical, agrochemical, pigment, and resin manufacturing can therefore translate into incremental consumption without requiring proportional growth in any single application. For producers, this diversification supports steadier plant utilization and encourages investments in purification, particle-size control, packaging, and logistics. Regional chemical localization also creates opportunities for suppliers with shorter delivery routes and reliable technical specifications. The resulting market impact is strongest in Asia Pacific, where chemical capacity additions and downstream manufacturing expansion are broadening the customer base and increasing the importance of dependable catalyst availability.
Increasing pharmaceutical and agrochemical production capacity
Pharmaceutical and agrochemical manufacturing is becoming a more important source of demand as producers expand intermediate capacity and diversify sourcing across Asia and other emerging chemical hubs. Aluminum chloride is used in selected synthesis pathways where Lewis-acid catalytic activity can support efficient transformations. Increasing production volumes can therefore raise demand for consistent grades, particularly where impurities or moisture affect downstream reactions. Contract manufacturing and localization strategies can further broaden the customer base by creating requirements for dependable small and medium-volume deliveries. Suppliers that maintain quality consistency, secure packaging, and technical documentation can improve customer qualification prospects. The market impact extends beyond direct volume growth because pharmaceutical and agrochemical customers often impose stricter procurement controls, encouraging producers to strengthen quality systems and improve traceability throughout manufacturing and distribution.
Development of higher-value and high-purity chemical grades
The growing use of specialized chemical processes is increasing the value of purity, particle control, and reproducibility rather than relying solely on bulk material availability. High-purity grades can address customers with demanding synthesis requirements, while tailored particle-size distributions can improve dosing and process control. This creates opportunities for manufacturers to differentiate through purification technology, packaging systems, quality assurance, and application-specific specifications. The commercial effect is a gradual shift from purely volume-driven competition toward a combination of product performance and supply reliability. Such differentiation can also improve customer retention because qualification of a chemical input within a sensitive process can require testing and validation. Producers able to demonstrate consistent specifications across batches are consequently better positioned to capture higher-value demand in pharmaceuticals, advanced chemicals, pigments, and specialized materials.
Anhydrous Aluminum Chloride Market Future Trends
Greater adoption of controlled-handling and moisture-management systems
Producers and downstream users are expected to increase investment in enclosed handling, moisture-resistant packaging, controlled storage, and automated feeding systems. These measures can reduce product degradation, improve worker safety, and limit material losses during transfer. Digital monitoring of storage conditions may also become more common as customers seek greater consistency across production batches. The Anhydrous Aluminum Chloride Market trend will be especially relevant for pharmaceutical, specialty chemical, and high-purity applications where small changes in material condition can influence process performance. Suppliers can respond by improving packaging formats, strengthening technical documentation, and offering application guidance around storage and handling. Over time, controlled-handling infrastructure is likely to become an increasingly important procurement consideration alongside purity, price, and delivery reliability.
Shift toward integrated and regionally diversified supply networks
Supply strategies are likely to become more diversified as chemical manufacturers seek to reduce exposure to single-country sourcing, transportation disruptions, and feedstock volatility. Integrated producers with access to chlorine and related chemical inputs can benefit from greater control over raw-material availability, while regional specialists can compete through proximity and flexible order fulfillment. Asia Pacific is expected to remain central to supply expansion, but North America, Europe, and India can gain strategic importance as customers seek shorter supply chains. This trend may encourage selective capacity upgrades rather than indiscriminate commodity expansion. Producers are also likely to strengthen distributor networks and inventory planning to serve customers requiring smaller, reliable shipments. The result should be a more regionally balanced supply structure with greater emphasis on resilience and qualification.
Anhydrous Aluminum Chloride Market Opportunities
High-purity grades for pharmaceutical and advanced chemical synthesis
Manufacturers in the Anhydrous Aluminum Chloride Market Forecast can pursue higher-value opportunities by developing grades designed for customers with stringent impurity, particle-size, and consistency requirements. Pharmaceutical intermediates and advanced chemical synthesis can support premium positioning where material specifications directly influence reaction performance and downstream purification costs. Investment priorities include improved purification, analytical testing, controlled packaging, and batch traceability. Suppliers can also develop technical support capabilities that help customers optimize dosing and storage. India, China, Japan, and North America offer attractive opportunities because of their expanding or established pharmaceutical and specialty chemical manufacturing bases. A differentiated grade strategy can reduce dependence on commodity pricing and create longer-term customer relationships when products become qualified within sensitive manufacturing processes. This opportunity is particularly relevant for producers seeking margin expansion without relying exclusively on capacity additions.
Regional production and distribution hubs in emerging chemical markets
Emerging chemical manufacturing centers offer opportunities in the Anhydrous Aluminum Chloride Market Forecast for localized production, packaging, and distribution as downstream industries expand. India and Southeast Asia are particularly relevant because pharmaceutical, agrochemical, pigment, and specialty chemical manufacturing is becoming more geographically diversified. Regional hubs can reduce transportation distances, improve inventory responsiveness, and address customer requirements for smaller shipment sizes. Producers can combine local warehousing with centralized manufacturing to balance scale economics and supply reliability. Partnerships with chemical distributors can further extend reach into fragmented customer bases. Investment decisions should consider access to chlorine and aluminum feedstocks, hazardous-material logistics, industrial infrastructure, and proximity to downstream users. Over time, regional supply models could become an important competitive differentiator, particularly where customers prioritize continuity of supply alongside technical specifications and cost.
Recent Developments
- June 5, 2025: Solvay selected BASF as its primary supplier of aluminum chloride for its Linne Herten plant in the Netherlands. The material is used in anthraquinone production for hydrogen peroxide. Solvay shifted sourcing from India to Germany and expects the change to reduce the carbon footprint of this raw material by more than 50%, highlighting growing emphasis on regional sourcing and lower-carbon chemical inputs.
- April 19, 2025: Norsk Hydro ASA advanced its proprietary HalZero technology, which converts alumina to aluminum chloride before electrolysis to eliminate CO₂ emissions from electrolysis and anode baking. Hydro was developing the technology at a dedicated test facility in Porsgrunn, Norway, with the aim of producing first aluminum in 2025 and industrial-scale pilot volumes by 2030. The development highlights a potential new technology pathway for aluminum chloride consumption in low-carbon primary aluminum production.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for