
Edge Banding Materials Market Size, Share & Demand by 2034
Coverage: By Material [Plastic (PVC, ABS, Acrylic, and Others), Wood, Metal, and Others] and End Use (Residential and Commercial & Industrial)
- Status : Data Released
- Report Code : TIPRE00019639
- Category : Chemicals and Materials
- No. of Pages : 150
- Available Report Formats :


- Last update date : October 26, 2026


2025 Market Size
US$ 1.97 Bn
Base year value
2034 Forecast
US$ 4.46 Bn
Projected by 2034
CAGR 2026-2034
9.5 %
Growth rate
Addressable Market
US$ 28.68 Bn
(2026-2034)
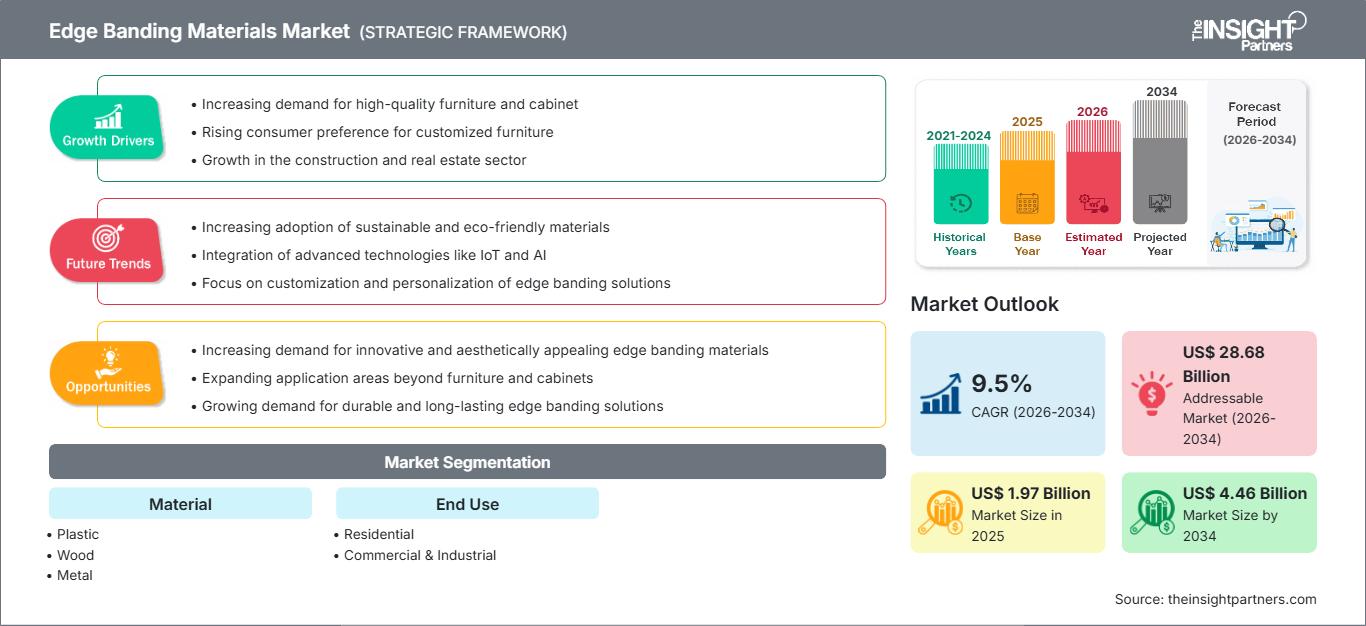
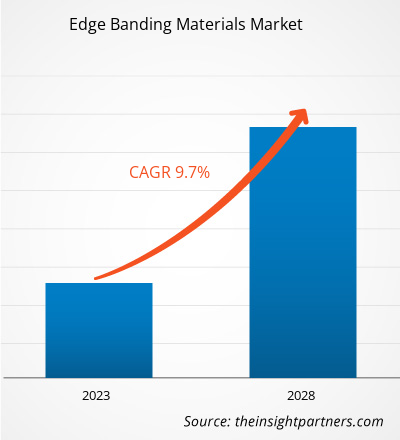
The Edge Banding Materials Market was valued at US$ 1.97 Billion in 2025 and is projected to reach US$ 4.46 Billion by 2034, growing at a CAGR of 9.5% from 2026 to 2034. The market covers materials applied to exposed edges of furniture, cabinetry, panels, and interior components to protect substrates and provide a finished appearance. The scope includes Plastic, Wood, and Metal materials across Residential and Industrial end uses.
North America represents an established demand center for the Edge Banding Materials Market, supported by cabinetry, furniture, commercial interiors, office refurbishment, and panel-processing activities. The region accounted for an estimated ~28% of global demand in 2025 and is expected to expand at ~8.4% CAGR through 2034. The U.S. remains the principal consumption market because of its extensive use of MDF, particleboard, laminate panels, and engineered wood products in residential and commercial applications. Demand is increasingly influenced by color matching, short production runs, flexible PVC solutions, and digitally printed finishes.
The Edge Banding Materials Market size is shaped in North America by the interaction between panel manufacturers, laminate producers, distributors, cabinet manufacturers, and specialized edgebanding companies. Suppliers such as Product Resources, Inc., Charter Industries, LLC., Aero Plastics Inc., and Frama-Tech LLC serve buyers that require matching colors, custom widths, multiple thicknesses, and rapid fulfillment. The market is therefore shifting from standardized edge strips toward application-specific materials and shorter customization cycles.
Edge Banding Materials Market Assessment and Insights
- North America: The region represented ~28% of the global Edge Banding Materials Market share in 2025 and is forecast to grow at ~8.4% CAGR through 2034. A mature cabinetry and furniture manufacturing base supports demand, while customized colors, flexible profiles, and faster distribution reinforce replacement and specification activity.
- U.S.: The U.S. represented ~72% of North American demand in 2025 and is expected to grow at ~8.2% CAGR. Residential cabinetry, commercial furniture, office refurbishment, and hospitality interiors create recurring demand for PVC, ABS, veneer, melamine, and specialty edge materials. Custom matching and low-volume availability remain important purchasing factors.
- Europe: Europe accounted for ~31% of global demand in 2025 and is expected to grow at ~9.0% CAGR. Germany, Italy, Poland, and France form important manufacturing and design centers. The region differentiates itself through zero-joint technologies, high-quality surface matching, recycled-content materials, and integration of edge design with decorative panels.
- Asia Pacific: APAC represented ~33% of the global market in 2025 and is projected to grow at ~11.1% CAGR. China, India, Japan, South Korea, and Southeast Asian furniture manufacturing clusters support demand. Rapid furniture production, export-oriented manufacturing, residential construction, and growing use of engineered panels provide a broad downstream base.
- Largest Segment: Plastic is the largest Material segment and is expected to expand at ~9.8% CAGR from 2026 to 2034. PVC, ABS, PP, and related thermoplastic solutions combine machinability, impact resistance, color flexibility, and compatibility with automated edgebanding equipment.
- High Growth Segment: Commercial & Industrial is the fastest-growing End Use segment at an estimated ~10.1% CAGR. Office furniture, hospitality, healthcare, institutional interiors, retail fixtures, and commercial cabinetry increasingly require durable edges, consistent surface matching, and designs compatible with higher-use environments.
- Key companies analyzed in detail: Product Resources, Inc.; SURTECO USA Inc.; Charter Industries, LLC.; JSO Wood Products; Sauers & Company Veneers; Aero Plastics Inc.; Lignadecor; Edgebanding Services, Inc.; REHAU Industries SE & Co. KG; Teknaform Inc.; Frama-Tech LLC; Rudolf Ostermann GmbH.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
Edge Banding Materials Market has grown beyond basic decorative elements to become a technologically advanced part of the process of manufacturing panels. Wooden veneer and paper products continue to play an important role in furniture making and cabinet manufacturing, whereas synthetic materials such as PVC, ABS, PP, PMMA, etc., have become more common due to the ability to automate application, to protect against impacts and moisture, and for decoration uniformity. Product development is getting increasingly intertwined with the surface material used.
According to the Edge Banding Materials Market report, advancements in manufacturing technology are shifting the economics of edge banding. Automatic edgebanders are able to perform a number of tasks such as adhesive application, pressing, trimming, scraping, and polishing within one technological line, thus emphasizing the role of dimensional accuracy and effective bonding. Technologies of zero joint with the use of laser, hot air, NIR, or another bonding methods require functional layers without visible edges. The latest innovations presented by REHAU in 2025 interzum include new types of edge banding materials and wood grain effect integrated into the milling radius.
Up until 2034, manufacturers will probably compete mainly in terms of material efficiency, recyclability, customizability, compatibility with processing technologies, and fastness of delivery. In Europe, manufacturers will offer more sustainable solutions. In Asia, manufacturing centers will increase production volumes and introduce more automatic panel processing lines. In North America, distributors will improve digital matching, stocks of edge banding materials and making-to-order services.
Localization of the supply chain will stay relevant since the furniture manufacturers will require guaranteed availability of matching edges in case of new collections of laminates and panels. Those companies that would manage to harmonize their color, print, extrusion, stock and technical services with those of board suppliers will lower their procurement hurdles. The future market will be characterized by a relevance of product range along with responsiveness and processing compatibility.
Edge Banding Materials Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 1.97 Billion |
| Market Size by 2034 | US$ 4.46 Billion |
| Global CAGR (2026 - 2034) | 9.5% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Edge Banding Materials Market Analysis
Edge Banding Materials Market development directly depends on the growth of engineered wood panels. Medium Density Fiberboards, Particle Boards, Plywood, Decorative Laminates create exposed edges that need to be protected and finished, thus becoming an integral part of the process of manufacture of furniture from panel material. Thus, the demand goes through the chain of selection of board material and surface finishing material, then the selection of edge banding materials and purchase, followed by their automatic or manual application while manufacturing furniture.
Material selection depends on the purpose of the usage. Plastic edges are more desirable for use in cases when impact resistance, moisture resistance, uniformity of color, and automation of the process is required. Wood and veneer edges are used when there is a need to provide furniture with a natural look or when there is a need to combine edge banding materials with expensive furniture surfaces. Metals can be useful for special cases, where there is a need to create certain visual effect or improve mechanical characteristics of edge materials.
The supply chain is diverse with integrated producers, specialized extruders, veneers, distributors, and services. Product Resources, Inc. offers various types such as PVC, ABS, veneer, melamine, metal, and digital print edges, whereas JSO Wood Products merges the wood veneer products with wood, PVC, polyester, melamine, and specialty edges. The wide range of options allows furniture manufacturers to source edgebanding using either standardized stocks or customized edgebanding material.
Edgebanding competitiveness is becoming highly dependent on connecting the surface to the edgebanding. SURTECO USA Inc. gains competitive advantage due to the wide product range of thermoplastic and paper melamine edges, while REHAU Industries SE & Co. KG offers differentiated solutions through its RAUKANTEX range, which covers both conventional and zero-joint products. Teknaform Inc. concentrates on the customization of PVC and ABS edges for North America's laminate and panels producers.
There’s going to be another level of competition in digital printing. Specialized printing makes it possible for suppliers to replicate the look of wood grain, stones, graphics, and other decorative finishes without holding each design as a conventional, stocked SKU. In this way, there is no danger of furniture producers having to settle on an edge match when they add a new surface. Thus, investment should go into extrusion, printing capability, digital designs, and automated matching systems.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Edge Banding Materials Market: Strategic Insights
Regional Insights
North America Edge Banding Materials Market
North America accounted for ~28% of global demand in 2025 and is projected to grow at ~8.4% CAGR through 2034. The area possesses a developed system of furniture and cabinetry driven by remodeling of houses, commercial interior, hotel facilities, healthcare buildings, office furniture and retail fixtures. The United States is the major consumer country, and Canada is an important location of production and distribution.
In 2025, North America was expected to show ~72% share of demand from the U.S. with the estimated ~8.2% CAGR. Competitors are engaged in the competition for color ranges in stock, matching colors, small-order production and compatibility with widely used laminates and TFL products. Charter Industries, LLC. offers extensive range of PVC and veneer edgebanding, while Aero Plastics Inc. produces flexible and rigid PVC and ABS edge products.
Canada has a significant share of extrusion and panel-oriented supply chain participants. Teknaform Inc. produces PVC and ABS edgebanding as well as performs color and texture matching for furniture and cabinetry use. It is a good example of production process that includes extrusion, printing, priming and coating of materials.
U.S. Edge Banding Materials Market
The U.S. market is characterized by a broad customer base ranging from large furniture producers and cabinet manufacturers to commercial millwork shops and smaller woodworking businesses. Procurement increasingly combines standard stocked products with custom runs. Product Resources, Inc. and Edgebanding Services, Inc. provide distribution-oriented models, allowing buyers to source multiple material categories without maintaining large inventories.
The market also rewards fast matching of new decorative panels. Frama-Tech LLC has expanded its focus on digitally printed and customized edgebanding, helping designers and manufacturers obtain matches for newer laminate surfaces. This trend is relevant because furniture producers increasingly introduce differentiated decors while expecting the edge to maintain a seamless visual relationship with the panel.
Europe Edge Banding Materials Market
Europe represented ~31% of global demand in 2025 and is projected to grow at ~9.0% CAGR. Germany, Italy, and Poland are important because of their furniture manufacturing, woodworking machinery, panel production, and interior design ecosystems. Germany has a particularly strong supplier base for edgebanding technologies and distribution services.
Germany combines advanced furniture manufacturing with demand for high-precision processing. Rudolf Ostermann GmbH supplies ABS, melamine, acrylic, aluminum, and real-wood edgings and supports zero-bondline applications. REHAU Industries SE & Co. KG has developed RAUKANTEX solutions around invisible joints and different processing technologies. These capabilities reinforce Europe's shift toward integrated surface-edge systems.
Italy contributes through furniture design, machinery, and premium interior manufacturing, where decorative coordination and natural material appearance influence product selection. Poland and neighboring Central European manufacturing clusters support high-volume furniture production and export activity. The European market is therefore shaped by both premium design requirements and industrial-scale production efficiency.
APAC Edge Banding Materials Market
APAC accounted for ~33% of global demand in 2025 and is projected to expand at ~11.1% CAGR, making it the fastest-growing core region. China is the principal production center because of its extensive furniture, cabinetry, panel, and export manufacturing base. Domestic demand and export-oriented furniture production both support the adoption of PVC, ABS, PP, melamine, and veneer edges.
India is expanding its furniture manufacturing and modular cabinetry ecosystem, increasing the need for coordinated decorative panels and edge materials. Local production and imported premium grades coexist, creating opportunities for suppliers that can provide consistent color matching and processing support. The growth of organized furniture production is shifting purchasing away from purely manual finishing toward more standardized edge application.
Japan and South Korea contribute through advanced furniture manufacturing, precision processing, and higher expectations for surface quality. Across Southeast Asia, manufacturing relocation and export-oriented furniture production provide additional demand. The region's growth profile reflects a combination of new furniture capacity, increasing use of engineered panels, urban housing demand, and broader adoption of automated woodworking machinery.
MEA Edge Banding Materials Market
The MEA market remains smaller than the principal manufacturing regions but has opportunities in residential interiors, hospitality, retail fit-outs, office furniture, and imported panel-based cabinetry. Demand is concentrated in markets with strong construction and interior-development activity, particularly the Gulf states and South Africa. Suppliers that can maintain inventory close to furniture production clusters can reduce lead-time constraints associated with imported edge materials.
South & Central America Edge Banding Materials Market
South and Central America are supported by residential furniture, kitchen cabinetry, commercial interiors, and wood-panel processing. Brazil provides the largest manufacturing base in the region, while other markets contribute through furniture imports, local cabinet production, and interior renovation. Currency conditions and import costs make distribution efficiency an important competitive factor, particularly for specialized materials and smaller production runs.
Segmentation Analysis
Material
Plastic is the largest Material segment and is expected to grow at ~9.8% CAGR. PVC remains important for cost-effective and durable furniture applications, while ABS and PP are increasingly used where material characteristics, regulatory considerations, or design requirements favor alternatives. Suppliers are expanding colors, textures, gloss levels, thicknesses, and flexible grades to accommodate automated and curved-edge applications.
Wood is projected to grow at ~8.2% CAGR. Veneer edges remain relevant in premium furniture, cabinetry, architectural millwork, and applications where natural wood appearance is important. Suppliers such as JSO Wood Products and Sauers & Company Veneers provide multiple wood species and backing configurations. The segment benefits from continued interest in authentic wood finishes but faces competition from high-quality printed and textured thermoplastic alternatives.
Metal is expected to grow at ~7.4% CAGR. Metal edging remains a specialized material choice used when designers require a distinctive appearance or specific functional characteristics. Aluminum and stainless-steel options can complement contemporary furniture, commercial interiors, and specialized fixtures. Growth is therefore linked more to design specifications and premium applications than to broad-volume substitution.
End Use
Residential is expected to expand at ~9.0% CAGR. Kitchens, wardrobes, home offices, storage furniture, shelving, and modular furniture require edge protection and coordinated decorative finishes. Moisture exposure in kitchens and bathrooms increases the value of durable plastic edges, while premium furniture continues to use wood veneer and specialized decorative solutions.
Commercial & Industrial is expected to grow at ~10.1% CAGR. Offices, hospitals, schools, hotels, retail stores, laboratories, and institutional environments require edges that withstand frequent handling, cleaning, impact, and extended use. Procurement decisions often prioritize durability, processing consistency, replacement availability, and compliance with project specifications.
Opportunity Snapshot
| End Use | Revenue Contribution | Trend Tag | Adoption Stage |
| Residential | High | Modular Living | Mature |
| Commercial & Industrial | High | Durable Interiors | Scaling |
Edge Banding Materials Market Growth Drivers and Impact Analysis
Expansion of Modular Furniture and Engineered Wood Panels
The continued adoption of MDF, particleboard, plywood, and decorative laminates directly increases the addressable requirement for edge treatment. Modular kitchens, wardrobes, storage systems, office furniture, and ready-to-assemble products depend heavily on panel processing. As furniture producers standardize production around automated cutting and edging, suppliers benefit when their materials can be matched accurately to board surfaces and processed at high throughput.
Demand for Seamless Decorative Finishes
Furniture designers increasingly expect edges to appear integrated with the panel rather than as a separate strip. This is an encouraging development of zero-joint and digitally matched solutions. REHAU and SURTECO have both developed technologies designed to reduce visible transitions between panel and edge. The commercial implication is a shift from commodity edge supply toward systems that combine appearance, processing compatibility, and functional performance.
Growth of Commercial and High-Use Furniture Applications
Commercial furniture faces higher exposure to impact, cleaning, abrasion, and repeated handling than many residential applications. This increases demand for rigid PVC, ABS, PP, and other durable solutions. Healthcare, hospitality, education, office, and retail projects can therefore support higher-value specifications where consistent appearance must be combined with service life and easy maintenance.
Edge Banding Materials Market Future Trends
Zero-Joint and Adhesive-Free Processing
The Edge Banding Materials Market trends are moving toward joining systems that minimize or eliminate visible adhesive lines. Laser, hot-air, plasma, and NIR-compatible edge technologies allow manufacturers to create cleaner transitions while reducing conventional glue-line visibility. This trend will influence both premium furniture design and automated production because manufacturers can pursue improved appearance without sacrificing processing efficiency.
Recycled and Lower-Impact Edge Materials
Sustainability requirements are increasingly influencing material selection. SURTECO's CIRCULAR EDGE portfolio illustrates the development of recycled-content PP edgebands designed to reduce the environmental footprint of edge products. Environmental product documentation and recycled-content certification can become increasingly important in commercial procurement as furniture manufacturers respond to material disclosure requirements and circularity targets.
Digital Customization and Surface Matching
Digital printing is expanding the number of designs that can be reproduced on edge materials. Instead of relying exclusively on large inventories of standardized colors, suppliers can produce customized graphics, wood-grains, and patterns in response to specific panel designs. This enables closer synchronization between surface launches and edge availability and reduces the likelihood of designers compromising on the intended furniture appearance.
Edge Banding Materials Market Opportunities
Integrated Matching Platforms for Furniture Manufacturers
A significant opportunity exists in digital platforms that connect board decors, laminate codes, edge specifications, color libraries, and production requirements. The target customers are furniture manufacturers, cabinet producers, distributors, and interior contractors who manage large numbers of surface combinations. Suppliers can strengthen customer retention by combining digital matching with sample ordering, inventory visibility, technical documentation, and rapid custom production.
The Edge Banding Materials Market Forecasts point toward greater value in integrated services rather than material supply alone. Companies that connect color development, production planning, and inventory management can reduce the time required to introduce new furniture collections and improve the probability that a matching edge is available when the panel reaches production.
Recycled-Content and Premium Thermoplastic Grades
Another opportunity is the development of recycled-content PP, ABS, and other thermoplastic grades that preserve machinability, appearance, and bonding performance. Furniture producers need sustainable materials without creating additional processing problems. Suppliers that can demonstrate consistent recycled-content quality while maintaining color stability and surface performance can target commercial projects, premium furniture, and customers with environmental procurement requirements.
Recent Developments
- November 2025: Frama-Tech LLC agreed to acquire EdgeCo Inc., with the transaction structured to integrate EdgeCo's employees, inventory, operations, and sales into Frama-Tech. The acquisition expands Frama-Tech's North American distribution footprint and strengthens access to edgebanding products and services for customers in the Northeast United States. The transaction also demonstrates continued consolidation among specialist distributors.
- May 2025: REHAU Industries SE & Co. KG presented new RAUKANTEX edgeband developments at interzum 2025, including textured structures and expanded natural-wood effects. The company highlighted technology that integrates detailed wood-grain into the milling radius, improving visual continuity while retaining impact resistance. The development reinforces the movement toward edges that function as an integrated design component rather than a simple protective strip.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners provided valuable market intelligence that supported our global go-to-market strategy. Their team was professional, responsive, and attentive to our feedback, providing thoughtful analysis and helpful methodological clarifications throughout the project.
Junmo Kim Chief Financial Officer (CFO), Enertech Co., Ltd.
The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for