
Epoxy Coatings Market Growth, Trends & Demand by 2034
Coverage: by Technology (Waterborne, Solvent Borne, Powder-Based); Application (Construction, Transportation, General Industrial, Others) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00009634
- Category : Chemicals and Materials
- No. of Pages : 150
- Available Report Formats :


- Last update date : September 01, 2026


2025 Market Size
US$ 46.04 Bn
Base year value
2034 Forecast
US$ 69.53 Bn
Projected by 2034
CAGR 2026-2034
4.69 %
Growth rate
Addressable Market
US$ 524.74 Bn
(2026-2034)
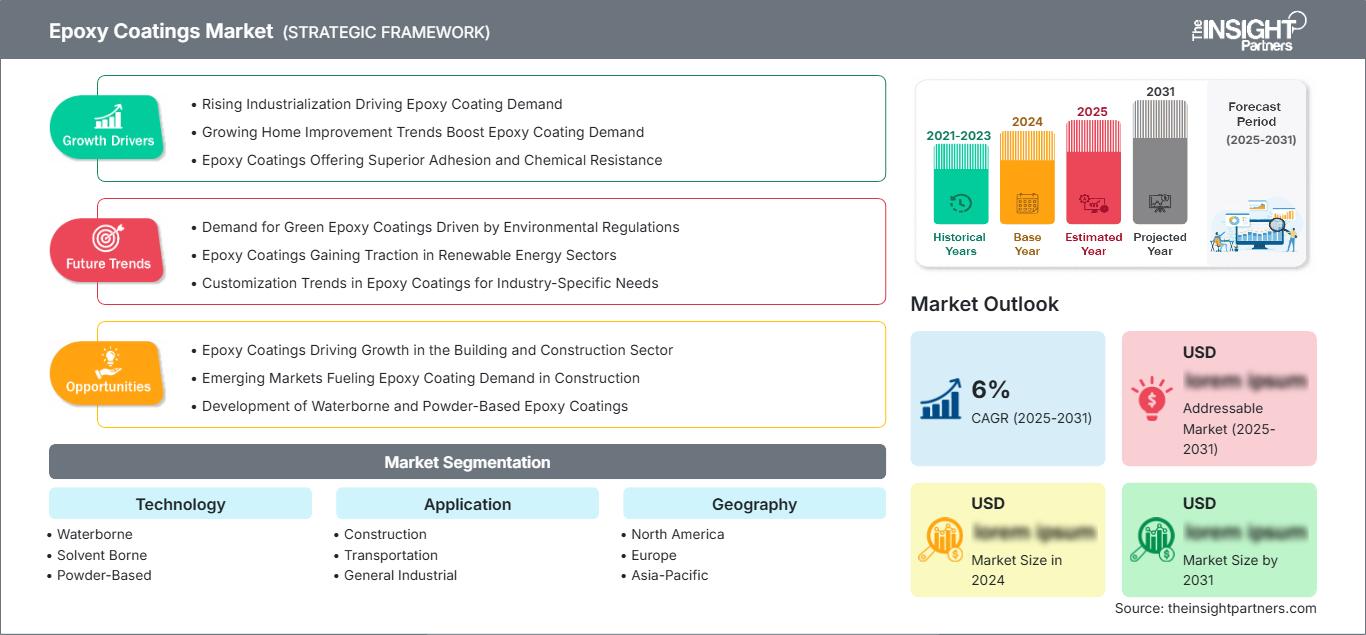
The Epoxy Coatings Market was valued at US$ 46.04 Billion in 2025 and is projected to reach US$ 69.53 Billion by 2034, registering a CAGR of 4.69% during 2026–2034. The market showcases a growing need for coatings which are durable, chemical-resistant and can protect surfaces from corrosion. The technology innovations being made include development of water-borne and powder coatings that are lower in emission while maintaining adhesion and mechanical resistance and protecting surfaces.
North America is a developed but resilient Epoxy Coatings Market Size where the demand comes from infrastructure replacement, upgrading of industrial units, transportation, and protective coatings. North America is also gaining advantage from rapid acceptance of low emission, fast curing and specialized substrates coatings. The region is investing in infrastructure, energy and commercial buildings, which are leading to stable demand.
Epoxy Coatings Market Assessment and Insights
- North America: North America is supported by infrastructure refurbishment, industrial maintenance, and transportation applications, accounting for a 24–28% share in 2025 and expanding at a 4.0–4.6% CAGR during 2026–2034.
- US: The US represents approximately 78–82% of North American demand, supported by infrastructure rehabilitation, industrial flooring, transportation assets, and protective coatings, with regional growth of 4.0–4.5% during 2026–2034.
- Europe: Europe holds a 20–24% share in 2025, with Germany, the UK, France, Italy, and Spain supporting demand through renovation, industrial protection, and lower-VOC technology adoption, growing at 3.5–4.1% during 2026–2034.
- Asia Pacific: Asia Pacific remains the largest regional market, holding a 45–49% share in 2025 and expanding at 4.0–4.6% during 2026–2034, led by China, Japan, South Korea, and India.
- Largest Segment: Construction within application is the largest segment, representing a 39–43% share in 2025 and growing at 4.2–4.8% during 2026–2034.
- High Growth Segment: Powder-Based technology is the high-growth segment, accounting for a 17–21% share in 2025 and expanding at 5.0–5.7% during 2026–2034.
- Key companies analyzed in detail: Akzo Nobel N.V., Axalta Coating Systems Ltd., BASF SE, Kansai Paint Co., Ltd., Nippon Paint Holdings Co., Ltd., PPG Industries, Inc., RPM International Inc., The Sherwin-Williams Company, Jotun A/S, Hempel A/S.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
Coatings technologies have increasingly trended towards formulations that offer durability and at the same time meet environmental standards where there are limitations on the use of VOCs by contractors and industrial end-users. Waterborne formulations have become significant where odor, worker exposure, and regulation play a role in deciding which products to use. In addition, powder coatings have become increasingly attractive since they can provide high transfer efficiency and low solvent usage. Manufacturers are focusing more on production methods that are fast, tolerant of surface preparation and longer maintenance interval.
Future demand forecasts point to an expansion of opportunities in new industrial development centers in Asia, Middle East and selected Latin American economies. Opportunities are expected to arise from infrastructure renewal, factory construction, energy and transportation investments which would increase demand for protective flooring and corrosion resistance coatings. The regulations will drive suppliers towards developing technologies with lower emissions while owners of assets will focus on the total lifecycle cost of the coating system and not just the cost of the product.
Epoxy Coatings Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 46.04 Billion |
| Market Size by 2034 | US$ 69.53 Billion |
| Global CAGR (2026 - 2034) | 4.69% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Epoxy Coatings Market Analysis
The demand is motivated by the need to guard concrete, steel, and other substrates against abrasion, chemical attacks, moisture, corrosion, and mechanical stress. Ecosystem includes resin and hardener manufacturers, formulations makers, applicators, contractors, distributors, equipment vendors, and the owners of industrial assets. Construction continues to be an important consumer, but the transportation and general industry needs coatings which would be able to preserve their functionality in conditions of cyclic loads and extreme operation. The supply is driven by the availability of resins, specialty additives, curing agents, energy prices, and regional production capabilities. The companies which have wider formulation range could better cope with the diversity of regulatory and operational needs. Local distribution systems continue to be important due to specific demands of projects.
The level of competition is rising owing to investment in innovation, local manufacture, and application by existing players in the coatings industry. The Epoxy Coatings Market Report highlights Akzo Nobel N.V. has a wide array of coatings in their product portfolio, while Axalta Coating Systems Ltd. keeps on investing in technology development within the various industrial uses. Product development and solutions for individual customers have been emphasized by BASF SE, Kansai Paint Co., Ltd., Nippon Paint Holdings Co., Ltd., and PPG Industries, Inc. RPM International Inc., The Sherwin-Williams Company, Jotun A/S, and Hempel A/S have been competing through specialist coatings, distribution, and expertise.
The value chain is also affected by an increasing trend of customizing the coating specifications. The need for coating formulations which are based on the type of substrate, environmental conditions, curing process, and temperature of operation is becoming more popular among industrial customers than standard formulations. In addition, this trend is motivating manufacturers to develop formulation capabilities and cooperation with applicators from a technical perspective. Distribution continues to play a key role in servicing fragmented construction and maintenance projects, whereas direct interactions with end-users are more common when dealing with big industrial clients. In addition, having regional production capacities is another way to enhance responsiveness and meet project-specific needs. With growing maintenance specifications, technical service-oriented suppliers will be able to increase their share in the market.
A second market factor that needs consideration is the growing role of lifecycle economics in industrial buying decisions. Asset owners are assessing coating systems not only by the cost but also by the frequency of maintenance, downtime risk, ease of application, and expected longevity. This trend opens up the possibility for high-end products that exhibit superior performance under challenging conditions. Positioning is thus no longer about resin technology alone but also about curing time, substrate tolerance, durability, and ease of application. In addition, coating manufacturers are also focusing on building regional alliances with contractors and distributors. With the growing need for maintenance of infrastructures and industrial assets, refurbing needs may create a dependable customer base.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Epoxy Coatings Market: Strategic Insights
Regional Insights
North America Epoxy Coatings Market
North America held a 24-28% of the Epoxy Coatings Market share of world demand in 2025 and is forecast to grow at a CAGR of 4.0-4.6% until 2034. Key drivers for the regional market include infrastructure refurbishment, modernization of industrial plants, maintenance of transport equipment, construction, and the need to replace existing floors and protective layers. Major drivers of demand include the US, although Canada and Mexico add value with industrial and infrastructural projects. High-performing formulations will continue to have a role among consumers who value chemical resistance, abrasion resistance, and increased service life.
In the region, the US accounts for about 78-82% of demand. Among applications are industrial flooring, bridges, warehouses, manufacturing facilities, energy infrastructure, and transport equipment. Environmental regulations are stimulating the use of water-borne and low-emission coatings, while fast cure technology reduces downtime of facilities. Mexico is adding industrial significance through its manufacturing activities, while Canada has continued to benefit from infrastructure and industrial refurbishments.
U.S. Epoxy Coatings Market
United States contributes about 78-82% of North American Epoxy Coatings Market demands and is projected to record CAGR of 4.0-4.5% between 2026 and 2034. Maintenance for industries, commercial flooring, transportation infrastructure, manufacturing operations, and energy assets contribute largely to demand generation. Consumers value durability, faster installation, and low emission coatings while choosing protective systems.
Company presence is well spread with leading companies like PPG Industries, Inc., Axalta Coating Systems Ltd., RPM International Inc., The Sherwin-Williams Company, among others being prominent in the manufacture of coatings. Application trends are inclined towards protective systems that offer high traffic floor protection, corrosion protection, chemical resistance, and quick return to service. Demand generation is also affected by the modernization of warehousing facilities, factories, data related infrastructure, and transportation infrastructure.
Europe Epoxy Coatings Market
The European region had a 20-24% share of the global demand in 2025 and is expected to register a CAGR of 3.5-4.1% between 2025 and 2034. The German Epoxy Coatings Market has been a prominent player due to industrial manufacturing and automobile industry operations whereas the UK market is benefiting from renovation works. The French region has demand driven through transportation, construction activities and industrial buildings. The Italian and Spanish regions contribute owing to renovation, manufacturing, logistics and infrastructure applications. Stringent regulations regarding emission control are helping improve formulations and waterborne coatings.
The German region will continue to remain strategically important because of its strong industrial base along with presence of auto, engineering, logistics and manufacturing industries. The demand is becoming more inclined towards protective coatings which can meet performance and environmental standards. The UK market is driven by refurbishment, transport infrastructures, warehouses and commercial structures. Emphasis on application efficiency and performance over life cycle makes UK market interesting. France, Italy and Spain markets provide diversified opportunities owing to infrastructure renewal, industrial flooring, construction refurbishment and maintenance activities.
APAC Epoxy Coatings Market
APAC is estimated to have captured a 45–49% share in 2025, with an anticipated growth rate of 4.0–4.6% during the period 2026-2034, emerging as the largest regional Epoxy Coatings Market. China is a prominent regional consumer due to manufacturing, infrastructure, logistics, and construction industries. Advanced manufacturing and transportation drive the demand in Japan and South Korea, whereas India is growing on account of infrastructure and industrial investments.
Australian contribution comes from infrastructure, facilities linked with mining, and industrial maintenance. The policies encouraging manufacturing, transport, urbanization, and infrastructure development in the region keep on generating demand for durable protective products. Increasing concerns about environment are driving preference for water-borne and powder technologies, whereas efficiency in applications remains a major factor for contractors.
Middle East & Africa Epoxy Coatings Market
The Middle East & Africa region is estimated to grow at a CAGR of 4.2–4.8% over 2026–2034, due to the ongoing development of infrastructure, energy, construction, and industrial sectors. Saudi Arabia is leading the regional demand through large infrastructure and diversification programs, while the UAE gains demand from the development of construction, logistics, commercial, and industrial sectors. South Africa plays its part by means of mining, manufacturing, transportation, and infrastructure maintenance.
High energy intensity and tough climatic conditions create the need for corrosion and chemical resistance, as well as high durability. The UAE and Saudi Arabia provide good prospects for protective floor coatings and industrial coatings, while South Africa provides demand from the maintenance-intensive industrial sector. Rest of MEA region demand is also project-based and is driven by infrastructure construction, water facilities, energy facilities, and commercial buildings.
Segmentation Analysis
Technology
Technology segment in the Epoxy Coatings Market is increasingly determined by environmental requirements, application conditions, curing characteristics, and lifecycle performance. The segment is expected to expand at a 4.3–4.9% CAGR during 2026–2034. Waterborne technologies benefit from lower emissions, solvent-borne products retain performance advantages in demanding applications, and powder-based systems gain relevance where efficient material utilization and solvent reduction are priorities.
- Waterborne: Waterborne systems are increasingly selected for applications requiring reduced solvent emissions and improved workplace conditions. Their relevance is expanding across construction and industrial environments as formulators improve curing, adhesion, and chemical resistance.
- Solvent Borne: Solvent-borne formulations remain important where penetration, substrate tolerance, application consistency, and established performance characteristics are prioritized, particularly across demanding industrial and transportation environments.
- Powder-Based: Powder-based systems provide high transfer efficiency and reduced solvent use, supporting adoption where manufacturers seek durable finishes, efficient production, and improved environmental performance across controlled application settings.
Application
Application segment in the Epoxy Coatings Market demand is projected to increase at a 4.2–4.8% CAGR during 2026–2034, supported by construction rehabilitation, transportation infrastructure, and industrial asset maintenance. Performance requirements vary significantly by substrate, exposure conditions, traffic intensity, and chemical environment, encouraging suppliers to develop application-specific systems and technical services.
- Construction: Construction represents the principal demand base because epoxy systems protect floors, concrete structures, commercial facilities, warehouses, and infrastructure from abrasion, chemicals, moisture, and heavy traffic.
- Transportation: Transportation applications require durable coatings for infrastructure and operating environments exposed to mechanical wear, weathering, chemicals, and repeated loading, supporting continued use across roads, facilities, and related assets.
- General Industrial: General industrial applications encompass factories, machinery areas, warehouses, processing facilities, and maintenance environments where resistance to chemicals, impact, abrasion, and operational wear is essential.
Opportunity Snapshot
| Application | Revenue Contribution | Trend Tag | Adoption Stage |
| Construction | High | Infrastructure Floors | Mature |
| Transportation | Medium | Asset Protection | Scaling |
| General Industrial | High | Factory Refurbishment | Mature |
Epoxy Coatings Market Growth Drivers and Impact Analysis
Infrastructure rehabilitation increases demand for durable protective systems
Aging infrastructure creates recurring requirements for coatings that can extend service life without requiring complete asset replacement. Bridges, parking structures, industrial floors, water facilities, warehouses, and transportation buildings increasingly require protective treatments against moisture, abrasion, chemicals, and mechanical stress. Epoxy systems are positioned to benefit because they can provide strong adhesion and durable surface protection across concrete and steel substrates. Rehabilitation projects also favor solutions that reduce maintenance frequency, particularly where shutdowns disrupt operations. The Epoxy Coatings Market impact extends beyond new construction because maintenance and refurbishment provide recurring demand throughout an asset’s operating life. Contractors and asset owners are therefore evaluating coating systems according to lifecycle economics, application productivity, and expected service intervals. This creates opportunities for suppliers offering specialized formulations, application guidance, and technical support rather than commodity products alone.
Environmental requirements accelerate formulation transition
Environmental regulation in the Epoxy Coatings Market is reshaping formulation priorities across mature coating markets. Restrictions on volatile organic compounds and increased attention to worker exposure encourage manufacturers to reduce solvent content while preserving application characteristics and coating performance. Waterborne technologies benefit from this transition, while powder-based systems provide another pathway for reducing solvent dependence in suitable controlled environments. The impact is particularly visible in Europe and increasingly relevant across North America and Asia Pacific, where customers are incorporating environmental criteria into procurement specifications. Formulators are consequently investing in resin chemistry, curing agents, additives, and application processes that deliver comparable durability with lower environmental burdens. This transition can increase development complexity because new formulations must satisfy performance, compatibility, curing, storage, and application requirements simultaneously. Suppliers with strong research capabilities and regional technical infrastructure are better positioned to commercialize compliant products efficiently.
Industrial modernization expands high-performance coating requirements
Industrial modernization is creating additional demand for coatings capable of operating under demanding mechanical and chemical conditions. New factories, logistics facilities, processing plants, energy infrastructure, and specialized manufacturing environments require floors and structural surfaces that withstand traffic, impact, chemicals, and cleaning regimes. Existing facilities also generate replacement demand as operators seek to improve productivity and reduce maintenance interruptions. Epoxy systems benefit from their established use across industrial floors and protective applications, while technology improvements are expanding suitability for specialized environments. Market impact is strongest where downtime carries substantial economic cost, making rapid curing and long service life important purchasing criteria. Suppliers can capture this demand through systems optimized for specific industries, application conditions, and substrates. Technical service is becoming increasingly important because surface preparation, coating thickness, curing conditions, and application quality can materially influence final performance.
Epoxy Coatings Market Future Trends
Low-emission chemistry becomes a mainstream specification criterion
Future formulation development in the Epoxy Coatings Market Trends is likely to focus increasingly on low-emission chemistry without sacrificing mechanical strength, adhesion, chemical resistance, or curing reliability. Waterborne systems should continue gaining relevance as environmental expectations become embedded in procurement decisions across construction, industrial, and infrastructure projects. Powder-based technologies may also expand where controlled application environments permit efficient curing and recovery of unused material. Product development will increasingly consider the complete application process, including substrate preparation, drying time, curing temperature, and worker exposure. Suppliers that reduce application complexity while maintaining performance can create measurable value for contractors and asset owners. Over time, environmental performance is expected to move from a compliance requirement toward a broader lifecycle purchasing criterion, particularly among multinational industrial users with standardized sustainability objectives across facilities.
Digital specification and application optimization reshape customer engagement
Digital tools are expected to become more influential in coating selection, specification, and application management. Customers increasingly require technical information that helps them compare coating performance against substrate conditions, exposure levels, operating temperatures, and maintenance schedules. Digital platforms can support product selection, project documentation, technical guidance, and customer interaction while reducing friction during procurement. Application technologies may also become more automated in controlled industrial environments, improving consistency and material utilization. These changes could favor suppliers capable of integrating formulation expertise with digital technical services. The trend is particularly relevant for complex industrial projects where incorrect coating selection can result in costly rework or premature failure. As customers increasingly evaluate total project outcomes rather than individual product characteristics, digital tools can become an important mechanism for demonstrating technical suitability and improving specification confidence.
Epoxy Coatings Market Opportunities
Specialized coatings for energy and infrastructure assets
Energy and infrastructure modernization presents an attractive opportunity for suppliers developing specialized epoxy systems for demanding operating environments. Offshore facilities, pipelines, renewable energy infrastructure, bridges, industrial plants, and transportation assets require coatings that resist corrosion, abrasion, chemicals, moisture, and mechanical stress. Suppliers can differentiate through high-build systems, rapid curing, long immersion resistance, and formulations compatible with complex maintenance schedules. The Epoxy Coatings Market Forecast is strongest where asset owners prioritize service-life extension and reduced shutdown frequency. Product development can also target specific environmental conditions, including high humidity, temperature variation, salt exposure, and chemical contact. Strategic expansion into these applications requires strong technical validation and specification support because project approvals often depend on performance standards and contractor confidence. Companies with established protective-coatings expertise can use specialized formulations to deepen relationships with infrastructure and energy customers.
Regional manufacturing expansion creates localized formulation opportunities
Manufacturing investment in Asia Pacific, the Middle East, and selected emerging markets creates opportunities for suppliers to establish localized production, distribution, and technical-service capabilities. Customers operating new factories often require coating systems tailored to local construction practices, substrate conditions, environmental regulations, and maintenance capabilities. Local manufacturing can improve supply reliability, shorten lead times, and reduce exposure to logistics disruptions while enabling closer relationships with contractors and industrial customers. The opportunity extends beyond product sales because specification assistance, surface preparation guidance, application training, and maintenance recommendations can influence purchasing decisions. Suppliers can also adapt established technologies to regional environmental requirements and industry priorities. As manufacturing clusters expand around automotive, electronics, logistics, energy, and general industrial activities, companies with flexible regional supply chains should be better positioned to capture recurring coating demand from both new facilities and subsequent maintenance cycles.
Recent Developments
- March 2026: PPG launched PPG SIGMASHIELD 950 and PPG SIGMASHIELD 899 GF, two glass-flake epoxy coatings designed for offshore energy, oil and gas, and infrastructure applications. SIGMASHIELD 950 is a solvent-free, high-build epoxy offering corrosion, water, abrasion, and impact resistance, while SIGMASHIELD 899 GF contains more than 20% glass flake and meets NORSOK M501:2022 and ISO 24656 requirements.
- March 2025: BASF and Sika jointly launched Baxxodur EC 151, a new epoxy hardener developed for more sustainable construction applications, particularly flooring. The solution enables ultra-low-VOC formulations, with selected systems demonstrating up to 90% lower VOC emissions than conventional hardeners. It also supports curing at temperatures of 5–10°C and can reduce curing time by up to two thirds.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for