
Aircraft Brake Calipers Market Trends, Demand & Growth by 2034
Coverage: By Product Type (Single Caliper Piston Type, Two Caliper Piston Type, Multiple Caliper Piston Type); Application (Business Aircraft, Commercial Aircraft, Defense Aircraft, Others); Aircraft Brake Type (Single Disc Brakes, Dual-Disc Brakes, Multiple-Disc Brakes, Segmented Rotor-Disc Brakes, Others); Sales Channel (Line Fit, Retro Fit) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00021921
- Category : Aerospace and Defense
- No. of Pages : 150
- Available Report Formats :


- Last update date : October 30, 2026


2025 Market Size
US$ 2.96 Bn
Base year value
2034 Forecast
US$ 4.11 Bn
Projected by 2034
CAGR 2026-2034
3.71 %
Growth rate
Addressable Market
US$ 32.10 Bn
(2026-2034)
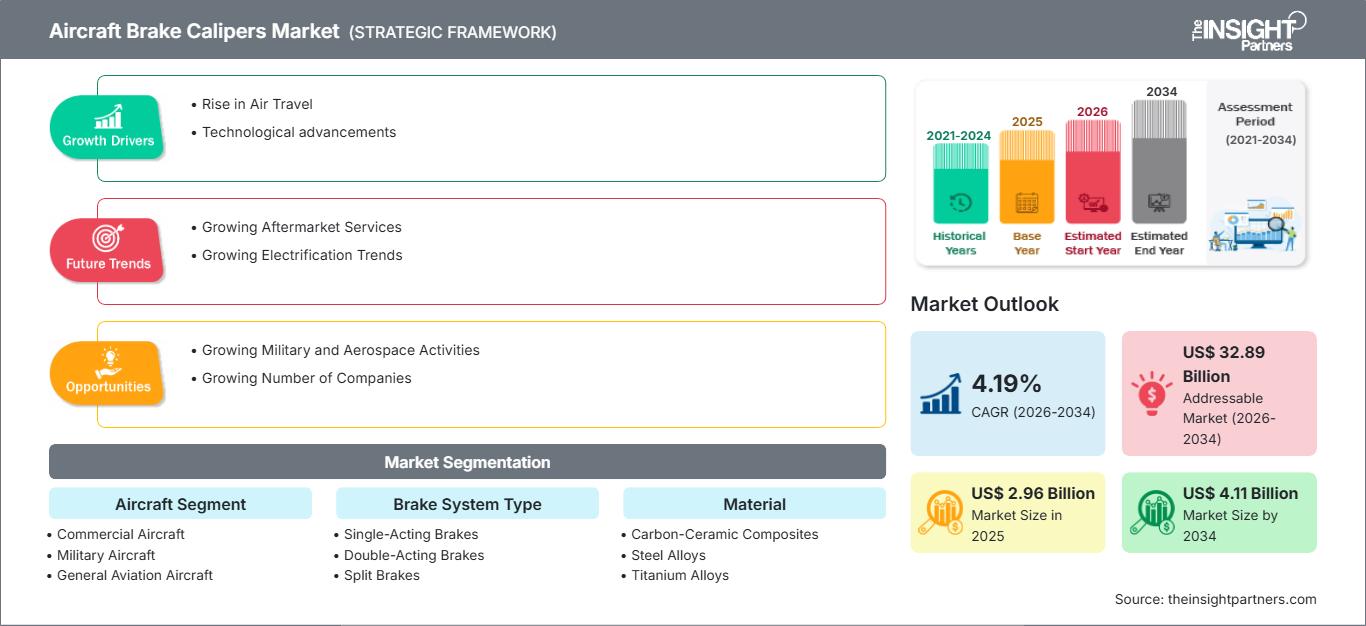
The Aircraft brake calipers market is a specialized aerospace component market covering braking assemblies that convert hydraulic or electromechanical actuation into clamping force at aircraft wheels. The market was valued at US$ 2.96 Billion in 2025 and is projected to reach US$ 4.11 Billion by 2034, registering a corrected CAGR of 3.71% during 2026–2034 based on the supplied market sizes. Demand is linked to aircraft deliveries, fleet utilization, replacement cycles, braking-system modernization, and requirements for reliable stopping performance.
North American demand is supported by a large installed aircraft base, extensive MRO infrastructure, and continued procurement of commercial, military, and general aviation platforms. The aircraft brake calipers market in the region is expected to expand at approximately ~4% CAGR through 2034, supported by replacement demand, retrofit programs, FAA-certified component availability, and investments in lightweight braking architectures. Increasing attention to maintenance turnaround and lifecycle cost also supports demand for durable caliper assemblies.
Aircraft Brake Calipers Market Assessment and Insights
Regional Outlook
- North America: ~34% of the global market in 2025 | ~4% CAGR through 2034. Market position: North America represents the largest regional market, supported by a substantial commercial and military aircraft installed base, mature MRO networks, established component certification infrastructure, and strong aftermarket demand for wheels, brakes, calipers, and related landing-system components.
- US: ~82% of North American market revenue in 2025 | ~4% CAGR through 2034. Market position: The US accounts for most North American demand because of its broad airline fleet, military aviation programs, business aviation activity, and extensive aftermarket ecosystem. FAA-approved replacement components and retrofit requirements sustain demand across operating aircraft.
- Europe: ~30% of the global market in 2025 | ~3% CAGR through 2034. Market position: Europe has a mature aircraft braking ecosystem centered on France, Germany, the UK, Italy, and Spain. France is the leading country in Europe, supported by major aerospace manufacturing, landing-system suppliers, airline fleets, and established MRO capabilities.
- Asia Pacific: ~24% of the global market in 2025 | ~5% CAGR through 2034. Market position: Asia Pacific is the fastest-growing region, driven by fleet expansion, rising air traffic, indigenous aerospace manufacturing, and MRO localization. China is the leading country in Asia Pacific, while India and Japan add demand through fleet expansion and aerospace industrial development.
Segment Outlook
- Aircraft Segment: ~67% Share in 2025 | ~4% CAGR through 2034. Market position: Aircraft Segment represents the largest main segment because commercial aviation generates substantial demand for brake components through high utilization, repeated landing cycles, scheduled overhaul, replacement requirements, and continuing deliveries of narrowbody and widebody aircraft.
- Material: ~31% Share in 2025 | ~5% CAGR through 2034. Market position: Material is the high-growth main segment as manufacturers increase the use of carbon-ceramic composites and advanced alloys to reduce weight, manage thermal loads, improve corrosion resistance, and extend component life without compromising braking performance.
Competitive Coverage
Parker Hannifin Corporation, Safran, Grove Aircraft Landing Gear Systems Inc., Collins Aerospace, Chief Aircraft Inc., Meggitt PLC, BERINGER AERO, Aircraft Spruce and Specialty Co., RAPCO, Inc., Altra Industrial Motion Corp.
Methodology
The Insight Partners follows Data Collection & Secondary Research, Primary Research, Data Analysis, and Data Triangulation & Final Review to validate market estimates and insights.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
Airplane braking systems have advanced from traditional metallic braking materials to those that are light, heat-absorbent, durable, and maintainable. Carbon braking material is becoming important in the aviation industry due to its ability to absorb heat energy during high-energy touchdowns. In modern landing systems, there is an increase in the integration of control and wheel speed sensors, anti-skid and system monitoring features. Collins Aerospace and Safran companies demonstrate this advancement through their products, such as integrated wheels, brakes, control and support throughout the life cycle. There are also other specialized suppliers who manufacture these products for general aviation and retrofits.
The forward outlook for Aircraft Brake Calipers Market share is shaped by aircraft production recovery, fleet replacement, defense modernization, and increasing MRO localization in emerging aviation markets. There is more development in the region of the Asia Pacific when it comes to the production and maintenance of aerospace products. There is also growing demand for advanced brake systems due to Middle Eastern airlines and other aviation programs. Airworthiness, traceability, fatigue resistance, thermal capabilities, and continued airworthiness remain the key barriers to market entry.
Aircraft Brake Calipers Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 2.96 Billion |
| Market Size by 2034 | US$ 4.11 Billion |
| Global CAGR (2026 - 2034) | 3.71% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Aircraft Brake Calipers Market Analysis
The aircraft brake calipers market growth is closely tied to aircraft utilization because braking assemblies experience repeated thermal and mechanical loads during landing and taxi operations. The demand for calipers follows the value chain involving material suppliers, forgings and machine shops, brake system manufacturers, aircraft OEMs, MRO companies, distributors, and users. The calipers should have dimensional stability, clamping strength, sealing capabilities, and anti-corrosion properties at very high temperatures and pressures. The replacement of calipers is especially crucial in light aircraft and aging commercial aircraft, which can be extended by installing certified retrofit kits without replacing the entire landing gear.
The Aircraft Brake Calipers Market forecast is influenced by supply dynamics involving precision machining, certified materials, testing capacity, and access to approved designs. Big suppliers can combine calipers with wheels, carbon/metallic brake friction materials, hydraulic systems, and maintenance, repair, and overhaul services to establish lifecycle contracts with airlines and airframers. Suppliers such as Grove Aircraft Landing Gear Systems Inc. and BERINGER AERO cater to smaller aircraft, while bigger aerospace suppliers have a presence in both commercial and military programs. The qualification criteria and long product development time frame restrict quick supplier replacement.
Key Aircraft Brake Calipers Market trends show that competitive positioning increasingly combines product performance with manufacturing responsiveness and aftermarket support. Safran operates across landing gear, wheels, brakes, and braking systems, while Collins Aerospace supplies integrated landing systems and wheel-and-brake solutions across commercial and military aircraft. Parker Hannifin has incorporated Meggitt’s aerospace braking capabilities into its broader aerospace portfolio, strengthening exposure to braking and related systems. Specialist distributors such as Aircraft Spruce and Specialty Co. and RAPCO, Inc. support replacement-component availability, while Altra Industrial Motion Corp. contributes broader motion-control capabilities.
Investment trends in the Aircraft Brake Calipers Market are also moving toward production automation, capacity expansion, and more-electric aircraft architectures. Collins Aerospace has described automation at its wheel-and-brake manufacturing operations, including machining cells and autonomous material movement, to shorten production lead times. Safran has expanded landing and braking manufacturing capacity in France and announced additional carbon-brake capacity investments. These actions indicate that competitive advantage increasingly depends on certified capacity, repeatable manufacturing, lifecycle support, and the ability to accommodate changing aircraft production rates.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Aircraft Brake Calipers Market: Strategic Insights
Regional Insights
North America Aircraft Brake Calipers Market
North America remains the largest regional market, with a ~4% CAGR through 2034. The US accounts for most regional demand because commercial airlines, military operators, business aviation fleets, and general aviation users create a diversified replacement base. Mature MRO infrastructure supports recurring requirements for caliper inspection, repair, overhaul, and replacement, while FAA certification pathways support deployment of approved aftermarket components.
Canada contributes through commercial aviation, regional aircraft, business aviation, and aerospace manufacturing activity. Regional suppliers benefit from proximity to aircraft operators and maintenance organizations, while major landing-system companies maintain extensive production and support capabilities across the continent. The aircraft brake calipers market also benefits from fleet modernization because newer aircraft increasingly require lightweight, high-temperature braking architectures. Defense procurement adds another demand layer, particularly for aircraft operating under high landing loads and demanding mission cycles.
U.S. Aircraft Brake Calipers Market
The US represents approximately ~82% of North American Aircraft Brake Calipers Market revenue in 2025 and is expected to expand at ~4% CAGR through 2034. The country's large airline fleet, military aircraft inventory, business aviation base, and general aviation population generate recurring demand for braking components. Commercial operators prioritize component reliability, turnaround time, and lifecycle cost, while military applications emphasize thermal performance, durability, and mission readiness.
The supplier ecosystem includes Collins Aerospace, Parker Hannifin Corporation, Safran, Grove Aircraft Landing Gear Systems Inc., Chief Aircraft Inc., RAPCO, Inc., Aircraft Spruce and Specialty Co., and other certified component specialists. Demand spans original equipment, replacement parts, overhaul programs, and retrofit kits. General aviation provides an important aftermarket channel because calipers, pads, discs, and associated hydraulic components can be replaced through approved conversion or maintenance programs.
Europe Aircraft Brake Calipers Market
Europe represented approximately ~30% of the global Aircraft Brake Calipers Market in 2025 and is expected to record a ~3% CAGR through 2034. France ranks first in the continent with the support of Safran's broad range of landing and braking operations and the country's aerospace manufacturing sector. Germany participates in terms of the manufacture of aircraft, engineering, MRO, and supply chains, while the United Kingdom still plays a role due to the aerospace engineering tradition and aircraft base in both commercial and military sectors.
Italy and Spain participate through the manufacture of aircraft, maintenance, defense programs, and airline fleets. European demands include issues of airworthiness, traceability, parts certification, environmental compliance, and continued airworthiness documents. There is also a development of advanced braking materials, such as carbon and corrosion-resistant metals. Production facility investments show that companies have planned capacities for increased aircraft manufacture and MRO needs. The situation provides continuous replacement demand despite the slow increase in the aircraft fleets compared to emerging aviation markets.
APAC Aircraft Brake Calipers Market
Asia Pacific held approximately ~24% of the global Aircraft Brake Calipers Market in 2025 and is forecast to expand at ~5% CAGR through 2034, making it the fastest-growing region. China leads the pack in the Asia Pacific region thanks to demand for commercial aircraft, aerospace industry development, and enhanced maintenance capacities. Japan and South Korea add value thanks to the aerospace industry manufacturing and military aviation programs.
India is building up its aviation manufacturing and maintenance infrastructure, whereas Australia is generating demand via commercial, military, and general aviation fleets. There is added value from industrial localization, airline fleet expansion, airport development, and government-sponsored aerospace industry programs for manufacturers of certified components. This is especially important in terms of MRO because increased utilization of aircraft means more demands on the replacement of braking systems.
Middle East & Africa Aircraft Brake Calipers Market
Middle East & Africa Aircraft Brake Calipers Market demand is expected to grow at approximately ~3% CAGR through 2034. Saudi Arabia is one of the prominent countries in the Middle East & Africa region due to fleet development, airport developments, and diversification in the aviation sector. The UAE also has a strong presence with respect to major airlines, MROs, airports, and aerospace services.
The South African country has been playing an important role via commercial, military, and general aviation activities, whereas other parts of the Middle East & Africa region are also connected with fleet upgrade, infrastructure development, and expansion in air connectivity. High-temperature operations lead to the importance of thermal management, sealing, corrosion protection, and regular maintenance. The new investments made by airlines and airports can create a need for brake components.
Segmentation Analysis
Aircraft Segment
The Aircraft Segment of the Aircraft Brake Calipers Market is the largest main segment, with a ~4% CAGR during 2026–2034. Commercial aircraft account for a substantial share of recurring brake-component demand because high utilization creates frequent landing cycles and predictable maintenance requirements. Military aircraft require robust systems capable of handling demanding operating conditions, while general aviation aircraft generate a fragmented but resilient aftermarket. The segment benefits from fleet growth, aircraft refurbishment, component replacement, and continued emphasis on braking reliability.
- Commercial Aircraft: Demand is concentrated around high-utilization fleets, where repeated landing cycles increase wear on braking assemblies. Airlines prioritize certified components that combine reliable stopping performance with lower maintenance burden and predictable overhaul intervals.
- Military Aircraft: Military platforms require braking systems capable of handling demanding loads, high-energy landings, and varied operating environments. Procurement is influenced by fleet modernization, sustainment programs, mission readiness, and long-term availability of certified replacement components.
- General Aviation Aircraft: General aviation creates a broad aftermarket for replacement calipers, brake assemblies, conversion kits, and associated hardware. Demand is influenced by aircraft age, owner maintenance requirements, retrofit activity, and availability of approved components.
Brake System Type
Brake System Type of the Aircraft Brake Calipers Market includes single-acting, double-acting, and split braking architectures and is expected to expand at approximately ~4% CAGR during 2026–2034. Selection depends on aircraft configuration, braking-force requirements, redundancy, hydraulic architecture, and application-specific certification. Replacement programs often retain the original system architecture unless an approved conversion offers maintenance or performance benefits.
- Single-Acting Brakes: Single-acting configurations remain relevant in aircraft where straightforward hydraulic actuation and relatively simple maintenance are preferred. They support general aviation and selected legacy platforms where component availability and ease of servicing influence replacement decisions.
- Double-Acting Brakes: Double-acting configurations provide braking force through actuation on both sides of the friction interface. They are suited to applications requiring greater control and consistent force distribution under higher operating loads.
- Split Brakes: Split braking architectures allow differentiated control across braking circuits or wheel assemblies. Their importance is linked to aircraft configuration, redundancy requirements, directional control, and integration with anti-skid or differential-braking functions.
Material
Material is the high-growth main segment of the Aircraft Brake Calipers Market and is projected to expand at ~5% CAGR during 2026–2034. Material selection affects mass, thermal performance, corrosion resistance, fatigue life, manufacturability, and lifecycle cost. Carbon-ceramic composites support weight and heat-management objectives, while steel and titanium alloys remain important where strength, durability, cost, or specific aircraft requirements favor metallic construction.
- Carbon-Ceramic Composites: Carbon-based braking materials are increasingly important in high-performance aircraft applications because of their heat-management capability and weight advantages. Their strategic relevance rises as airlines and airframers seek lower operating weight and longer component service intervals.
- Steel Alloys: Steel alloys remain important for applications where robustness, established certification pathways, energy absorption, and maintainability are priorities. Metallic braking systems continue to serve commercial and general aviation fleets where cost-effective lifecycle performance is required.
- Titanium Alloys: Titanium alloys support lightweight structural requirements where corrosion resistance and high strength-to-weight performance justify higher material costs. Their use is relevant to advanced aircraft systems seeking mass reduction while maintaining mechanical integrity.
Calipers Design
Calipers Design is expected to expand at approximately ~4% CAGR during 2026–2034. Design selection is influenced by packaging, wheel configuration, actuation method, serviceability, load distribution, and aircraft-specific installation constraints. Manufacturers continue to refine caliper geometry and materials to balance braking force, weight, thermal stability, and maintenance requirements.
- Floating Calipers: Floating designs accommodate movement relative to the brake disc and can provide compact configurations suited to selected aircraft applications. Their importance is associated with straightforward force distribution and packaging efficiency.
- Fixed Calipers: Fixed calipers provide rigid positioning around the disc and can support consistent clamping performance. They are relevant where structural stiffness, predictable actuation, and high braking-force requirements influence system architecture.
- Sliding Calipers: Sliding calipers allow controlled movement to maintain effective engagement with the braking surface. Their strategic value is linked to compact installation, serviceability, and application-specific requirements for aircraft wheels and braking assemblies.
Opportunity Snapshot
| Aircraft Segment | Revenue Contribution | Trend Tag | Adoption Stage |
|---|---|---|---|
| Commercial Aircraft | High | Fleet Renewal | Mature |
| Military Aircraft | Medium | Defense Sustainment | Scaling |
| General Aviation Aircraft | Low | Retrofit Kits | Scaling |
Aircraft Brake Calipers Market Growth Drivers and Impact Analysis
High Aircraft Utilization Increases Component Replacement Demand
Higher aircraft utilization directly increases the number of landing and braking cycles experienced by calipers and associated brake assemblies. Commercial aircraft operating frequent short- and medium-haul routes accumulate braking cycles faster than lower-utilization aircraft, increasing the importance of inspection, overhaul, and replacement planning. Military fleets similarly require dependable braking components during sustained operations and training cycles. For suppliers, the effect is a shift from purely delivery-driven demand toward recurring lifecycle revenue generated through spares and MRO channels. The aircraft brake calipers market therefore benefits from fleet utilization even when new-aircraft deliveries fluctuate. Operators also seek components that reduce downtime and maintenance complexity, encouraging suppliers to improve serviceability, component interchangeability, corrosion resistance, and wear characteristics.
Lightweight Braking Architectures Improve Aircraft Operating Economics
Lighter weight continues to be an ongoing design consideration for aerospace components, as there is always the possibility of saving on fuel burn through reduced weight. Brake calipers must be designed along with lighter wheels and high-performance friction material, among other integrated braking system considerations. There are carbon-containing materials that can be used to save weight in appropriate application scenarios, while titanium and advanced steels have been proposed where strength and resistance to corrosion is essential. Market impact includes not only the OEMs but also the certification and cost benefit of the retrofitted solution. Suppliers who design for lightness and thermal performance can meet the needs of both OEM and aftermarkets in a way that does not compromise the safety and certification of aircraft brakes.
Expansion of MRO Networks Strengthens Aftermarket Component Demand
An increase in the capacity of the MRO industry will ensure the ongoing demand for aircraft brake calipers since inspections, overhaul, repairs, and replacements will occur over the operating life of the aircraft. Airlines have started demanding regional maintenance service provision to ensure a reduction in aircraft downtime and ensure parts availability. Suppliers of the component react by creating a network of repair services, maintaining stocks of replacement assemblies, and providing documentation and technical data to distributors. Aftermarket opportunities for specialists dealing with old and general aviation aircraft exist due to the opportunity for extending the useful life of the aircraft through the use of replacement components. Localization of the MRO services in the Asia Pacific and Middle East region can reduce supply chains and make certified parts available.
Aircraft Brake Calipers Market Future Trends
Trend Toward More-Electric Braking and Integrated Health Monitoring
The aircraft brake calipers market is likely to become increasingly connected to electric actuation, electronic control, sensing, and aircraft health-management architectures. With more electric aircraft being developed, there is an increasing reduction of dependency on hydraulic systems in certain functionalities, thus making room for new electromechanical brake systems and electronic braking systems. This way, the sensors would be able to monitor brake temperature, wheel speed, brake wear, and operating conditions to facilitate condition-based maintenance. This means that there is a move from mechanical parts that have been individually designed to landing system architectures. There will need to be demonstrations of electromagnetic compatibility, redundancy, fault detection, and reliable performance under certification conditions.
Advanced Materials and Automated Manufacturing Reshape Component Design
Future calipers will involve the application of high-tech materials, composites, coatings, machining, and even production. The manufacturers can apply numerically controlled machining and inspection machines to achieve increased repeatability and minimize production choke points. Also, additive manufacturing can have an impact on specific supporting structures and tooling as long as certification and qualification allow the use of specific materials. Material development will continue involving the improvement of heat-resistance, fatigue resistance, corrosion protection, and lightweight. Automation in production will be able to help improve the reaction to changes in the schedule of aircraft production and in the aftermarket. With further certification, the combination of material and digital manufacturing technologies can help design component-specific calipers.
Aircraft Brake Calipers Market Opportunities
Localized MRO and Certified Aftermarket Supply in Asia Pacific
The Asia Pacific region represents an opportunity for suppliers that can set up certified after-market supply chains near growing aircraft fleets. There is a need for the airlines and MRO providers to have a reliable source of replacement parts for brakes, along with documentation, testing facilities, and fast delivery services. Near-site stocking and repair arrangements will help in minimizing ground time for the aircraft and procurement time. Different markets in India, China, Japan, South Korea, and Australia represent a variety of commercial, military, and general aviation applications that enable suppliers to cater to the right product mix for the fleets. There is also an opportunity for the suppliers through the approved repair stations to generate continuous demand for replacement calipers and related components.
Retrofit and Replacement Solutions for Aging General Aviation Fleets
Older aircraft in the general aviation fleet offer chances for suppliers with certified caliper conversion kits and braking system assemblies. Many aircraft from a certain period in history still need support, even if their parts are hard to obtain. There is a chance of supplying alternatives that would be easier to maintain without extensive changes to the airframe, based on the proper certification, such as STC, PMA, TSO, etc., and accompanying manuals. Light wheel and brake kits may become another chance for companies to enter into cooperation because of the search for higher-quality braking systems or a reduction in the frequency of maintenance procedures.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners provided valuable market intelligence that supported our global go-to-market strategy. Their team was professional, responsive, and attentive to our feedback, providing thoughtful analysis and helpful methodological clarifications throughout the project.
Junmo Kim Chief Financial Officer (CFO), Enertech Co., Ltd.
The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for