
Antibody Drug Conjugates Contract Manufacturing Market Growth, Trends & Forecast by 2034
Antibody Drug Conjugates Contract Manufacturing Market Size and Forecasts (2021 - 2034), Global and Regional Share, Trends, and Growth Opportunity Analysis Report Coverage : by Stage of Development (Phase I, Phase II, Phase III and Commercial); Process Component (Antibody, HPAPI / Cytotoxic Payload, Conjugation / Linker and Fill / Finish); Condition (Myeloma, Lymphoma, Breast Cancer); Linker (Cleavable Linker, Non-cleavable) ; and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00040055
- Category : Life Sciences
- No. of Pages : 150
- Available Report Formats :


- Last update date : August 26, 2026


2025 Market Size
US$ 11.46 Bn
Base year value
2034 Forecast
US$ 25.54 Bn
Projected by 2034
CAGR 2026-2034
9.31 %
Growth rate
Addressable Market
US$ 165.25 Bn
(2026-2034)
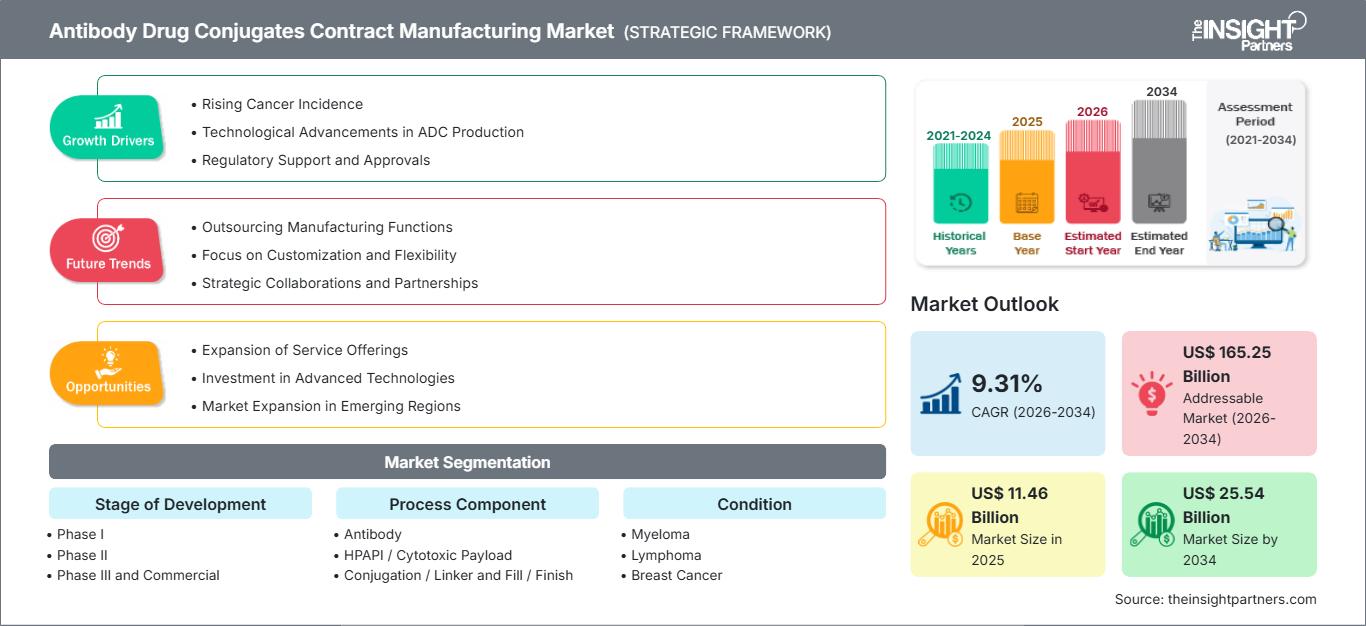
The antibody drug conjugates contract manufacturing market is projected to expand from US$ 11.46 Billion in 2025 to US$ 25.54 Billion by 2034, registering a CAGR of 9.31% during 2026–2034. The market is being shaped by increasing outsourcing of complex bioconjugation operations, rising clinical development activity, and growing demand for specialized manufacturing infrastructure capable of handling highly potent payloads, controlled conjugation processes, and sterile drug-product production.
North America remains a strategically important manufacturing hub, supported by a mature biopharmaceutical ecosystem, established CDMO infrastructure, and strong oncology investment. The antibody drug conjugates contract manufacturing size is expected to advance at approximately 9.0–9.6% CAGR through 2034, supported by outsourcing among emerging biotechnology companies and increasing demand for integrated antibody, payload, conjugation, and fill-finish capabilities.
Antibody Drug Conjugates Contract Manufacturing Market Assessment and Insights
- North America: North America held an estimated 40–44% share in 2025 and is projected to grow at a 9.0–9.6% CAGR between 2026–2034, supported by specialized high-potency facilities, biopharmaceutical outsourcing, and strong clinical-stage ADC pipelines.
- US: The US represented approximately 78–82% of North America's 2025 market and is expected to grow at 9.0–9.6% CAGR between 2026–2034, led by extensive CDMO capacity and oncology development.
- Europe: Europe accounted for approximately 25–29% share in 2025 and is projected to expand at 8.8–9.4% CAGR between 2026–2034, with Germany, Switzerland, the UK, France, and Italy supporting specialized biologics and high-potency manufacturing.
- Asia Pacific: Asia Pacific represented approximately 18–22% share in 2025 and is expected to register 10.0–10.7% CAGR between 2026–2034, with China, Japan, South Korea, India, and Australia strengthening biopharmaceutical manufacturing capabilities.
- Largest Segment: Commercial programs represented an estimated 45–50% market share in 2025 and are expected to grow at 8.7–9.2% CAGR through 2034 as approved ADC portfolios require reliable commercial-scale supply.
- High Growth Segment: Phase II programs represented approximately 16–20% market share in 2025 and are expected to expand at 10.2–10.8% CAGR as clinical pipelines transition toward pivotal development.
- Key companies analyzed in detail: AbbVie Inc., Eli Lilly and Company, Gilead Sciences, Inc., Merck KGaA, Boehringer Ingelheim, Recipharm AB, Lonza Group AG, Catalent, Inc., KBI Biopharma, Inc., ImmunoGen, Inc.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
As technological maturity occurs, the process of manufacturing ADCs will shift from specialized tasks to integrated models. Contract development and manufacturing organizations (CDMOs) are integrating antibody manufacturing, handling of highly potent APIs, chemistry of linker-payloads, conjugation, characterization, and fill-finish operations. Advancements in technologies of site-specific conjugation, process analytical technologies, containment facilities, and scalable purification will result in decreased variability and increased consistency between batches. These developments will increase the importance of providers with the ability to support several development phases.
The future of manufacturing capacity will expand beyond existing US and Europe-based locations. With investment in biologics infrastructure in Asia, the resilience of the supply chain in this region, and regulatory harmonization, more manufacturing capacity will become available. At the same time, the preference of developers is going to be on CDMOs offering flexibility in batch sizes, validated containment facilities, experience in worldwide regulation, and technology transfer.
Antibody Drug Conjugates Contract Manufacturing Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 11.46 Billion |
| Market Size by 2034 | US$ 25.54 Billion |
| Global CAGR (2026 - 2034) | 9.31% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Antibody Drug Conjugates Contract Manufacturing Market Analysis
Growth in the antibody drug conjugates contract manufacturing market is attributed to the increasing complexity associated with ADC manufacturing processes, as well as the lack of capital to invest in dedicated facilities. The value chain comprises of antibody manufacturing, payload manufacturing, linker manufacturing, conjugation, purification, analytics, formulation, and fill-finish. Developers may opt to outsource various steps of the process or even the whole program based on their capabilities, clinical stage, containment, and commercial scale.
The supply chain remains limited due to the fact that ADC manufacturing is a special process. Some payloads may need occupational exposure control, while the conjugation requires extra process development, which involves issues like drug-to-antibody ratio, purity, aggregation, and stability. An integrated CDMO can help to ease the technology transfer process by conducting several steps within one quality management system.
Based on the antibody drug conjugates contract manufacturing market report, the market is highly competitive, with diversified CDMOs that have a strong position in terms of biologics, small molecule, and high potency. Lonza Group AG has specialized in offering ADC integrated service that includes antibodies, linkers, payloads, bioconjugation, and fill-finish. Catalent, Inc. specializes in ADC services through SMARTag capability and development as well as manufacturing, and AbbVie Inc. offers infrastructure for ADC contract manufacturing. In addition, KBI Biopharma, Inc. offers advanced analytics and antibodies development.
Increasingly, strategic differentiation has been more focused on integration than specific manufacturing processes. Eli Lilly and Company, Gilead Sciences, Inc., Merck KGaA, Boehringer Ingelheim, Recipharm AB, and ImmunoGen, Inc. add their expertise in ADC contract manufacturing market through broad development, biologics, oncology, or conjugation. Increasing investment is towards containment, conjugation suite, analytics technology, and capacity flexibility, and hence capturing programs at all stages from clinical supply to commercial manufacturing.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Antibody Drug Conjugates Contract Manufacturing Market: Strategic Insights
Regional Insights
North America antibody drug conjugates contract manufacturing market
North America had antibody drug conjugates contract manufacturing market share of about 40%–44% in 2025 and is projected to grow at 9.0%–9.6% CAGR during 2034. North America is driven by a large presence of biotech firms, pharma sponsors, CDMOs, oncology centers, and regulatory experts. The USA continues to be the primary contributor whereas Canada complements it with its biologics development and manufacturing capability. Venture funding and licensing contribute to outsourcing.
North America also gains from high-potency capability and integrated bioconjugation technology. Sponsors are now looking for providers who can manage both antibody manufacturing and linker-payload manufacturing, conjugation and characterization and sterile manufacturing. The need for process control and containment also helps experienced companies. Well-established clinical trial setup in North America helps in fast transfer of projects into manufacturing.
U.S. antibody drug conjugates contract manufacturing market
The US accounted for roughly 78%-82% of the North American 2025 market share and is expected to have a growth rate of 9.0%-9.6% CAGR up until 2034. Such dominance is due to high oncology pipeline, advanced biotech ecosystem, established CDMO capacity, and outsourced manufacturing demands. Some examples of such organizations are AbbVie Inc., Catalent, Inc., Lonza Group AG, and KBI Biopharma, Inc.
Demand for the services is highly focused on oncology programs that have the need for highly potent payload processing and conjugation. Commercial manufacturing plays an ever more important role as approved ADC therapeutics begin having wider indications and launch into new geographies. At the same time, early-stage companies continue outsourcing their process development and clinical production due to significant investments needed for containment and analysis equipment.
Europe antibody drug conjugates contract manufacturing market
Europe comprised about 25% to 29% market share in 2025 and is projected to grow at 8.8% to 9.4% CAGR until 2034. Switzerland continues to be a key manufacturing destination due to its well-developed CDMO infrastructure and the region of Germany, the UK, France, Italy, and Spain complements the pharma and biotechnology capabilities.
The UK and Germany continue to have key importance in the field of biopharmaceutical development and manufacturing. Switzerland continues to play an important role for high potency and bioconjugation manufacturing due to well-developed facilities and global CDMO presence. France, Italy, and Spain continue to complement with pharma manufacturing, clinical studies, and developing biotechnology. The European sponsors have been increasingly looking for the suppliers which can offer development, analytical, conjugation and sterile manufacturing services within coordinated quality system.
APAC antibody drug conjugates contract manufacturing market
The APAC region was responsible for 18%-22% share in 2025 and forecast to grow at a 10.0%-10.7% CAGR till 2034. China will drive the regional growth, followed by Japan and South Korea. India and Australia will bolster their complementing manufacturing and research abilities.
Industrial policies, rising capacity for biologics production, and increased research in oncology are driving the investments in the region. China and South Korea have established advanced eco-systems for bio-conjugation, while India is known for cost-competitive development and manufacturing facilities. Japan is known for its pharmaceutical prowess, while Australia brings in research and clinical facilities.
Middle East & Africa antibody drug conjugates contract manufacturing market
Middle East & Africa is expected to grow at approximately 7.8–8.6% CAGR through 2034, supported by healthcare modernization and pharmaceutical localization. Saudi Arabia leads regional development, with the UAE and South Africa providing important healthcare, distribution, research, and manufacturing capabilities.
Saudi Arabia and UAE are working towards building their pharmaceutical capabilities as well as domestic manufacturing capabilities, while South Africa remains a center of healthcare and innovation. However, RoMEA still relies largely on imports of advanced pharmaceuticals and manufacturing capabilities. Availability of energy resources and industrial park developments can facilitate biologics investments in the future, although the lack of ADC manufacturing facilities will keep the region reliant on international CDMOs.
Segmentation Analysis
Stage of Development
Stage of Development segment in the antibody drug conjugates contract manufacturing market is projected to grow at 8.9–10.4% CAGR between 2026–2034. Manufacturing requirements evolve materially across development stages, moving from small-scale process experimentation toward validated commercial operations. Sponsors increasingly favor CDMOs that can preserve process knowledge and analytical comparability as programs advance.
- Phase I: Early clinical programs emphasize rapid material availability, flexible batch sizes, analytical characterization, and efficient process development while sponsors evaluate safety, dose escalation, and initial pharmacological activity.
- Phase II: Programs require stronger process control, reproducibility, and scalable manufacturing as patient enrollment expands and developers optimize dose, formulation, conjugation parameters, and supply planning.
- Phase III: Pivotal programs demand robust validation strategies, larger production campaigns, regulatory documentation, and consistent commercial-readiness standards to support submissions and launch preparation.
- Commercial: Commercial programs prioritize validated processes, reliable capacity, supply continuity, quality systems, and long-term manufacturing economics across multiple markets and production cycles.
Process Component
Process Component segment in the antibody drug conjugates contract manufacturing market is expected to register 9.1–9.8% CAGR from 2026–2034. Complexity across the manufacturing chain creates opportunities for specialized and integrated suppliers. The antibody drug conjugates contract manufacturing scope increasingly extends beyond conjugation into coordinated sourcing, processing, characterization, and final drug-product manufacture.
- Antibody: Antibody production establishes the biological targeting component and requires consistent expression, purification, characterization, and control of critical quality attributes before conjugation.
- HPAPI / Cytotoxic Payload: Highly potent payload manufacturing requires strict containment, specialized equipment, occupational controls, and analytical capabilities because small quantities can present significant handling risks.
- Conjugation / Linker: Conjugation determines payload attachment, drug-to-antibody ratio, stability, and release characteristics, making process control and analytical characterization central to product quality.
- Fill / Finish: Sterile fill-finish requires specialized containment, aseptic processing, formulation control, and packaging capabilities suitable for highly potent drug products and commercial supply.
Condition
Condition segment in the antibody drug conjugates contract manufacturing market is forecast to expand at 9.0–9.7% CAGR during 2026–2034. Oncology remains the dominant therapeutic setting because ADCs are particularly suited to targeted delivery of potent payloads. Manufacturing demand follows clinical activity, commercial adoption, and expansion of ADC programs into additional cancer types.
- Myeloma: ADC development in myeloma creates demand for targeted manufacturing programs combining established antibody platforms with potent payload technologies and controlled conjugation processes.
- Lymphoma: Lymphoma remains an important ADC application because validated surface targets and established oncology treatment pathways support continued development and manufacturing requirements.
- Breast Cancer: Breast cancer represents a major manufacturing opportunity due to extensive HER2-directed ADC development, expanding patient populations, and continued exploration of earlier treatment settings.
Linker
Linker segment in the antibody drug conjugates contract manufacturing market is projected to grow at 9.3–10.0% CAGR between 2026–2034. Linker selection increasingly influences stability, intracellular release, therapeutic index, and manufacturability. CDMOs with differentiated conjugation chemistry and analytical expertise can support developers seeking optimized payload delivery.
- Cleavable Linker: Cleavable linkers enable payload release under defined biological conditions and remain strategically important for optimizing intracellular activity, bystander effects, and therapeutic performance.
- Non-cleavable: Non-cleavable linkers provide strong plasma stability and rely on intracellular degradation pathways for payload release, supporting applications where controlled systemic exposure is important.
Opportunity Snapshot
| Condition | Revenue Contribution (High/Medium/Low) | Trend Tag | Adoption Stage |
|---|---|---|---|
| Myeloma | Medium | Target Expansion | Scaling |
| Lymphoma | High | CD30 Targeting | Mature |
| Breast Cancer | High | HER2 Targeting | Mature |
Antibody Drug Conjugates Contract Manufacturing Market Growth Drivers and Impact Analysis
Rising Outsourcing of High-Potency Manufacturing
ADC developers increasingly outsource manufacturing because high-potency payloads require containment systems, specialized engineering controls, dedicated procedures, and experienced personnel. Establishing equivalent internal infrastructure can create substantial fixed costs before a candidate reaches proof of concept. This dynamic is particularly important for smaller biotechnology companies that need clinical material without building dedicated facilities. CDMOs can spread infrastructure utilization across multiple programs, improving economic flexibility for sponsors. The market impact is strongest in HPAPI handling, conjugation, analytical development, and sterile fill-finish. As more programs advance into pivotal trials, outsourcing can also reduce manufacturing bottlenecks by providing access to validated equipment and experienced technical teams. This supports longer customer relationships and increases opportunities for integrated service contracts.
Increasing Complexity of ADC Molecules
Next-generation ADCs increasingly incorporate differentiated antibodies, sophisticated linker chemistries, novel payloads, site-specific conjugation, and alternative drug-to-antibody ratios. Such complexity expands manufacturing requirements beyond conventional monoclonal antibody production. Process developers must evaluate conjugation efficiency, aggregation, payload distribution, residual impurities, stability, and release specifications simultaneously. Consequently, sponsors increasingly assess CDMOs according to their ability to connect development, analytical characterization, process optimization, and GMP execution. The impact extends across the value chain because changes in linker or payload chemistry can affect purification, formulation, fill-finish, and analytical methods. Suppliers with multidisciplinary capabilities therefore gain an advantage when developers seek to minimize technology-transfer events. This driver should particularly benefit integrated providers serving programs transitioning from laboratory-scale development into larger clinical batches.
Expansion of ADC Clinical and Commercial Pipelines
Growing investment in oncology pipelines is increasing the number of ADC programs requiring external manufacturing support across different development stages. Developers increasingly evaluate multiple targets, payload classes, linker architectures, and combination strategies, creating demand for flexible manufacturing rather than standardized production alone. Each successful clinical transition can generate incremental requirements for process characterization, scale-up, validation, and commercial supply. The effect is amplified because manufacturing decisions made during early development can influence later comparability and regulatory submissions. CDMOs that establish continuity from Phase I through commercial production can therefore capture greater lifetime value from individual programs. For sponsors, outsourcing also provides access to specialized capabilities while preserving internal resources for discovery and clinical development. This dynamic should strengthen demand for scalable, integrated manufacturing partnerships.
Antibody Drug Conjugates Contract Manufacturing Market Future Trends
Shift Toward Integrated and Platform-Based Manufacturing
The antibody drug conjugates contract manufacturing market trends are likely to increasingly favor platform-based manufacturing models that connect antibody production, payload synthesis, linker chemistry, conjugation, analytics, and fill-finish. Developers will seek standardized process frameworks that can be adapted to different molecules without sacrificing product-specific control. Digital process monitoring and enhanced characterization should support faster comparability assessments during technology transfer. CDMOs may also develop modular suites capable of handling several payload classes while maintaining stringent containment. This approach can improve facility utilization and reduce the time required to establish manufacturing readiness for new programs. Over time, platform capabilities should become a stronger purchasing criterion alongside individual technical expertise, particularly for sponsors managing multiple ADC candidates across different targets and clinical stages.
Greater Adoption of Site-Specific and Dual-Payload Approaches
Future manufacturing demand will increasingly reflect ADC designs that seek improved homogeneity, therapeutic index, and resistance management. Site-specific conjugation can create more controlled drug-to-antibody ratios and reduce product heterogeneity compared with less controlled approaches. Dual-payload concepts may further expand analytical and process requirements because manufacturers must demonstrate consistent incorporation of multiple active components. These approaches will increase the importance of advanced mass spectrometry, chromatography, impurity profiling, and process characterization. CDMOs that establish validated analytical workflows early may reduce development delays and support regulatory documentation more efficiently. The antibody drug conjugates contract manufacturing market is therefore likely to move toward manufacturing models where analytical development is integrated closely with process engineering rather than treated as a downstream testing activity.
Antibody Drug Conjugates Contract Manufacturing Market Opportunities
Expansion of Integrated ADC Manufacturing Hubs in Asia
Asia offers an opportunity to develop specialized ADC manufacturing hubs serving both domestic and international biotechnology companies. China, South Korea, Japan, and India already possess substantial pharmaceutical manufacturing capabilities, but specialized containment, conjugation, and integrated fill-finish capacity remains more concentrated. Investment in dedicated facilities could provide cost-efficient alternatives for selected development programs while strengthening regional supply resilience. Local CDMOs can differentiate through faster technology transfer, regional regulatory expertise, and flexible clinical-scale production. Partnerships with global sponsors could accelerate capability development without requiring every supplier to establish a complete end-to-end platform immediately. antibody drug conjugates contract manufacturing The antibody drug conjugates contract manufacturing market forecast should therefore account for gradual regional capacity expansion, particularly where governments are encouraging biopharmaceutical localization and advanced manufacturing investment.
Long-Term Capacity Partnerships With Emerging Biotech Sponsors
Emerging biotechnology companies represent an attractive customer group because many lack internal infrastructure for high-potency manufacturing and specialized conjugation. CDMOs can capture this opportunity through staged agreements that begin with development and analytical services before progressing into GMP clinical supply and commercial manufacturing. Such arrangements provide sponsors with technical continuity while giving CDMOs better visibility into future capacity requirements. Suppliers can further differentiate through flexible minimum batch sizes, rapid technical assessment, and integrated regulatory support. Strategic capacity reservations may become increasingly valuable as several ADC programs compete for specialized manufacturing slots. Providers that establish relationships before pivotal development can improve customer retention and potentially secure multi-year supply commitments when programs reach commercialization.
Recent Developments
- June 2026: Lonza Group AG and InduPro announced a licensing agreement covering Lonza’s GlycoConnect, HydraSpace, and linker-payload technologies. The agreement supports development of ADCs targeting up to two oncology antigens and expands access to Lonza’s bioconjugation technology platform for next-generation targeted therapies.
- November 2025: Catalent, Inc. presented new SMARTag ADC pipeline data and introduced SMARTag Enhanced Conjugates, combining different payload types on a single antibody. The company highlighted preclinical work involving a MUC1-targeting ADC and expanded its technology offering for differentiated conjugate development.
- September 2025: KBI Biopharma, Inc. announced a collaboration with Infinimmune to support manufacturing of the biotechnology company's lead human monoclonal antibody program. The agreement reinforces KBI's integrated antibody development and manufacturing capabilities relevant to complex biologics and future conjugated therapeutics.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for