
Gallium Nitride Semiconductor Device Market Trends, Share & Demand by 2034
Coverage: by Wafer Size (2 Inch, 4 Inch, and 6-Inch and Above); Device Type (GaN Radio Frequency Devices, Opto-semiconductors, and Power Semiconductors); and End User (Automotive, Consumer Electronics, Healthcare, Aerospace & Defense, Information & Communication Technology, and Industrial), and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00002943
- Category : Electronics and Semiconductor
- No. of Pages : 150
- Available Report Formats :


- Last update date : August 18, 2026


2025 Market Size
US$ 2.72 Bn
Base year value
2034 Forecast
US$ 13.13 Bn
Projected by 2034
CAGR 2026-2034
19.14 %
Growth rate
Addressable Market
US$ 64.95 Bn
(2026-2034)
The Gallium Nitride Semiconductor Device Market was valued at US$ 2.72 Billion in 2025 and is projected to reach US$ 13.13 Billion by 2034, registering a compound annual growth rate (CAGR) of 19.14% during the forecast period from 2026 to 2034. Gallium nitride (GaN) semiconductor devices are wide-bandgap materials that offer superior power density, switching frequency, and thermal tolerance compared to traditional silicon, enabling applications ranging from RF amplifiers and power supplies to electric vehicle onboard chargers and 5G infrastructure.
The Gallium Nitride Semiconductor Device Market Size in North America is estimated to grow at a CAGR of 16.2% to 16.6% during the forecast period, driven by substantial investments in 5G infrastructure deployment and defense electronics modernization. The region benefits from strong government support through initiatives such as the US CHIPS Act, which has accelerated domestic GaN manufacturing capacity expansion and reduced reliance on Asian supply chains.
Gallium Nitride Semiconductor Device Market Assessment and Insights
- North America: Accounts for approximately 27% to 31% of the global Gallium Nitride Semiconductor Device Market share in 2025, growing at a CAGR of 16.2%–16.6% from 2026 to 2034. The market is driven by defense electronics production surges and 5G network infrastructure investments across the region.
- US: Holds a dominant position within North America with a market share of 85%–90% in 2025, growing at a CAGR of 16.4%–16.8% during the forecast period, supported by the CHIPS Act funding allocation and significant defense electronics procurement.
- Europe: Accounts for 19%–23% of the global market share in 2025, growing at a CAGR of 15.8%–16.2% from 2026 to 2034. Leading countries include Germany, the UK, and France, with significant contributions from the automotive and industrial manufacturing sectors.
- Asia Pacific: Represents the largest regional market with a share of 35%–39% in 2025, growing at a robust CAGR of 18.5%–18.9% during 2026–2034. China, Japan, South Korea, and India are key contributors, driven by extensive consumer electronics manufacturing and telecommunications infrastructure expansion.
- Largest Segment: The Power Semiconductors device type segment dominates the market with a share of 40%–44% in 2025, growing at a CAGR of 17.0%–17.4% during 2026–2034, owing to widespread adoption in electric vehicles, data centers, and industrial power supplies.
- High Growth Segment: The GaN Radio Frequency Devices segment exhibits the highest growth potential, with a CAGR of 18.2%–18.6% from 2026 to 2034, driven by increasing demand for 5G infrastructure, radar systems, and defense communications applications.
- Key companies analyzed in detail: Efficient Power Conversion Corporation, Inc., Fujitsu Ltd., GaN Systems, Inc., Infineon Technologies AG, Microsemi Corporation, NXP Semiconductor N.V., Qorvo, Inc., Samsung Electronics Co. Ltd., Texas Instruments, Inc., Toshiba Corporation.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The Gallium Nitride Semiconductor Device Market development can be associated with revolutionary changes in terms of moving from conventional silicon power electronics solutions towards wider band-gap products that provide increased performance along with reduced size and higher temperature resistance capabilities. The production processes are becoming more advanced through implementation of larger wafers (for example, 6-inch and 8-inch).
The future trends for the Market include high growth prospects due to new areas of application of GaN products such as electric vehicles power electronics, wireless charging solutions, LiDAR technologies, data centers power supplies that allow achieving increased efficiency in comparison to silicon-based solutions. Increasing adoption of GaN technology within 5G network infrastructure with drain efficiency of about 60% in comparison to lower than 50% for LDMOS allows defining this product as an essential solution for further development of telecom networks.
Gallium Nitride Semiconductor Device Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 2.72 Billion |
| Market Size by 2034 | US$ 13.13 Billion |
| Global CAGR (2026 - 2034) | 19.14% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Gallium Nitride Semiconductor Device Market Analysis
The GaN Semiconductor Device Market essentially stems from strong demand from end-users like automotive, consumer electronics, information and communication technology, and aerospace & defense industries. The increasing use of electric vehicles has led to high demand for GaN semiconductor power devices that are employed in applications such as onboard chargers, DC-DC converters, and traction inverters, thanks to GaN’s excellent switching properties that facilitate greater efficiency and smaller systems. In the value chain analysis, there is a high level of interlinkage between suppliers of raw materials, epitaxial wafers, and fabricators of GaN semiconductors, with gallium metal being mostly supplied by China, which meets more than 80% of the world's needs for this metal, and epitaxial wafer manufacturing being done in Taiwan, South Korea, and Germany.
The Gallium Nitride Semiconductor Device Market Report competition structure comprises both existing semiconductor giants and GaN technology specialists, with companies like Infineon Technologies, Qorvo, Texas Instruments, and Samsung Electronics having broad portfolios encompassing all types of products ranging from power devices to RF components and opto-semiconductors. Some other firms like Efficient Power Conversion Corporation and GaN Systems are focusing on developing products for specific applications, such as electric vehicle power electronics, data center power supplies, and 5G applications. Competitiveness in the market largely depends on reliability of products, production capabilities, and provision of integrated solutions of GaN devices and driver ICs.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
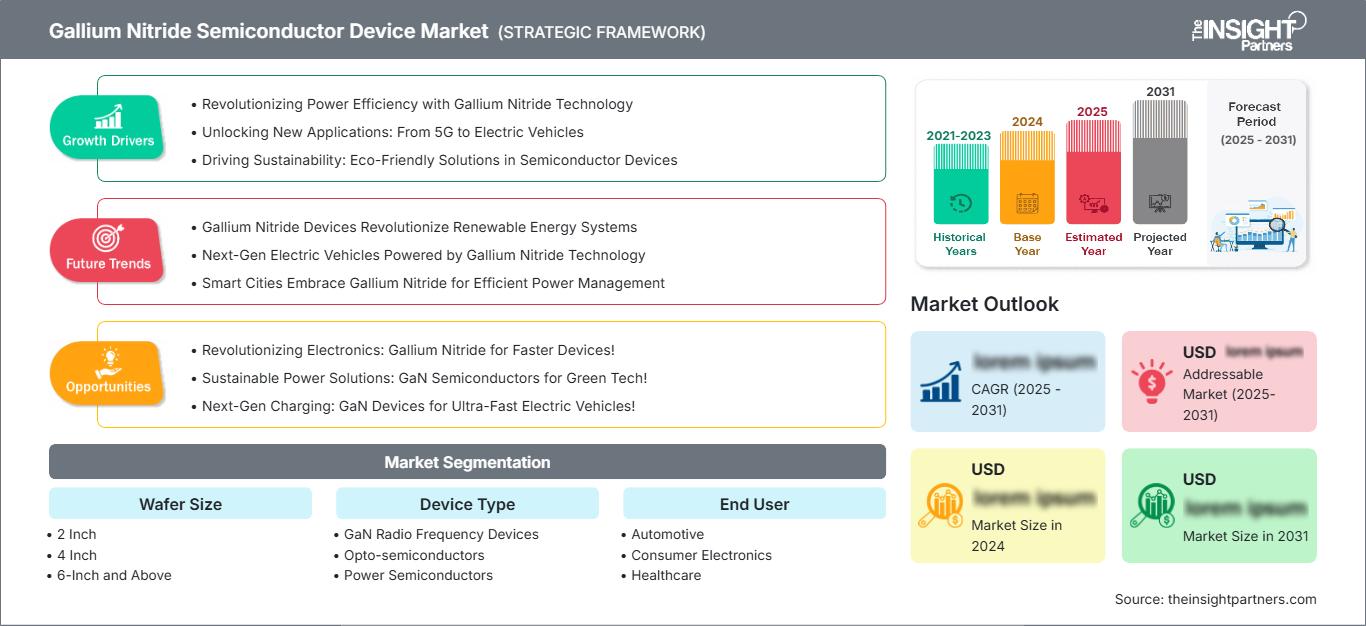
Gallium Nitride Semiconductor Device Market: Strategic Insights
Regional Insights
North America Gallium Nitride Semiconductor Device Market
The North America GaN Semiconductor Device Market holds a prominent market share of about 27%–31% in the market valuation on a global level in 2025, expanding at a CAGR of 16.2%–16.6% up until 2034. The growth in the market is highly impacted by the development of the semiconductor market in the region, wherein the US CHIPS Act provides US$ 39 billion towards semiconductor manufacturing in the country, including wide-bandgap devices which have led to rapid expansion in the production of GaN devices.
U.S. Gallium Nitride Semiconductor Device Market
The United States Gallium Nitride Semiconductor Devices Market is a leading market in terms of country-level market, having an 85%–90% market share in North America in 2025, with a CAGR of 16.4%–16.8%. The vast defense electronics industry and semiconductor fabrication ability along with research facilities will fuel the demand for GaN semiconductor devices for applications such as radars, 5G networks, electric vehicles, and data centers. Leading companies like Texas Instruments, Qorvo, and Efficient Power Conversion Corporation have strong presence in the U.S., thus contributing to innovation and growth in the region.
Europe Gallium Nitride Semiconductor Device Market
The Europe holds a market share of 19% to 23% of the global market share in 2025, which will increase at a CAGR of 15.8% to 16.2% between 2026 and 2034. Germany, UK, France, Italy, and Spain are the major players driving regional demand. Germany has a strong automotive manufacturing industry and industrial automation, making the country witness huge demand for GaN power devices owing to its usage in electric vehicles, industrial motor drives, and power supplies. In the case of the UK, it focuses on aerospace, defense, and research applications, which helps the country drive growth by way of value-added semiconductor and GaN RF device applications.
APAC Gallium Nitride Semiconductor Device Market
The APAC Gallium Nitride Semiconductor Devices Market is the leading regional segment, representing about 35% to 39% of the total global market share in 2025, with China, Japan, South Korea, India, and Australia among the main contributors. The market is expected to grow at a CAGR of 18.5% to 18.9% over the forecast period owing to a large consumer electronics production industry, expansion of telecommunications networks, and production of electric vehicles. China is the leading regional player in terms of demand due to its leadership in refining gallium metal (over 80% of the world's production) and its strong electronics production industries and electric vehicles. Policy initiatives aimed at fostering domestic innovation and self-reliance in semiconductor technology are defining the Gallium Nitride Semiconductor Devices Market dynamics in the APAC region.
Middle East & Africa Gallium Nitride Semiconductor Device Market
Middle East and Africa Gallium Nitride Semiconductor Devices Market presents an emerging market region of increasing relevance owing to the influence of geopolitical factors on the supply chain of gallium nitride in the international market as well as the regional initiatives for industrial diversification. Saudi Arabia and United Arab Emirates are the major countries in terms of market with considerable investments in industrial diversification projects and technological innovation projects including research in semiconductors. The conflict in the Middle East has affected the supply chain of gallium nitride through its sea route and Sanctions.

Segmentation Analysis
Wafer Size
The Wafer Size segment encompasses 2 Inch, 4 Inch, and 6-Inch and Above. This segment is expected to register a CAGR of 18.0%–18.4% from 2026 to 2034. The evolution toward larger wafer sizes reflects the semiconductor industry's continuous drive for manufacturing efficiency and cost reduction, with larger diameter wafers enabling more devices per wafer and improved economies of scale. The transition from 2-inch to 4-inch and increasingly 6-inch platforms represents a significant trend in GaN manufacturing.
- 2 Inch: Holds a modest market share as of 2025, primarily utilized in research and development environments and specialized, low-volume applications where extreme performance requirements justify higher production costs. This size is commonly used for early-stage device prototyping.
- 4 Inch: Represents a significant manufacturing platform, widely used for GaN devices requiring high-performance epitaxial layers. 4-inch wafers offer a balance between production efficiency and manufacturability for RF and power applications.
- 6-Inch and Above: The fastest-growing wafer size category with a CAGR of 18.5%–18.9%, driven by the industry's shift toward larger-diameter platforms to reduce unit costs and improve production scalability. 6-inch GaN-on-silicon wafers are increasingly adopted for power electronics applications where cost competitiveness with silicon is critical.
Device Type
The Device Type segment comprises GaN Radio Frequency Devices, Opto-semiconductors, and Power Semiconductors. The segment is projected to grow at a CAGR of 17.5%–17.9% from 2026 to 2034. The diverse device types address distinct market requirements, with RF devices targeting telecommunications and defense, power semiconductors serving automotive and industrial applications, and opto-semiconductors covering lighting and display technologies.
- GaN Radio Frequency Devices: The fastest-growing device type with a CAGR of 18.2%–18.6%, driven by increasing demand for 5G infrastructure, radar systems, and defense communications. GaN RF devices offer superior power density and efficiency compared to traditional LDMOS devices, with drain efficiency of approximately 60% compared to less than 50% for silicon alternatives.
- Opto-semiconductors: Hold a significant market share as of 2025, utilized in LED lighting, display technologies, and laser applications where GaN's wide-bandgap properties enable high-brightness and efficient light emission. This segment benefits from continued adoption of GaN-based lighting solutions.
- Power Semiconductors: The largest device type with 40%–44% market share in 2025, widely adopted in electric vehicle onboard chargers, DC-DC converters, data center power supplies, and industrial power conversion applications. GaN power semiconductors deliver superior efficiency and reduced system size compared to silicon alternatives.
End User
The End User segment includes Automotive, Consumer Electronics, Healthcare, Aerospace and Defense, Information and Communication Technology, and Industrial. This segment is projected to grow at a CAGR of 17.8%–18.2% from 2026 to 2034. The automotive and ICT sectors represent the largest end-user segments, driven by electric vehicle adoption and 5G infrastructure deployment, while aerospace and defense applications benefit from modernization programs and geopolitical tensions.
- Automotive: A key end-user segment utilizing GaN devices for electric vehicle power electronics, onboard chargers, and DC-DC converters. The segment is driven by the transition from silicon to wide-bandgap semiconductors for efficiency gains.
- Consumer Electronics: Represents a significant end-user segment for GaN devices in fast chargers, adapters, and power supplies where GaN's higher efficiency and smaller footprint enable compact, high-power solutions for smartphones and laptops.
- Healthcare: Utilizes GaN devices in medical imaging, diagnostic equipment, and therapeutic devices requiring high-performance power electronics. The segment benefits from the reliability and efficiency of GaN technology.
- Aerospace and Defense: The fastest-growing end-user segment with a CAGR of 18.5%–18.9%, driven by defense electronics modernization, radar systems, and secure communications applications. Geopolitical tensions and defense budget increases have accelerated adoption.
- Information and Communication Technology: A major end-user segment encompassing 5G infrastructure, data centers, and telecommunications equipment requiring GaN RF devices for high-frequency, high-power applications. The segment is driven by network modernization programs.
- Industrial: Encompasses motor drives, power supplies, and automation equipment where GaN devices offer energy efficiency improvements and reduced system size. Industrial energy efficiency regulations continue to drive adoption.
Opportunity Snapshot
| Device Type Segment | Revenue Contribution | Trend Tag | Adoption Stage |
|---|---|---|---|
| GaN Radio Frequency Devices | High | 5G Deployment | Scaling |
| Opto-semiconductors | Medium | LED Lighting | Mature |
| Power Semiconductors | High | EV Powertrain | Scaling |
Gallium Nitride Semiconductor Device Market Growth Drivers and Impact Analysis
Electric Vehicle Adoption and Powertrain Electrification
The accelerating adoption of electric vehicles and powertrain electrification is a primary driver for the Market, as automakers increasingly deploy GaN power devices in onboard chargers, DC-DC converters, and traction inverters. The International Energy Agency reported nearly 14 million electric cars sold worldwide in 2023, creating substantial demand for power electronics that can deliver higher efficiency and reduced system size compared to silicon-based alternatives. The market impact is evident in the growing integration of GaN devices in EV applications, where superior switching characteristics enable faster charging, extended range, and reduced thermal management requirements. Major power semiconductor manufacturers are expanding their GaN portfolios with devices specifically designed to meet the rigorous reliability and safety requirements of automotive applications, including compliance with AEC-Q101 automotive qualification standards.
5G Infrastructure Deployment and RF Power Requirements
The global deployment of 5G telecommunications infrastructure is a significant driver for the Gallium Nitride Semiconductor Device Market, as GaN RF devices offer superior performance characteristics for high-frequency, high-power applications required in next-generation networks. 5G infrastructure demands amplifiers and transmitters that operate at higher frequencies with greater efficiency than previous-generation technologies, with GaN devices delivering drain efficiency of approximately 60% compared to less than 50% for traditional LDMOS solutions. Telecommunications service providers are actively pursuing the increased use of GaN in network infrastructure, with major equipment vendors and operators incorporating GaN devices to address the capacity, latency, and traffic density requirements of 5G networks.
Data Center Power Efficiency and Sustainability Requirements
The growing emphasis on data center power efficiency and sustainability is driving demand for Gallium Nitride Semiconductor Device Market solutions, as hyperscale data center operators seek to reduce energy consumption and carbon footprint through advanced power conversion technologies. GaN power devices offer superior efficiency in server power supplies, point-of-load converters, and power distribution systems, enabling data centers to reduce energy losses and improve overall power usage effectiveness (PUE) metrics. Major data center operators are specifying GaN solutions to achieve sustainability targets and reduce operating costs, creating sustained demand for high-performance GaN power devices designed for continuous, reliable operation in enterprise and cloud computing environments.
Gallium Nitride Semiconductor Device Market Future Trends
Geopolitical Supply Chain Diversification and Regionalization
Geopolitical tensions and supply chain vulnerabilities are driving a significant trend toward supply chain diversification and regionalization in the Gallium Nitride Semiconductor Device Market Trends, as manufacturers and end-users seek to reduce dependence on single-source suppliers and concentrate of production capacity. The Middle East conflict and China's gallium export controls have exposed the fragility of global GaN supply chains, accelerating regional manufacturing initiatives in North America, Europe, and Southeast Asia. The US CHIPS Act and the European Union's "Gallium Nitride for Europe" program represent strategic responses to supply chain vulnerabilities, with both regions investing in domestic GaN production capacity from gallium refining to epitaxial wafer manufacturing and device fabrication. This trend is driving development of alternative gallium sources outside China, including refining projects in Australia, Canada, and Greece, as well as increased investment in Southeast Asian fabrication capacity to serve Western markets with reduced geopolitical risk.
Wafer Size Transition and Manufacturing Innovation
The transition toward larger wafer sizes and manufacturing innovation is emerging as a transformative trend in the Gallium Nitride Semiconductor Device Market, as manufacturers seek to reduce production costs and improve economies of scale through adoption of 6-inch and 8-inch platforms. The shift to larger-diameter GaN-on-silicon wafers enables more devices per wafer and reduced unit costs, improving the competitiveness of GaN devices relative to silicon alternatives in price-sensitive applications. This trend reflects the maturation of GaN technology from specialized, high-value applications toward broader adoption across automotive, consumer, and industrial markets where cost competitiveness is essential. Market participants are investing in advanced epitaxial growth techniques and wafer handling technologies to enable reliable production on larger substrates, addressing historical challenges with defectivity and uniformity.
Gallium Nitride Semiconductor Device Market Opportunities
Automotive Power Electronics and Electric Vehicle Expansion
Significant opportunities exist in the Gallium Nitride Semiconductor Device Market Forecast arising from the expansion of automotive power electronics and electric vehicle applications, where GaN technology offers superior performance for onboard chargers, traction inverters, and DC-DC converters. The global transition toward electric vehicles creates substantial demand for power semiconductor solutions that deliver higher efficiency, reduced weight, and improved thermal management compared to silicon alternatives. Investment opportunities include developing automotive-qualified GaN devices meeting AEC-Q101 requirements, establishing partnerships with automotive Tier 1 suppliers and manufacturers, and creating integrated power modules that combine GaN devices with advanced packaging for improved thermal performance and reliability. The growing emphasis on faster charging capabilities and extended vehicle range is driving innovation in GaN power electronics, creating opportunities for companies that can deliver solutions meeting the rigorous reliability and performance requirements of automotive applications.
Industrial Power Conversion and Energy Efficiency Solutions
The growing emphasis on industrial power conversion and energy efficiency presents significant opportunities for the Gallium Nitride Semiconductor Device Market, as industrial operators seek to reduce energy consumption and improve operational efficiency through advanced power electronic solutions. GaN devices offer substantial efficiency improvements in motor drives, power supplies, and energy conversion systems, enabling industrial applications to reduce energy losses and carbon emissions. Investment opportunities include developing application-specific GaN solutions for industrial motor drives, uninterruptible power supplies, and renewable energy systems, creating integrated power modules that simplify implementation for industrial equipment manufacturers. The increasing focus on sustainability and energy efficiency regulations across industrial sectors is driving demand for GaN-based solutions that can deliver measurable efficiency gains with reduced system size and weight, creating favorable conditions for market expansion in industrial automation and power conversion applications.
Recent Developments
- June 2026: onsemi introduced GaNEXUS™, a new gallium nitride (GaN) power semiconductor portfolio designed to improve efficiency, power density, and thermal performance in next-generation power systems. The portfolio includes GaN FETs ranging from 40V to 650V, including 650V GaNEXUS Smart devices with integrated protection features to simplify system design and improve reliability. Target applications include AI data centers, industrial automation, robotics, 48V power systems, and energy infrastructure.
- February 2026: ROHM announced plans to strengthen its GaN power device production capability by combining its in-house GaN development and manufacturing technologies with TSMC’s GaN process technology. Through this collaboration, ROHM aims to establish an end-to-end production system to support increasing demand for GaN power devices in applications such as AI servers, electric vehicles, AC adapters, and high-voltage power systems.
- December 2025: onsemi announced a collaboration with GlobalFoundries (GF) to develop and manufacture next-generation gallium nitride (GaN) power devices, beginning with 650V lateral GaN solutions. The new GaN devices are targeted for applications including AI data centers, electric vehicles, renewable energy systems, industrial automation, power supplies, DC-DC converters, onboard chargers, solar microinverters, and aerospace and defense systems.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for