
Microplastic Fillers Market Size, Demand & Growth by 2034
Microplastic Fillers Market Size and Forecasts (2021–2034), Global and Regional Share, Trends, and Growth Opportunity Analysis Report Coverage : by Type (Polyurethane, Polyethylene); Function (Rheology Modification, Fillers); Form (Powder, Fiber); End-Use Industry (Packaging, Cosmetics & Personal Care, Construction Materials); and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00040495
- Category : Chemicals and Materials
- No. of Pages : 150
- Available Report Formats :


- Last update date : August 06, 2026


2025 Market Size
US$ 3.23 Bn
Base year value
2034 Forecast
US$ 3.77 Bn
Projected by 2034
CAGR 2026-2034
1.95 %
Growth rate
Addressable Market
US$ 32.06 Bn
(2026-2034)
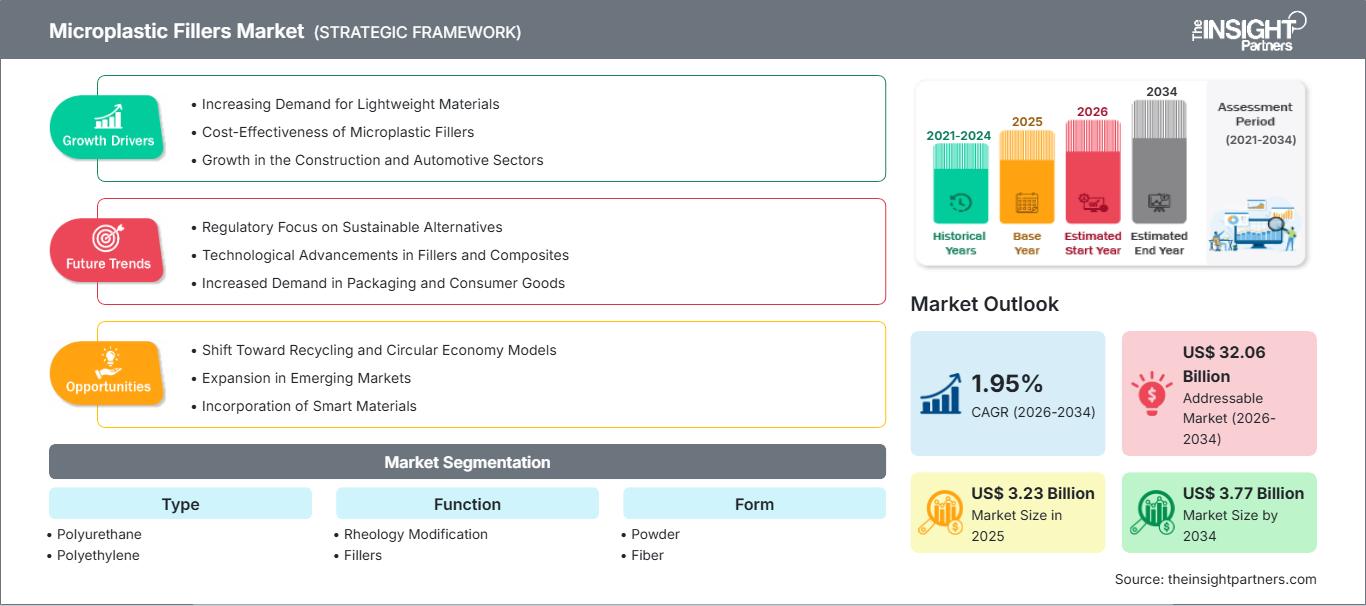
The microplastic fillers market size had a valuation of US$ 3.23 Billion in 2025 and is forecasted to grow to a value of US$ 3.77 Billion by 2034 at a CAGR of 1.95%. The market is driven by consistent demands for specialty polymer additives that ensure improved mechanical properties, dimension stability, and process efficiency in coatings, plastics, adhesives, sealants, and composites. Product innovations in the industry will involve developing better fillers, which will meet sustainable development and regulatory requirements.
In North America, companies are still making efforts towards developing new polymer formulations that provide more durable and efficient polymers for industrial uses. In the microplastic fillers market in North America, the market is predicted to have a CAGR of 1.8% to 2.2% up to 2034 owing to high demands from industries like automotive, specialty coatings, engineered plastics, and manufacturing industry.
Microplastic Fillers Market Assessment and Insights
- North America: Accounted for 34–37% Microplastic Fillers Market share in 2025 and is projected to grow at a CAGR of 1.8–2.2% during 2026–2034. Strong specialty polymer manufacturing capabilities, advanced coatings production, and sustained investment in lightweight composite materials continue supporting regional demand.
- U.S.: Represented 78–82% of the North American market in 2025 and is anticipated to register a CAGR of 1.8–2.2% through 2034, driven by industrial coatings, engineered plastics, automotive components, and polymer research activities.
- Europe: Held 27–30% market share in 2025 and is forecast to expand at a CAGR of 1.5–1.9%. Germany, France, Italy, and the UK remain major consumers due to established plastics processing, specialty chemicals, and industrial manufacturing industries.
- Asia Pacific: Captured 28–31% market share in 2025 and is expected to record the fastest regional CAGR of 2.3–2.8%. China, Japan, India, and South Korea continue expanding production capacity for engineering plastics, coatings, and polymer compounds.
- Largest Segment: Polyurethane accounted for 58–62% market share in 2025 and is projected to grow at a CAGR of 1.8–2.1%, supported by widespread utilization in coatings, elastomers, adhesives, and high-performance industrial formulations.
- High Growth Segment: Fiber represented 28–32% market share in 2025 and is estimated to register a CAGR of 2.3–2.7%, driven by increasing use in reinforced composites and lightweight structural materials.
- Key companies analyzed in detail: BASF SE, Clariant AG, Thermo Fisher Scientific Inc., POLYFILL Technologies Inc., Composition Materials Co., Honeywell International Inc., Schilling Ltd., Kaimaoxing Cellulose (Shandong) Co., Ltd., Precision Drawell Pvt. Ltd., and Goonvean Fibres Ltd.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
Development in the industry will continue as manufacturers favor engineered polymer particles with better dispersion properties, controlled particle morphology, and compatibility with contemporary resin systems. Technical developments in terms of manufacturing methods, surface treatment techniques, and customization have made it possible for fillers to provide better resistance to abrasion, dimensional stability, rheology, and processability. Rising need from industrial coatings, engineered plastics, and advanced composites manufacturers will make the industry players introduce solutions for specific applications that meet higher quality standards.
In terms of the future, investments will be made mostly in Asian Pacific manufacturing facilities and dedicated research centers in North America and Europe. The efforts being made by the government for the promotion of sustainable materials, along with the increased use of recycled polymers and sustainable manufacturing processes, will shape the development path of the companies.
Microplastic Fillers Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 3.23 Billion |
| Market Size by 2034 | US$ 3.77 Billion |
| Global CAGR (2026 - 2034) | 1.95% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Microplastic Fillers Market Analysis
The growing demand for specialty polymers used as additives in industries is expected to shape the development of the microplastic fillers market. Microplastic fillers offer improved properties of stiffness, dimensional stability, abrasion resistance, and processability along with the reduction of the formulation cost in certain industrial applications. Value chain participants include manufacturers of polymer resins, particle engineers, compounders, formulators, distributors, and end users. Thanks to advances in particle size reduction technology, surface treatments, and compounding techniques, manufacturers have been able to produce customized filler grades that meet the increasing demands of the industry.
Factors affecting the supply include the availability of raw materials, prices of polymers, environmental regulations, and process technologies. More manufacturers are now utilizing recycling technology and optimizing production processes to ensure efficient use of resources without compromising on product quality. Strategic partnerships between raw material suppliers and compounders facilitate the launch of specialized fillers designed for automotive parts, coatings, construction materials, and engineering plastics.
The competitive scenario in the microplastic fillers market analysis still holds a moderate consolidation level as players from all across the globe such as global specialty chemical manufacturers compete against regional firms offering tailored polymer fillers. Companies such as BASF SE, Clariant AG, Honeywell International Inc., Thermo Fisher Scientific Inc., Composition Materials Co., and POLYFILL Technologies Inc. will be focusing on innovations in products, advancements in particle engineering, and sustainable materials development in order to establish their market position.
In terms of investment, the trend has been shifting towards sustainable production processes, precision particle engineering, and development of composite materials. Technical services will gain increased emphasis as companies aim at providing assistance to customers in enhancing formulation efficiency in compliance with changing environmental laws. Partnerships, capacity expansions, digital quality control systems, and collaboration of research with industrial manufacturers will be some of the strategic moves of the players during the forecast period, especially in regions undergoing industrialization.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Microplastic Fillers Market: Strategic Insights
Regional Insights
North America Microplastic Fillers Market
North America constituted around 34-37% of the total share of the global market for microplastic fillers in 2025 and is expected to show a CAGR of 1.8-2.2% during 2026-2034. This region is favored by a developed specialty chemicals sector, effective polymer processing facilities, and high demand from the automotive, aerospace, industrial coating, and engineered plastic manufacturers. A focus on product quality and material performance favors the usage of engineered fillers for increasing durability, wear resistance, processing ease, and various industrial uses.
The United States and Canada are continuing their investments in advanced material research and sustainable polymers, helping in innovations in high-performance fillers. Growth is also driven by increased demand for lightweight composites, protective coatings, and specialty adhesives in manufacturing industries. Despite growing strictness of environmental regulations on microplastics, the growth of this regional market is supported by recyclable materials, higher production efficiencies, and specialized particles, ensuring steady demand in the long term.
U.S. Microplastic Fillers Market
United States accounted for 78-82% share of the North American market in 2025 and is projected to grow at a CAGR of 1.8-2.2% during the forecast period. Strength of the country lies in its large scale production capacity of plastics, coatings industry, and consistent R&D in the field of polymers and specialty materials. The demand for these fillers is largely driven by automotive parts, industrial machinery, construction products, consumer goods, and composite materials requiring enhanced mechanical and dimensional stability.
Key players in the market such as Honeywell International Inc., Thermo Fisher Scientific Inc., along with other regional suppliers of specialty materials are increasing their R&D capacities and customized formulation solutions. Increasing use of lightweight materials in transportation and manufacturing industries is boosting demand for custom-engineered fillers with uniform particle size distribution and greater compatibility with various polymers.
Europe Microplastic Fillers Market
Europe held 27-30% share of the world market in 2025 and is predicted to show a CAGR of 1.5-1.9% between 2026 and 2034. The market is led by Germany due to the country’s flourishing automotive manufacturing sector, superior polymer processing ability, and developed specialty chemicals industry.
The United Kingdom continues to provide a stable demand owing to industrial coatings, specialty plastics, and construction materials due to investments in modern manufacturing technologies. Germany has taken advantage of the country's superiority in engineering plastics, automotive manufacturing, and materials' engineering research to become the major contributor in Europe. France, Italy, and Spain jointly boost the demand in the region with the help of increased industrial production, packaging, consumer goods manufacturing, and specialty chemicals. Growing investments into recyclable polymers and environmentally friendly production processes are anticipated to contribute to the further development of the market despite the growing regulations on traditional polymer materials.
APAC Microplastic Fillers Market
Asia Pacific captured 28–31% of the global market in 2025 and is forecast to register the fastest regional CAGR of 2.3–2.8%. China leads regional demand owing to its extensive polymer manufacturing capacity, followed by Japan, India, South Korea, and Australia, which continue expanding production of specialty plastics and industrial composites.
Government support for advanced manufacturing, expanding automotive production, and increasing investments in industrial infrastructure continue supporting regional demand. Rising consumption of engineered plastics, protective coatings, packaging materials, and lightweight composite products is expected to strengthen long-term market development across Asia Pacific.
Middle East & Africa Microplastic Fillers Market
The Middle East & Africa market is anticipated to grow at a CAGR of 1.7–2.2% during the forecast period. Saudi Arabia remains the leading market due to its integrated petrochemical industry, while the UAE and South Africa continue expanding specialty plastics processing and industrial manufacturing capabilities.
Regional growth is supported by ongoing investments in downstream petrochemical production, industrial diversification, and infrastructure development. Increasing adoption of advanced polymer materials across construction, industrial coatings, and manufacturing sectors is expected to create steady opportunities for specialty filler suppliers despite relatively modest overall market expansion.
Segmentation Analysis
Type
The Type segment represents the largest revenue contributor to the market, as polymer selection directly determines filler performance, compatibility, and end-use functionality. The microplastic fillers market scope continues expanding with growing demand for engineered fillers offering improved mechanical strength, abrasion resistance, and dimensional stability across coatings, plastics, composites, and specialty industrial formulations. The segment is projected to grow at a CAGR of 1.8–2.1% during 2026–2034, supported by continuous material innovation and application-specific product development.
- Polyurethane: Widely utilized across coatings, adhesives, sealants, and elastomers due to its excellent flexibility, wear resistance, and compatibility with multiple resin systems. It remains the dominant product category across industrial applications.
- Polyethylene: Increasingly adopted in engineered plastics, packaging materials, and composite formulations because of its low density, chemical resistance, and ability to improve processing efficiency while maintaining cost competitiveness.
Function
The Function segment is anticipated to register a CAGR of 1.9–2.3% during 2026–2034, driven by increasing demand for multifunctional additives that improve processing characteristics while enhancing finished product performance. Industrial manufacturers continue prioritizing fillers capable of delivering both formulation efficiency and mechanical property enhancement across diverse polymer applications.
- Rheology Modification: Supports viscosity control, improved dispersion, sag resistance, and application consistency across paints, coatings, adhesives, and specialty formulations, enabling manufacturers to achieve better processing stability and finished product quality.
- Fillers: Primarily incorporated to improve dimensional stability, stiffness, impact resistance, and cost efficiency while maintaining desirable processing characteristics across engineering plastics, construction materials, and industrial composite products.
Form
The Form segment is expected to expand at a CAGR of 2.0–2.4% during 2026–2034, supported by increasing demand for specialized particle morphologies optimized for advanced manufacturing processes. Selection of filler form significantly influences dispersion quality, reinforcement capability, processing efficiency, and final product performance across multiple industrial applications.
- Powder: Represents the most widely used form owing to its ease of handling, uniform dispersion, broad compatibility with polymer matrices, and suitability for large-scale industrial compounding and coating formulations.
- Fiber: Gains increasing adoption in reinforced composites and high-performance engineering materials where improved tensile strength, crack resistance, lightweight reinforcement, and structural durability are required for demanding industrial applications.
Opportunity Snapshot
| Form | Revenue Contribution | Trend Tag | Adoption Stage |
|---|---|---|---|
| Powder | High | Lightweight Fillers | Mature |
| Fiber | Medium | Reinforcement | Scaling |
Microplastic Fillers Market Growth Drivers and Impact Analysis
Growing Demand for Lightweight Polymer Composite Materials
The increasing adoption of lightweight polymer composites across automotive, construction, industrial coatings, and engineered plastics continues to support demand for microplastic fillers. Manufacturers seek fillers capable of improving dimensional stability, abrasion resistance, scratch resistance, and processing efficiency while minimizing overall formulation costs. Polyurethane and polyethylene based fillers are increasingly incorporated into composite formulations to achieve improved mechanical properties without significantly increasing product weight. Growth in electric vehicles, lightweight consumer products, and durable industrial components further supports material demand. These developments encourage suppliers to invest in advanced polymer particle engineering, surface treatment technologies, and customized particle size distributions that improve compatibility with modern resin systems.
Expansion of High Performance Coatings and Industrial Formulations
Industrial coatings increasingly require fillers that improve rheology, wear resistance, chemical stability, and surface finish. Microplastic fillers offer manufacturers improved formulation consistency while maintaining desirable processing characteristics across multiple coating systems. Growth in protective coatings for infrastructure, marine equipment, industrial machinery, and transportation continues supporting steady demand despite increasing sustainability pressures. Specialty coating manufacturers are developing formulations with optimized particle morphology to reduce defects and improve durability. These factors encourage long-term investments in specialty filler technologies that provide enhanced application performance while meeting increasingly stringent industrial quality specifications.
Continuous Innovation in Specialty Polymer Processing Technologies
Advancements in polymer processing equipment and particle engineering technologies are expanding opportunities for highly specialized filler materials. Precision particle manufacturing enables improved dispersion, lower agglomeration, and better compatibility with engineering polymers used in demanding industrial applications. Producers increasingly develop customized grades tailored for additive manufacturing, specialty adhesives, sealants, and high-performance composite materials. Collaboration between polymer producers and downstream formulators supports innovation in advanced material systems. Although environmental regulations moderate market expansion, technological improvements continue sustaining demand for premium filler grades across specialized industrial sectors where performance remains a primary purchasing criterion.
Microplastic Fillers Market Future Trends
Development of Sustainable and Circular Polymer Fillers
Sustainability initiatives are reshaping product development strategies across the industry. Manufacturers increasingly invest in recycled polymer feedstocks, bio-based alternatives, and improved recyclability while reducing environmental impact throughout production processes. These microplastic fillers market trends indicate that future innovation will focus on balancing material performance with regulatory compliance and circular economy objectives. Companies are expected to introduce environmentally responsible formulations capable of maintaining high mechanical performance while supporting sustainability commitments from industrial customers.
Greater Customization for High-Performance Industrial Applications
Future product development is expected to emphasize application-specific filler designs with optimized particle size, morphology, density, and surface functionality. Manufacturers increasingly require customized fillers capable of enhancing processing efficiency while improving finished product performance. Digital material characterization, advanced quality control systems, and precision particle engineering will support production of differentiated specialty fillers for electronics, aerospace composites, advanced coatings, and engineered plastics. This trend is expected to strengthen supplier competitiveness through higher-value customized product portfolios.
Microplastic Fillers Market Opportunities
Increasing Investments in Advanced Composite Manufacturing
Investment opportunities continue emerging across advanced composite manufacturing industries where lightweight materials and high mechanical performance remain strategic priorities. Automotive electrification, renewable energy equipment, industrial machinery, and infrastructure modernization require specialty fillers capable of improving composite durability and processing efficiency. Microplastic Fillers Market Forecasts indicate that manufacturers emphasizing customized particle technologies, advanced surface treatments, and application-specific formulations are expected to strengthen their competitive positioning. Strategic partnerships with polymer producers and composite manufacturers can further accelerate commercialization of premium specialty filler products while supporting long-term revenue diversification across multiple industrial sectors.
Expansion Across Emerging Industrial Manufacturing Economies
Rapid industrialization throughout Asia Pacific, Latin America, and selected Middle Eastern countries presents attractive opportunities for suppliers of specialty filler materials. Expanding plastics processing, coatings production, automotive manufacturing, and industrial infrastructure projects continue increasing regional demand for performance-enhancing fillers. Establishing local manufacturing facilities, technical support centers, and collaborative research partnerships enables suppliers to strengthen customer relationships while reducing supply chain costs. Companies capable of balancing competitive pricing with high product quality are expected to secure sustainable growth opportunities despite increasing environmental regulations affecting conventional polymer materials.
Recent Developments
- January 2026: MATEtronix acquired the St. Charles manufacturing assets of Microplastics Inc., expanding production capacity for precision plastic components and engineered polymer products.
- July 2025: Star Plastics LLC completed the merger of Trivalence Technologies LLC, expanding its engineered thermoplastics platform through enhanced technical expertise, broader product offerings, wider geographic reach, and greater market diversification. The combined organization also strengthened its capabilities in custom polymer compounds, recycled resins, and specialty filler solutions for injection molding and extrusion applications.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for