
Moisture Cure Adhesives Market Size, Trends & Growth by 2034
Coverage: by Chemistry (Polyurethane, Silicone, Cyanoacrylate, Polyolefin); Application (Construction, Automotive, Wood Working, Textile, Others) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00009057
- Category : Chemicals and Materials
- No. of Pages : 150
- Available Report Formats :


- Last update date : August 17, 2026


2025 Market Size
US$ 6.28 Bn
Base year value
2034 Forecast
US$ 9.84 Bn
Projected by 2034
CAGR 2026-2034
5.12 %
Growth rate
Addressable Market
US$ 73.15 Bn
(2026-2034)
The moisture cure adhesives market size stood at US$ 6.28 Billion in 2025 and is estimated to reach US$ 9.84 Billion by 2034, growing at a CAGR of 5.12% between 2026 and 2034. Growth will remain robust on account of increased usage among manufacturers owing to the need for superior adhesion, durable performance, and weatherability offered by high-performance bonding materials that undergo curing due to exposure to moisture present in the air.
In North America, the moisture cure adhesives market will continue to be positively impacted owing to increasing investments in renovation, commercial, and automotive manufacturing activities. The market in North America is anticipated to grow at a CAGR of 4.8 to 5.3% over the forecast period, driven by the demand for low VOC adhesives and technological advancements in polyurethane and silicone formulations.
Moisture Cure Adhesives Market Assessment and Insights
- North America: Accounted for 31–35% of the global Moisture Cure Adhesives market in 2025 and is projected to grow at a CAGR of 4.8–5.3% during 2026–2034. Infrastructure modernization, advanced manufacturing, and renovation activities continue supporting regional demand.
- US: Represented 79–83% of the North American market in 2025 and is expected to expand at a CAGR of 4.9–5.4% through 2034, supported by construction and automotive production.
- Europe: Held 26–30% market share in 2025 and is forecast to register a CAGR of 4.7–5.2%. Germany, France, Italy, and the UK remain leading contributors due to mature industrial manufacturing and stringent sustainability regulations.
- Asia Pacific: Accounted for 32–36% of global demand in 2025 and is anticipated to grow at a CAGR of 5.8–6.3%, led by China, Japan, South Korea, and India owing to expanding construction and manufacturing activities.
- Largest Segment: Polyurethane dominated with a market share of 42–46% in 2025 and is projected to register a CAGR of 5.1–5.6% owing to superior mechanical strength, flexibility, and weather resistance.
- High Growth Segment: Construction accounted for 33–37% market share in 2025 and is expected to record the fastest CAGR of 5.6–6.1% through 2034 due to increasing infrastructure investments and green building initiatives.
- Key companies analyzed in detail: 3M Company, Bostik SA, H.B. Fuller Company, Henkel AG & Co. KGaA, Illinois Tool Works Inc., Jowat SE, Pidilite Industries Limited, Royal Adhesives and Sealants, LLC, Sika AG, The Dow Chemical Company.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The moisture cure adhesives have progressed from ordinary industrial adhesives to advanced versions that can deliver outstanding properties such as high durability, elasticity, and environmental resilience. The advancement in the chemistry of polyurethane and silicone as well as the use of additives have made it possible for the manufacturers to improve the curing time, mechanical strength, and substrate adaptability while complying with strict environmental and occupational safety standards.
The future market growth of the moisture cure adhesives will be more dependent on research and investment in sustainable adhesive chemistry, eco-friendly materials, and green manufacturing processes. As developing economies build their infrastructure and production capacities, there will be more innovations in moisture cure adhesives due to encouragement from government policies in favor of environmentally friendly materials.
Moisture Cure Adhesives Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 6.28 Billion |
| Market Size by 2034 | US$ 9.84 Billion |
| Global CAGR (2026 - 2034) | 5.12% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Moisture Cure Adhesives Market Analysis
Market dynamics continue to benefit from construction, automotive lightweighting, and industrial manufacturing operations in both developed and developing countries. Market dynamics continue to be fueled by increasing demand for one component adhesive systems which not only make processing easier but also provide good mechanical strength and resistance to water and wear. Increased demand from modular construction systems, prefabricated buildings and engineered wood products can be attributed to better performance and improved efficiencies offered by such products.
Supply side players, polymer companies, formulation companies, distributors, equipment manufacturers, and the end use industries together make up the industry value chain. Raw materials like polyurethane prepolymers, silicone polymers, specialty chemicals and curing agents are some of the critical components that make up the raw material matrix. Secure supply relationships, consistent innovation and technical support services have become critical due to the demand for customized formulations.
Moderate level of consolidation still exists in the competitive environment, with large international companies consolidating themselves via product innovation, M&A transactions, geographical expansion of manufacturing facilities and provision of technical services to customers. As per Moisture Cure Adhesives Market analysis, companies like Henkel AG & Co. KGaA, Sika AG, H.B. Fuller Company, Arkema S.A. (Bostik SA) and The Dow Chemical Company are continuously investing in sustainable adhesive technology, digital formulation as well as localized production to gain competitive advantage in worldwide markets. On the other hand, companies like 3M Company, Jowat SE, Illinois Tool Works Inc., Pidilite Industries Limited and Royal Adhesives and Sealants, LLC are investing in specialized products catering to applications in construction, transportation, woodworking and industrial assembly segments.
Investment of money in production automation, formulation and geographical expansion are becoming key areas for industry participants to address changing customer needs. Development of low VOC adhesives, biobased raw materials and advanced polymer formulations is likely to improve environmental performance while offering high bonding efficiency. Collaboration with companies from construction, automobile and industrial machinery segments will play a vital role in future growth of the industry.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
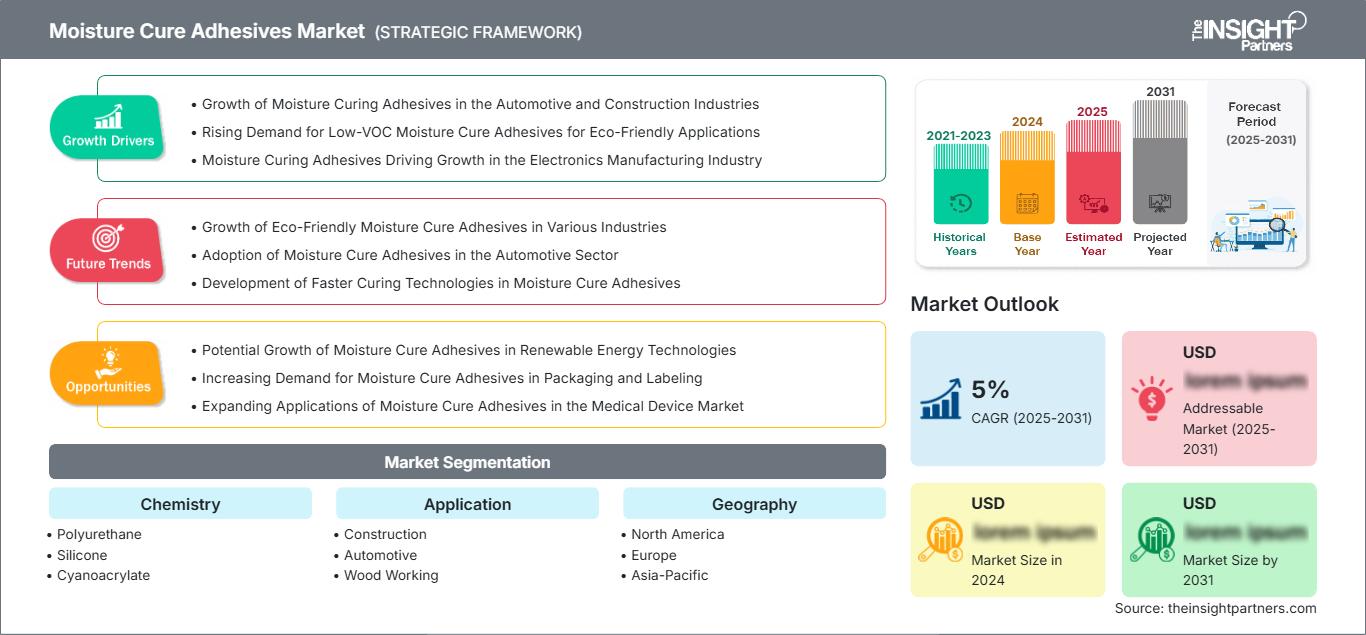
Moisture Cure Adhesives Market: Strategic Insights
Regional Insights
North America Moisture Cure Adhesives Market
The North American region accounted for 31-35% of the global market in 2025 and it is expected to record a CAGR of 4.8-5.3% between 2026 and 2034. This region is characterized by well-established construction industry, advanced automotive industry, and high adoption rates of industrial performance adhesives. Increase in investment in infrastructural development, commercial buildings, and prefabricated buildings continues to drive demand for moisture cure adhesive solutions that have properties of providing robust bonding and efficient application on different substrates. The Moisture Cure Adhesives Market share is noteworthy owing to product innovations and regulatory compliance in the region.
In the United States and Canada, investments are being made in efficient buildings, transportation systems, and manufacturing. Increase in production of electric vehicles, engineered wood, and automation is prompting the use of polyurethane and silicone based moisture cure adhesives. In addition, environmentally friendly product forms are being launched to conform to regulations related to environment with high-performance features.
U.S. Moisture Cure Adhesives Market
The U.S. represented 78–82% of the North American market in 2025 and is expected to expand at a CAGR of 4.9–5.4% through 2034. Strong residential and commercial construction activity, increasing vehicle production, and advanced manufacturing capabilities continue driving adhesive consumption. Government infrastructure investments and renovation activities are further strengthening demand for durable sealing and bonding materials across transportation, industrial equipment, and public infrastructure projects.
Leading manufacturers including 3M Company, H.B. Fuller Company, The Dow Chemical Company, and Illinois Tool Works Inc. maintain extensive manufacturing, research, and distribution networks across the country. Continuous innovation in low-emission adhesive technologies, automated dispensing systems, and high-performance polyurethane formulations supports adoption across automotive assembly, modular construction, engineered wood products, and industrial fabrication, reinforcing the country's leadership within the regional market.
Europe Moisture Cure Adhesives Market
The European region represented 25-29% of the total Moisture Cure Adhesives Market share in 2025, and it is estimated to register a CAGR of 4.7-5.2% in the period 2026-2034. Germany continues to dominate among all the regions owing to its robust automobile, machinery, and construction industries. Growing sustainability norms and circular economy programs have been driving the manufacturers to innovate low emission adhesives along with efficient manufacturing and increased durability.
The United Kingdom and Germany continue to be the leading demand generators. The UK has been deriving demand owing to renovations and modular home developments, whereas Germany has been benefiting from its automotive manufacturing industry, engineering industry, and advanced production technologies. Other major contributors have been France, Italy, and Spain with their growing renovations in buildings, furniture manufacturing, industrial equipment manufacture, and automotive components.
APAC Moisture Cure Adhesives Market
Asia Pacific held 34–38% of the global Moisture Cure Adhesives market in 2025 and is forecast to register the highest regional CAGR of 5.8–6.3% during 2026–2034. China leads regional consumption, supported by large-scale manufacturing, infrastructure investment, and construction activities. Japan and South Korea continue driving demand through advanced automotive and electronics manufacturing.
India is witnessing rapid growth through infrastructure expansion, urbanization, and increasing industrial production, while Australia contributes through commercial construction and mining-related industrial applications. Government initiatives promoting domestic manufacturing and industrial modernization continue strengthening long-term regional demand.
Middle East & Africa Moisture Cure Adhesives Market
Middle East & Africa is anticipated to grow at a CAGR of 5.2–5.7% between 2026–2034. Saudi Arabia is the primary market in the region owing to large infrastructure projects, industrial diversification efforts, and commercial construction activities in the country.
While South Africa will continue to be a significant production base that will fuel demand for industrial adhesives in the region, Rest of MEA will continue to get a boost from construction and energy sector investments. Growth in industrial diversification, logistics improvement, and infrastructure development will ensure consistent growth in high-performance moisture cure adhesives in the region.
Segmentation Analysis
Chemistry
The Chemistry segment is projected to grow at a CAGR of 5.1–5.5% during 2026–2034. Product innovation is centered on improving curing speed, adhesion strength, weather resistance, and environmental performance across multiple substrates. The Moisture Cure Adhesives Market scope continues to expand as manufacturers develop advanced formulations that satisfy evolving industrial standards, sustainability requirements, and application-specific performance needs across construction, transportation, woodworking, and general manufacturing.
- Polyurethane – The dominant chemistry owing to its excellent flexibility, high bond strength, abrasion resistance, and compatibility with concrete, metals, plastics, and wood. It is extensively used across construction, automotive assembly, and industrial manufacturing.
- Silicone – Increasingly adopted for applications requiring exceptional UV resistance, thermal stability, and long-term flexibility. Demand continues rising in glazing systems, façade construction, electronics, and weather-resistant sealing applications.
- Cyanoacrylate – Preferred for precision bonding applications requiring rapid curing and high initial bond strength. The material is widely utilized in electronics assembly, medical devices, consumer products, and specialty industrial manufacturing.
- Polyolefin – Gaining acceptance in lightweight industrial components and packaging applications due to improved chemical resistance, low density, and compatibility with modern polymer-based manufacturing processes.
Application
The Application segment is expected to register a CAGR of 5.2–5.6% during 2026–2034. Rising demand for durable, one-component adhesive systems across infrastructure development, transportation manufacturing, engineered wood products, and industrial production continues supporting market expansion. Increasing adoption of automated assembly processes further strengthens the importance of moisture cure adhesives in achieving reliable, long-lasting structural bonding.
- Construction – Represents the largest application owing to widespread use in flooring, roofing, façade systems, insulation panels, structural glazing, window installation, expansion joints, and waterproof sealing across residential, commercial, and infrastructure projects.
- Automotive – Demand continues increasing with vehicle lightweighting strategies, electric vehicle production, composite material adoption, and improved structural bonding requirements that reduce mechanical fasteners while enhancing durability and vibration resistance.
- Wood Working – Widely utilized in furniture manufacturing, cabinetry, flooring, doors, engineered wood panels, and interior finishing applications where moisture resistance, strong adhesion, and long service life remain essential performance requirements.
- Textile – Used in technical textiles, footwear manufacturing, coated fabrics, protective clothing, and industrial textile lamination where flexibility, wash durability, and consistent adhesive performance improve finished product quality.
Opportunity Snapshot
| End-Use Industry | Revenue Contribution | Trend Tag | Adoption Stage |
|---|---|---|---|
| Construction | High | Green Buildings | Mature |
| Automotive | High | EV Assembly | Scaling |
| Wood Working | Medium | Engineered Wood | Mature |
| Textile | Medium | Technical Fabrics | Scaling |
| Others | Low | Industrial Repair | Emerging |
Moisture Cure Adhesives Market Growth Drivers and Impact Analysis
Expanding Infrastructure and Sustainable Construction Activities
Global investments in residential, commercial, and public infrastructure continue to strengthen demand for high-performance bonding and sealing materials. Moisture cure adhesives are increasingly preferred because they provide excellent adhesion, weather resistance, and durability across concrete, metals, wood, composites, and plastics while simplifying installation through one-component formulations. Green building certifications and stricter construction standards are encouraging the use of low-VOC products with extended service life. Modular construction and prefabricated building systems further increase adhesive consumption by reducing assembly time and improving structural integrity. As governments continue investing in transportation networks, affordable housing, industrial facilities, and urban redevelopment, demand for moisture cure adhesive technologies is expected to remain strong across both developed and emerging economies.
Growing Adoption of Lightweight Materials in Automotive Manufacturing
Automotive manufacturers continue replacing conventional mechanical fasteners with structural adhesive technologies to reduce vehicle weight, improve fuel efficiency, and enhance electric vehicle performance. Moisture cure adhesives provide durable bonding across aluminum, composites, engineered plastics, and coated metals while improving vibration resistance and corrosion protection. Expanding production of battery electric vehicles and hybrid platforms is accelerating demand for advanced adhesive systems capable of supporting lightweight vehicle architectures. Manufacturers are also seeking solutions that improve manufacturing efficiency through simplified processing and reduced curing complexity. As global vehicle electrification accelerates, adhesive technologies are expected to play an increasingly important role in modern automotive assembly and component manufacturing.
Technological Advancements in High-Performance Polymer Formulations
Continuous innovation in polymer chemistry is enabling manufacturers to develop moisture cure adhesives with improved curing speed, higher bond strength, superior environmental resistance, and lower volatile organic compound emissions. Advanced polyurethane and silicone formulations provide enhanced performance under demanding temperature, humidity, and chemical exposure conditions, expanding adoption across industrial manufacturing, transportation, electronics, and construction. Digital formulation tools, automated production systems, and precision dispensing technologies further improve product consistency and manufacturing efficiency. Increasing investments in research and development, combined with rising demand for sustainable materials, are expected to accelerate commercialization of next-generation adhesive technologies capable of meeting increasingly stringent environmental and performance requirements across multiple end-use industries.
Moisture Cure Adhesives Market Future Trends
Development of Sustainable and Bio-Based Adhesive Formulations
Manufacturers are increasingly investing in renewable raw materials, bio-based polyols, recycled feedstocks, and low-emission curing technologies to meet evolving sustainability targets across construction and industrial manufacturing. Moisture Cure Adhesives Market trends indicate that environmentally responsible formulations will gain wider commercial acceptance as governments strengthen regulations on volatile organic compound emissions and lifecycle carbon footprints. Companies are also focusing on improving recyclability, reducing hazardous substances, and enhancing energy efficiency during production. These innovations are expected to strengthen product differentiation while enabling manufacturers to address the sustainability requirements of automotive, construction, furniture, and industrial customers worldwide.
Integration of Smart Manufacturing and Automated Adhesive Dispensing
Industrial manufacturers in the Moisture Cure Adhesives Market are increasingly incorporating automated dispensing equipment, robotics, digital quality monitoring, and precision application technologies into adhesive bonding operations. These systems improve application consistency, reduce material waste, optimize production efficiency, and minimize manual intervention across automotive assembly, electronics manufacturing, engineered wood processing, and construction component fabrication. Real-time monitoring technologies further enhance process control by ensuring accurate adhesive placement and curing performance. As Industry 4.0 adoption expands globally, manufacturers are expected to integrate moisture cure adhesive technologies with intelligent production systems that improve productivity, product quality, and operational efficiency across high-volume manufacturing environments.
Moisture Cure Adhesives Market Opportunities
Expansion of Bio-Based and Low-Emission Adhesive Technologies
Growing environmental regulations and corporate sustainability commitments are creating favorable conditions for manufacturers investing in renewable and low-emission adhesive technologies. Demand is increasing for moisture cure adhesives formulated with bio-based polyols, reduced volatile organic compounds, and safer curing chemistries without compromising bond strength or durability. Construction firms, automotive OEMs, and furniture manufacturers are prioritizing environmentally responsible materials to comply with green building certifications and product stewardship initiatives. Moisture Cure Adhesives Market Forecasts indicate that suppliers capable of commercializing sustainable formulations while maintaining competitive production costs are expected to secure long-term contracts. Strategic collaborations with renewable raw material suppliers and investments in advanced formulation research will create significant competitive advantages across mature and emerging markets.
Growing Industrialization Across Emerging Manufacturing Economies
Rapid industrial development across Southeast Asia, India, Latin America, Eastern Europe, and selected Middle Eastern countries presents substantial opportunities for adhesive manufacturers expanding regional production and distribution capabilities. Rising investments in automotive assembly, consumer goods manufacturing, modular construction, and industrial equipment production continue to increase adhesive consumption across diverse applications. Local manufacturing facilities reduce logistics costs while improving supply reliability and customer responsiveness. Companies establishing technical service centers alongside regional production units can provide customized adhesive solutions that address climate conditions, substrate variations, and regulatory requirements. Long-term infrastructure investments and increasing foreign direct investment further strengthen demand fundamentals, encouraging both multinational corporations and regional suppliers to expand production capacities and strengthen distribution partnerships.
Recent Developments
- July 2026: Matrix Adhesives Group (“Matrix” or the “Company”), a TruArc Partners (“TruArc”) portfolio company and provider of advanced adhesive and sealant solutions for renovation and construction, industrial, commercial, and specialty applications, acquired IPS Adhesives (“IPSA”), a provider of high-performance adhesives serving building and construction, transportation, industrial, and marine industries, from the parent company of IPS Corporation (“IPS”).
- February 2026: Sika acquired Akkim, a leading global manufacturer of adhesives and sealants based in Turkey. According to Sika, this acquisition will strengthen the company’s position in the global adhesives and sealants industry and unlock growth opportunities through expanded presence in the distribution channel and broader geographic reach. In addition, Akkim will add considerable production capacity, enabling a more efficient operational footprint.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for