
Automotive Control Cable Market Share, Growth & Forecast by 2034
Coverage: By Raw Material (Steel, PVC Compound, Copper Rods, Others); Product Range (Single Core Cable, Multi Core Cable); Cable Type (Clutch Cable, Bowden Cable, Throttle Cable, Speedometer Cable, Steering Control Cable, Others); End User (Motorcycles, Passenger Car Cable, Light Commercial Vehicle, Heavy Commercial Vehicle), and Geography
- Status : Data Released
- Report Code : TIPTE100000886
- Category : Automotive and Transportation
- No. of Pages : 150
- Available Report Formats :


- Last update date : August 13, 2026


2025 Market Size
US$ 8.28 Bn
Base year value
2034 Forecast
US$ 11.15 Bn
Projected by 2034
CAGR 2026-2034
3.36 %
Growth rate
Addressable Market
US$ 88.23 Bn
(2026-2034)
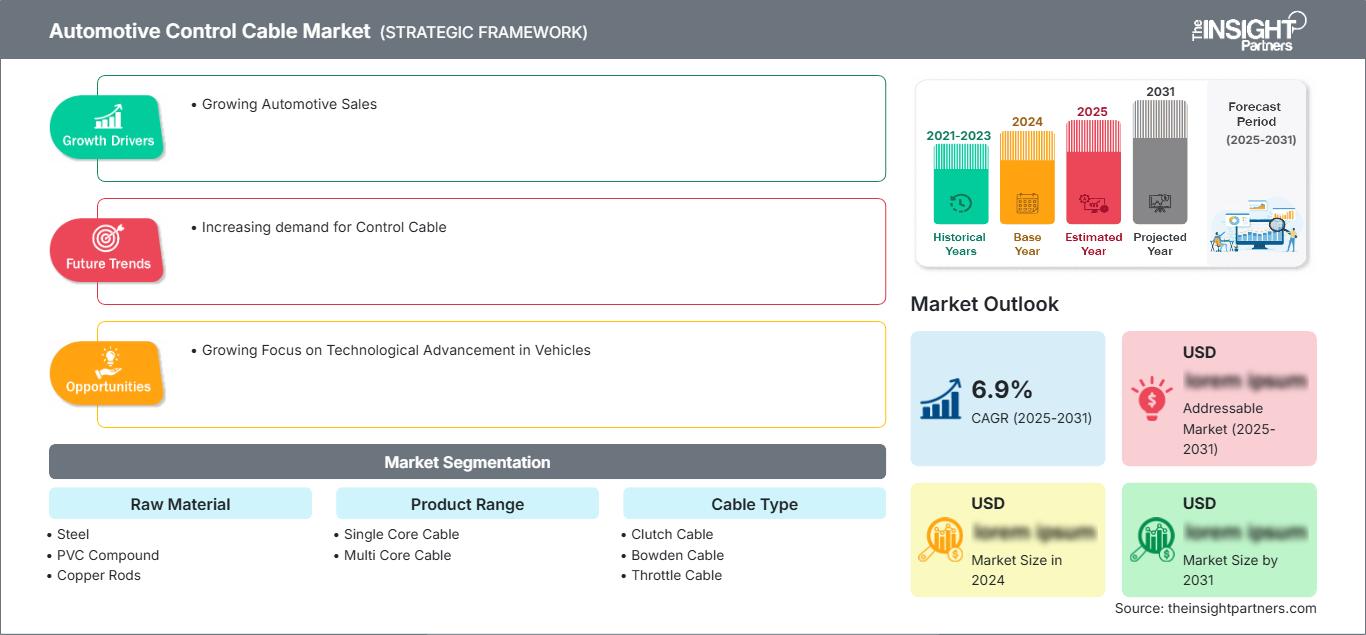
The automotive control cable market was valued at US$ 8.28 Billion in 2025 and is projected to reach US$ 11.15 Billion by 2034, registering a CAGR of 3.36% from 2026 to 2034. Demand remains linked to mechanical motion transfer in clutch, throttle, speedometer, steering, latch, seating, braking, and auxiliary control systems across motorcycles, passenger cars, light commercial vehicles, and heavy commercial vehicles.
North America automotive control cable market size is expected to expand at a CAGR of 2.8–3.3% during 2026–2034, supported by replacement demand, powersports usage, commercial vehicle servicing, and aging vehicle parc dynamics. Regional demand is also reinforced by specialty cable assembly suppliers that provide push-pull, pull-only, Bowden, and custom cable solutions for OEM, aftermarket, marine, off-road, and performance applications.
Automotive Control Cable Market Assessment and Insights
- North America: Accounted for an estimated 22–25% share in 2025 and is expected to grow at a CAGR between 2.8–3.3% during 2026–2034, supported by aftermarket replacement, powersports, and light commercial vehicle demand.
- US: Represented about 76–80% of North America demand in 2025 and is projected to grow at a CAGR between 2.7–3.2% during 2026–2034.
- Europe: Held an estimated 24–27% share in 2025 and is likely to expand at a CAGR between 2.9–3.4%, led by Germany, the UK, France, Italy, and Spain.
- Asia Pacific: Led with an estimated 41–45% share in 2025 and is expected to grow at a CAGR between 3.8–4.4%, driven by China, India, Japan, South Korea, and Australia.
- Largest Segment: Motorcycles estimated 34–38% market share in 2025 and a CAGR between 3.5–4.1% during 2026–2034.
- High Growth Segment: Bowden Cable estimated 28–32% share in 2025 and a CAGR between 4.0–4.7% during 2026–2034.
- Key companies analyzed in detail: Allied Wire & Cable, Inc., Alpha Wire, Cable Manufacturing & Assembly Co., Cable-Tec, Guangzhou Zhujiang Cable Co., Ltd., Jersey Strand and Cable, Inc., LEONI AG, Lexco Cable Manufacturing, SAB Bröckskes GmbH & Co. KG, and TE Connectivity Ltd.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
Technology evolution in the automotive control cable market has moved from basic steel cable assemblies toward low-friction liners, corrosion-resistant coatings, engineered PVC compounds, improved end fittings, and application-specific cable routing. Production dynamics depend on steel wire quality, copper conductor availability, extrusion consistency, crimping accuracy, and validation for heat, vibration, bend radius, and pull force. Manufacturers increasingly design cable assemblies around smoother actuation, longer service life, and compact packaging in crowded vehicle architectures.
Forward demand will remain strongest in Asia Pacific two-wheeler platforms, emerging commercial vehicle fleets, and aftermarket channels that still rely on mechanical control systems. Automotive Control Cable Market forecast projections indicate continued investment in automated cutting, swaging, testing, and custom assembly capabilities. Safety and reliability expectations will support certified suppliers, while electrification will shift some functions to electronic actuation but preserve cable use in parking, seating, hood, latch, and specialty vehicle controls.
Automotive Control Cable Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 8.28 Billion |
| Market Size by 2034 | US$ 11.15 Billion |
| Global CAGR (2026 - 2034) | 3.36% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Automotive Control Cable Market Analysis
The Automotive control cable market growth is supported by vehicle parc expansion, two-wheeler production, commercial vehicle replacement cycles, and continued need for economical mechanical actuation. Even today control cables are still important owing to the fact that they transfer force without electronics, are very durable in hostile environments, and can be replaced easily. Most demand for them comes from motorcycles, economy cars, utility vehicles, and off-road vehicles.
The supply chain involves makers of steel strands, producers of PVC compounds, makers of copper rods, cable assembly makers, Tier 1 firms, distributors, and repair facilities. Automotive control cable market analysis shows that suppliers compete on pull-force consistency, abrasion resistance, routing flexibility, end-fitting precision, and catalogue coverage. Aftermarket buyers often prioritize fitment accuracy and preassembled cables that reduce workshop labor and minimize repeat repairs.
Competition includes global cable technology companies and specialist mechanical cable manufacturers. LEONI AG, SAB Bröckskes GmbH & Co. KG, Alpha Wire, and TE Connectivity Ltd. bring broad cable engineering and automotive-grade capability, while Cable Manufacturing & Assembly Co., Lexco Cable Manufacturing, Jersey Strand and Cable, Inc., Cable-Tec, Allied Wire & Cable, Inc., and Guangzhou Zhujiang Cable Co., Ltd. strengthen the custom and regional supply base.
Investment trends emphasize low-friction Bowden designs, high-temperature jackets, automated assembly, and hybrid mechanical-electrical cable solutions. The Automotive Control Cable Market is seeing suppliers position themselves around OEM qualification, short-run customization, aftermarket availability, and material traceability. Strategic differentiation increasingly depends on designing cables that maintain smooth actuation after repeated cycling, moisture exposure, dirt ingress, and tight routing around compact engines, cabins, and electric vehicle auxiliary systems.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Automotive Control Cable Market: Strategic Insights
Regional Insights
North America automotive control cable market
North America held an estimated 22–25% automotive control cable market share in 2025 and is forecast to grow at a 2.8–3.3% CAGR through 2034. Demand is supported by older vehicles, recreational vehicles, motorcycles, marine equipment, light trucks, powersports platforms, and custom cable assembly needs.
Regional suppliers serve both automotive and adjacent mobility markets, which helps maintain production flexibility despite gradual electronic actuation adoption. Cable Manufacturing & Assembly Co., Lexco Cable Manufacturing, Jersey Strand and Cable, Inc., Allied Wire & Cable, Inc., and TE Connectivity Ltd. support replacement, custom, and OEM-style requirements across mechanical controls, wire rope assemblies, and engineered cable assemblies.
U.S. automotive control cable Market
The US represented an estimated 76–80% of North American demand in 2025 and is expected to grow at a CAGR of 2.7–3.2% during 2026–2034. The Automotive Control Cable Market in the country is shaped by high vehicle age, powersports ownership, specialty vehicle demand, restoration activity, and the ongoing maintenance of clutch, throttle, brake, hood, seat, and parking control cables.
Company presence is strong in custom cable manufacturing, distribution, and aftermarket engineering. Lexco Cable Manufacturing supplies automotive wire rope and push-pull assemblies, while Cable Manufacturing & Assembly Co. focuses on light to heavy-duty mechanical cable assemblies for automotive, powersports, marine, aerospace, and medical uses.
Europe automotive control cable Market
Europe accounted for an estimated 24–27% share in 2025 and is projected to grow at a CAGR of 2.9–3.4% during 2026–2034. The Automotive Control Cable Market in the region is led by Germany, driven by its strong cable engineering capabilities, specialty manufacturing expertise, and deep automotive supplier ecosystem.
The UK supports aftermarket replacement and motorsport-oriented cable requirements, while France, Italy, and Spain add passenger car, motorcycle, and light commercial vehicle servicing demand. LEONI AG and SAB Bröckskes GmbH & Co. KG strengthen the European supplier base through automotive cables, high-voltage cables, custom control cables, and special cable manufacturing.
APAC automotive control cable Market
APAC held the leading 41–45% share in 2025 and is expected to grow at a CAGR of 3.8–4.4% from 2026 to 2034. The Automotive Control Cable Market in the region is led by China due to its large-scale vehicle production, extensive two-wheeler manufacturing activity, deep cable manufacturing ecosystem, and cost-efficient automotive component supply chain.
India contributes strong motorcycle, scooter, and light commercial vehicle demand, while Japan and South Korea add quality-oriented OEM supply chains. Australia supports replacement demand in utility, motorcycle, and off-road applications. Localized manufacturing and expanding vehicle parc support recurring cable replacement.
Middle East & Africa automotive control cable Market
Middle East and Africa is projected to grow at a 2.9–3.5% CAGR during 2026–2034. Saudi Arabia is the leading country, supported by commercial transport, motorcycles, construction fleets, and harsh operating conditions that increase cable wear.
The UAE contributes parts trading and premium vehicle servicing, while South Africa adds assembly and aftermarket channels. Rest of MEA demand is fragmented, but heat, dust, long-distance fleet use, and mechanical repair preferences support clutch, throttle, and Bowden cable replacement.
Segmentation Analysis
Raw Material
Raw Material is expected to grow at a CAGR of 3.1–3.7% during 2026–2034. Automotive control cable market scope in this segment is shaped by tensile strength, insulation durability, corrosion protection, conductivity, cost control, and the ability to withstand heat, vibration, moisture, and repeated bending in vehicle environments.
- Steel remains central for inner wires and strands because it delivers tensile strength, fatigue resistance, and dependable force transmission in clutch, throttle, brake, steering, and Bowden cable assemblies.
- PVC Compound supports protective jackets and liners where flexibility, abrasion resistance, insulation, chemical tolerance, and cost efficiency are required for high-volume automotive cable production.
- Copper Rods are important where electrical or hybrid cable assemblies require conductivity, signal continuity, and integration with vehicle wiring, sensors, or auxiliary control functions.
Product Range
Product Range is forecast to grow at a CAGR of 3.2–3.8% during 2026–2034. Single core cables remain important for simple pull-only actuation, while multi core designs gain value where routing complexity, combined functions, or integrated control and sensing requirements increase.
- Single Core Cable is widely used in direct mechanical controls because it offers simple construction, predictable load transfer, easy replacement, and cost-effective fitment across motorcycles and entry-level vehicles.
- Multi Core Cable supports compact routing and combined functions where multiple conductors, strands, or signal paths are needed within a protected cable assembly for advanced vehicle applications.
Cable Type
Cable Type is projected to grow at a CAGR of 3.3–3.9% during 2026–2034. Demand varies by actuation function, with clutch, throttle, Bowden, speedometer, and steering control cables serving distinct mechanical requirements in conventional vehicles, motorcycles, commercial fleets, and specialty platforms.
- Clutch Cable demand is sustained by manual transmission vehicles, motorcycles, and replacement cycles where smooth disengagement, low stretch, and reliable pedal or lever feel are essential.
- Bowden Cable is the high-growth cable type because flexible routing, low-friction operation, and protected pull-force transmission support seats, latches, parking systems, motorcycles, and compact vehicle layouts.
- Throttle Cable remains relevant in motorcycles, small engines, legacy vehicles, and performance applications where direct mechanical response and straightforward serviceability continue to matter.
- Speedometer Cable demand is more replacement-oriented as digital sensors expand, but legacy motorcycles, commercial vehicles, and restoration markets still require accurate mechanical speed transmission.
- Steering Control Cable serves selected specialty, marine, off-road, and auxiliary vehicle systems where flexible mechanical motion transfer is preferred over more complex electronic or hydraulic alternatives.
End User
End User is expected to grow at a CAGR of 3.4–4.0% during 2026–2034. Motorcycles lead demand because they use multiple exposed and serviceable mechanical cables, while passenger and commercial vehicles generate steady cable replacement through clutch, parking, hood, latch, and auxiliary controls.
- Motorcycles generate the largest demand because throttle, clutch, brake, choke, speedometer, and control functions remain cable-intensive across commuter, premium, off-road, and aftermarket segments.
- Passenger Car Cable demand is supported by replacement of hood, seat, parking, clutch, and latch cables, especially in older vehicles and cost-sensitive models retaining mechanical controls.
- Light Commercial Vehicle applications prioritize durable cables for frequent use, fleet uptime, and serviceability across delivery vans, pickups, small trucks, and utility platforms.
- Heavy Commercial Vehicle demand centers on robust cables that withstand vibration, long operating hours, heat, dust, and maintenance cycles in transport, construction, and vocational fleets.
Opportunity Snapshot
| End User | Revenue Contribution | Trend Tag | Adoption Stage |
| Motorcycles | High | Two Wheeler | Mature |
| Passenger Car Cable | Medium | Service Parts | Mature |
| Light Commercial Vehicle | Medium | Fleet Repair | Scaling |
| Heavy Commercial Vehicle | Medium | Duty Cycle | Scaling |
Automotive Control Cable Market Growth Drivers and Impact Analysis
Two-Wheeler and Entry Vehicle Mechanical Control Demand
Motorcycles, scooters, and low-end passenger cars will continue using mechanical cables due to their affordability, packagability, and reparability. Throttle, clutch, braking, choke, and speedometer systems typically employ cable assemblies that are exposed to vibrations, dust, moisture, and constant lever actuation. The driver force here lies in India, Southeast Asia, China, Africa, and Latin America, where two-wheelers play a crucial role in people’s mobility. The market influence includes repeated purchases by the original equipment manufacturers (OEM) and aftermarket players; high demand for custom fitments; and ongoing innovations in terms of low friction liners and corrosion resistance.
Aftermarket Replacement Across Aging Vehicle Fleets
The control cables are wear items due to the deterioration of their internal strands, liners, jackets, boots, and fittings after the repetitive motion and heating, contamination with dirt, moisture, and automotive road deicing salt. The aging fleet of vehicles will result in more replacements, particularly clutch, parking brake, hood release, throttle, and seat cables. In independent repair shops, it is advantageous to have complete assemblies of the cable, which shorten installation and ensure consistent actuation of the controls. This customer will benefit distributors, catalogers, and custom cable manufacturers in North America and Europe.
Cost-Efficient Reliability in Commercial and Specialty Vehicles
The advantages that mechanical cables have over electronic actuators include that they are reliable in transferring force without using any electronics. In tough conditions, a durable cable may be easier to identify and replace than an electronic actuator. Predictable maintenance and access to local repairs are also important factors for fleets. It is advantageous to the supplier who produces heavy-duty push-pull cables, Bowden cables, and wire rope assemblies, which are protected against wear and tear. The market effect is increased resilience despite the growing use of electronic controls in passenger cars.
Automotive Control Cable Market Future Trends
Hybrid Mechanical-Electrical Cable Assemblies
The automotive control cable market trends are moving toward hybrid assemblies that combine mechanical actuation with sensors, conductive paths, or diagnostic features. Such assemblies could offer the functionality of traditional cable assemblies while including feedback on positioning, wear, or compatibility with the electrical system in the vehicle. This product would appeal to OEM customers who want redundancy but cannot afford to replace the mechanical components entirely. Suppliers that have knowledge in both cable assembly and electronic interconnections will benefit from such higher value-added products. Future success will be contingent upon controlling costs and proper sealing.
Low-Friction and Long-Life Bowden Cable Designs
In future designs, there will be a stronger consideration towards the need for low pull force, longevity, and maintenance considerations. Manufacturers of Bowden cables are developing liners, sheath configurations, lubrication techniques, and terminations to ensure that the cables continue to function smoothly despite having to go through stringent routing and environmental conditions. The development is particularly important in applications such as motorcycles, latch systems, seating systems, parking systems, and specialized control systems where customer feel and reliability are tangible.
Automotive Control Cable Market Opportunities
Premium Replacement Kits for Motorcycles and Fleets
The automotive control cable Forecasts highlight a realistic possibility within high-value kits for use in motorbikes, light commercial vehicles, and fleet management. The suppliers can include cables, together with boots, adjusters, brackets, and installation instructions to minimize mistakes within workshops. This is a realistic option because most repairs are fitment-dependent, and a failure directly influences the driver's control. High-value kits would be profitable since durability, smoothness, resistance to corrosion, and minimal downtime make value for everyone concerned.
Localized Manufacturing for Emerging Aftermarket Channels
Cable manufacture and catalog development is possible in emerging markets due to increased vehicle parc resulting in increased demand for services. Cable manufacturers in India, China, Southeast Asia, Africa, and Latin America need to make sure that they are providing affordable cables for motorcycles, small cars, and commercial vehicles. Locating extrusion, crimping, swaging, and assembly processes in these regions will help in decreasing the turnaround time and also developing suitable products based on the region’s vehicles. Companies that have good pricing policies and conduct testing will earn the respect of distributors.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners provided valuable market intelligence that supported our global go-to-market strategy. Their team was professional, responsive, and attentive to our feedback, providing thoughtful analysis and helpful methodological clarifications throughout the project.
Junmo Kim Chief Financial Officer (CFO), Enertech Co., Ltd.
The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for