
Cardiac Marker Testing Market Demand, Trends & Forecast by 2034
Coverage: By Product Type (Reagents and Kits, Instruments); Biomarker Type (Troponin I and T, CK-MB, BNP, Myoglobin, Hs-CRP, Other Biomarkers); Application (Myocardial Infarction, Congestive Heart Failure, Acute Coronary Syndrome, Atherosclerosis, Ischemia); End User (Laboratory Testing, Point-Of-Care-Testing, Others) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00022451
- Category : Life Sciences
- No. of Pages : 150
- Available Report Formats :


- Last update date : September 08, 2026


2025 Market Size
US$ 5.65 Bn
Base year value
2034 Forecast
US$ 12.55 Bn
Projected by 2034
CAGR 2026-2034
9.29 %
Growth rate
Addressable Market
US$ 81.39 Bn
(2026-2034)
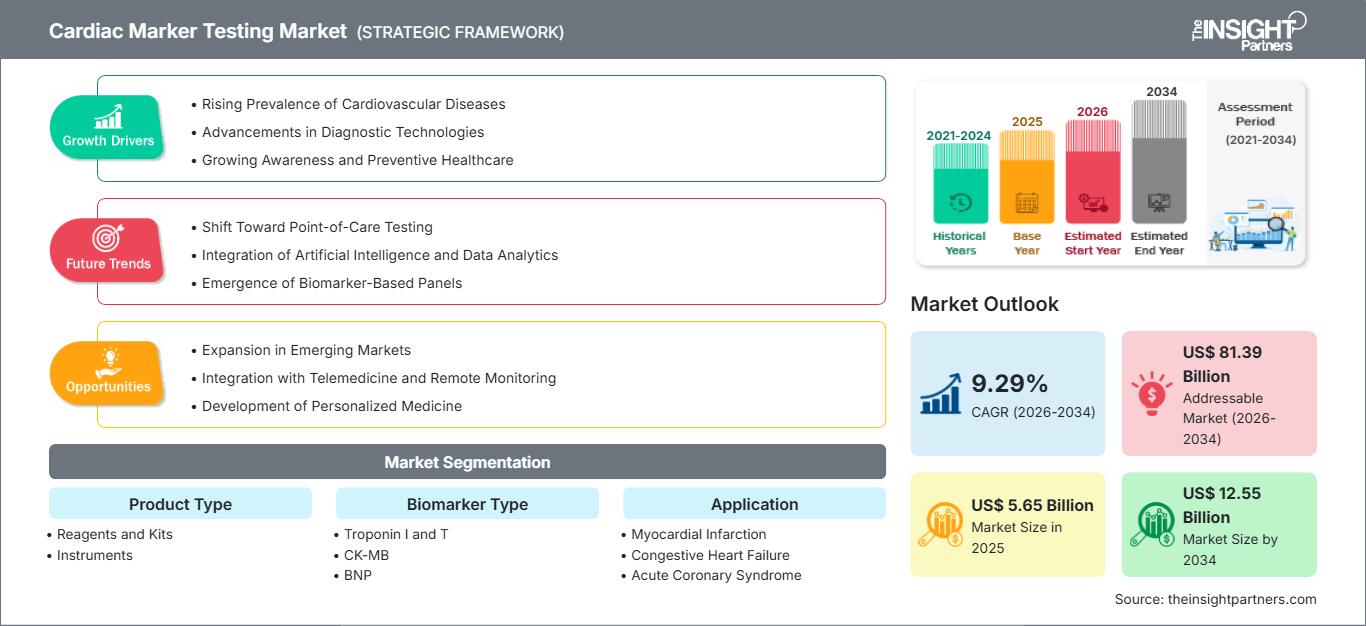
The Cardiac Marker Testing Market was valued at US$ 5.65 Billion in 2025 and is projected to reach US$ 12.55 Billion by 2034. The market is expected to register a CAGR of 9.29% during 2026–2034, reflecting sustained demand for biomarker-based diagnosis across emergency departments, centralized laboratories, cardiac care units, and decentralized testing environments.
North America provides a substantial foundation for the Cardiac Marker Testing Market size, with the region estimated to advance at a CAGR of 8.6–9.2% during 2026–2034. Broad access to high-sensitivity troponin assays, established emergency care protocols, integrated laboratory networks, and continued investment in rapid clinical decision-making support regional adoption. Rising cardiovascular disease prevalence and value-based hospital management further encourage testing standardization.
Cardiac Marker Testing Market Assessment and Insights
- North America: The region accounted for an estimated 36–39% share in 2025 and is projected to record a CAGR of 8.6–9.2% during 2026–2034, supported by high-sensitivity assay adoption, reimbursement coverage, and established acute-care infrastructure.
- US: The US represented an estimated 82–85% of North American revenue in 2025 and is expected to expand at a CAGR of 8.7–9.3% during 2026–2034.
- Europe: Europe held an estimated 27–30% share in 2025 and is projected to grow at a CAGR of 8.1–8.8% during 2026–2034. Germany, the UK, France, Italy, and Spain remain important diagnostic markets.
- Asia Pacific: Asia Pacific captured an estimated 22–25% share in 2025 and is forecast to register a CAGR of 10.4–11.2% during 2026–2034, led by China, Japan, India, South Korea, and Australia.
- Largest Segment: Reagents and Kits held an estimated 66–70% market share in 2025 and are projected to grow at a CAGR of 9.5–10.1% during 2026–2034 due to recurring testing demand.
- High Growth Segment: Point-Of-Care-Testing represented an estimated 24–28% market share in 2025 and is forecast to expand at a CAGR of 11.0–11.8% during 2026–2034.
- Key companies analyzed in detail: Roche Diagnostics International Ltd., Abbott Laboratories, Siemens Healthineers AG, Danaher Corporation, QuidelOrtho Corporation, Randox Laboratories Ltd., bioMérieux SA, LSI Medience Corporation, DiaSorin S.p.A., and Bio-Rad Laboratories, Inc.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
Testing in the clinical arena has progressed beyond CK-MB and myoglobin into high sensitivity troponin I and T tests that can be used for rapid rule-in and rule-out strategies. Analytical sensitivity, automation capability, stability of the tests, and throughput are being improved by the manufacturers as laboratories transition to immunoassay platforms for cardiac panels. Trends in production dynamics are favoring production of reagents, standardization of calibrators, automation-ready controls, and instrument agnostic quality systems. Meanwhile, point-of-care companies are lowering the sample volume and turnaround time requirements without sacrificing analytical performance.
Capital spending is anticipated to shift towards compact analyzers, connectivity solutions, and multiplex clinical pathways during the forecast period. In Asia-Pacific, Middle-East, and some African countries, expansion opportunities exist due to government initiatives towards development of emergency medicine, laboratory systems, and chronic disease management programs. Acceptance of high sensitivity assays, outcome-based payment system, and quality harmonization will support adoption. Companies able to supply economical test kits, technical service, and calibrator supplies stand to gain from recurring demand.
Cardiac Marker Testing Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 5.65 Billion |
| Market Size by 2034 | US$ 12.55 Billion |
| Global CAGR (2026 - 2034) | 9.29% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Cardiac Marker Testing Market Analysis
The growth of the Cardiac Marker Testing Market is fueled by the increasing need to differentiate myocardial infarction, acute coronary syndrome, heart failure, and noncardiac chest pain. According to WHO reports, there were 19.8 million deaths due to cardiovascular diseases in 2022, which constitute around 32% of the total global deaths, where 85% of deaths are due to heart attack and stroke. The burden of the disease helps in driving recurring demand from emergency departments, cardiology units, diagnostic laboratories, and ambulance testing.
This market ecosystem consists of antibody and reagent manufacturers, assay makers, analyzer producers, quality control organizations, distributors, laboratories, hospitals, and clinical guidelines authorities. Consistent supply is very crucial because serial testing requires constant performance and availability of reagents. High-volume laboratories prefer multi-analyte immunoassays systems, while low-volume laboratories prefer stable cartridges, easy workflows, quick turnaround time, and integration with LIS systems.
Market analysis of Cardiac Marker Testing Market reveals that the competitive landscape is characterized by installed bases of analyzers, assay menu, regulatory clearance, service capability, and long-term reagent contract. The main competitors include Roche Diagnostics International Ltd., Abbott Laboratories, and Siemens Healthineers AG because of high sensitivity troponin portfolio and integrated laboratory system. Danaher Corporation, QuidelOrtho Corporation, bioMérieux SA, and DiaSorin S.p.A. strengthen the competition by way of integration with workflow, assay, and regional distribution.
The Cardiac Marker Testing Market forecast indicates that future investments in the market are geared towards prognostics, automated interpretation, quality assurance, and point-of-care applications. Randox Laboratories Ltd. and Bio-Rad Laboratories, Inc. help in maintaining the consistency of the test with their control and external quality program, while LSI Medience Corporation helps in providing specialty in immunoassay. Increasingly competitive positioning will require evidences regarding rapid algorithms, sex specific cut-off values, interference, uptime, and economic benefit in EDs.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Cardiac Marker Testing Market: Strategic Insights
Regional Insights
North America Cardiac Marker Testing Market
North America held an estimated 36–39% share in 2025 and is projected to register a CAGR of 8.6–9.2% during 2026–2034. Cardiac Marker Testing Market share is driven by substantial emergency department facilities, laboratory accreditation, extensive immunoassay analyzers distribution, and use of high sensitivity troponin in the diagnosis of myocardial infarction.
There is regional demand as well due to substantial prevalence of cardiovascular disease. According to the American Heart Association, 127.9 million Americans suffered from some kind of cardiovascular disease in 2017-2020, and total cardiovascular costs in the US were equal to US$ 417.9 billion in 2020-2021. Canada drives regional demand via laboratory modernization, while Mexico provides affordable point-of-care deployments.
U.S. Cardiac Marker Testing Market
The US accounted for an estimated 82–85% of North American revenue in 2025 and is projected to expand at a CAGR of 8.7–9.3% during 2026–2034. More hospitals are adopting protocols for high-sensitivity troponins to help expedite patient disposition, avoid unnecessary hospitalization, and enhance standardization between EDs and core laboratories.
There are Roche Diagnostics International Ltd., Abbott Laboratories, Siemens Healthineers AG, Danaher Corporation, QuidelOrtho Corporation, and Bio-Rad Laboratories, Inc. companies that are strong commercially and service-wise across the country. The trend is moving towards high sensitivity testing, automation and comparative testing, and risk assessment testing. Siemens Healthineers offers high-sensitivity troponin I test with results in 10 minutes in STAT mode on their Atellica instrument.
Europe Cardiac Marker Testing Market
Europe represented an estimated 27–30% share in 2025 and is expected to record a CAGR of 8.1–8.8% during 2026–2034. Germany is leading through its large number of hospital labs, decentralized emergency medicine services, and the high uptake of automated immunoassays. In the UK, clinical pathways and centralized purchasing practices make things easier despite the budget pressure, which increases the need to measure the efficiency of workflows.
In France, the combination of public hospitals’ purchasing processes and growing private laboratory networks has created favorable conditions. Italy and Spain create a demand for tests through their improvement of emergency medicine, diagnostic consolidation, and aging populations. European adoption is possible due to CE-marked assays and fast troponin algorithms. Roche's sixth generation high-sensitivity Troponin T test obtained the CE mark in 2025 and was validated using a clinical study with over 13,000 participants.
APAC Cardiac Marker Testing Market
Asia Pacific held an estimated 22–25% share in 2025 and is forecast to expand at a CAGR of 10.4–11.2% during 2026–2034. China leads through hospital expansion, domestic diagnostics manufacturing, and increasing automation. Japan emphasizes assay precision and laboratory quality, while India offers substantial potential for compact and cost-efficient testing.
South Korea supports advanced immunodiagnostics adoption, and Australia maintains mature emergency testing protocols. Public investment in tertiary hospitals, urban diagnostic chains, and noncommunicable disease screening strengthens regional demand. Local manufacturing and distributor partnerships are expected to improve affordability and service responsiveness.
Middle East & Africa Cardiac Marker Testing Market
The region is projected to grow at a CAGR of 8.9–9.7% during 2026–2034. Saudi Arabia leads through hospital construction, laboratory digitization, and health-sector diversification. The UAE supports premium diagnostic platforms and centralized hospital networks, while South Africa anchors sub-Saharan laboratory demand.
Rest of MEA presents uneven adoption due to infrastructure and reimbursement constraints. Investment in emergency departments, electrical reliability, cold-chain logistics, and trained laboratory personnel remains essential. Compact analyzers and stable reagent formats offer practical routes into underserved facilities.
Segmentation Analysis
Product Type
Product Type is projected to expand at a CAGR of 9.2–9.8% during 2026–2034. The Cardiac Marker Testing Market scope includes recurring consumables and dedicated or integrated instruments used across core laboratories and near-patient settings. Purchasing decisions increasingly consider total cost per reportable result, calibration frequency, throughput, maintenance requirements, connectivity, and compatibility with rapid diagnostic protocols.
- Reagents and Kits: Recurring demand, short replenishment cycles, expanding test volumes, and assay-specific consumables make this the leading product category. High-sensitivity troponin kits hold particular strategic importance for emergency testing workflows.
- Instruments: Automated laboratory analyzers and compact point-of-care systems support workflow differentiation. Demand centers on rapid processing, low sample volumes, connectivity, reliable calibration, simplified maintenance, and broad cardiac assay menus.
Biomarker Type
Biomarker Type is forecast to grow at a CAGR of 9.3–9.9% during 2026–2034. Adoption is guided by clinical specificity, diagnostic timing, guideline positioning, and compatibility with serial measurement. Troponin remains central to myocardial injury assessment, while BNP, hs-CRP, CK-MB, and myoglobin address heart failure evaluation, inflammation, reinfarction assessment, and complementary clinical interpretation.
- Troponin I and T: These biomarkers occupy the leading position because of myocardial specificity and inclusion in rapid infarction pathways. High-sensitivity formats enable lower-level measurement and more confident interpretation of serial changes.
- CK-MB: Demand persists in selected reinfarction, peri-procedural, and legacy testing protocols. Its strategic relevance is strongest where clinicians combine enzyme kinetics with troponin results and broader clinical evidence.
- BNP: BNP testing is important for evaluating suspected heart failure, differentiating cardiac from respiratory causes of dyspnea, and supporting prognosis, treatment monitoring, and hospital admission decisions.
- Myoglobin: Rapid release after muscle injury supports early assessment, but limited cardiac specificity restricts standalone use. Its role is primarily complementary within multi-marker panels and time-sensitive emergency workflows.
- Hs-CRP: The marker supports cardiovascular inflammation and risk assessment rather than acute infarction confirmation. Demand is associated with preventive cardiology, atherosclerotic risk stratification, and longitudinal patient management.
Application
Application is expected to register a CAGR of 9.1–9.7% during 2026–2034. Clinical use extends from acute myocardial injury detection to heart failure assessment and longer-term cardiovascular risk evaluation. Test selection depends on presentation, timing, comorbidities, baseline biomarker concentrations, renal function, and access to serial sampling.
- Myocardial Infarction: This application generates substantial testing volume because suspected infarction requires rapid baseline and repeat measurements. High-sensitivity troponin supports earlier clinical decisions and streamlined emergency department disposition.
- Congestive Heart Failure: BNP and related natriuretic peptide testing enable diagnostic clarification and prognostic assessment. Demand rises with aging populations, recurrent hospitalizations, and greater emphasis on longitudinal disease management.
- Acute Coronary Syndrome: Multi-step assessment integrates symptoms, electrocardiography, troponin changes, and clinical risk scores. Testing is strategically important for distinguishing infarction, unstable angina, and noncardiac conditions.
- Atherosclerosis: Hs-CRP and emerging biomarkers complement lipid measurements and clinical risk factors. Adoption centers on preventive cardiology, residual inflammatory risk, and identification of patients requiring intensified intervention.
- Ischemia: Biomarker testing supports evaluation where cardiac injury is suspected but imaging or electrocardiographic findings are inconclusive. Demand depends on assay specificity and integration with broader diagnostic pathways.
End User
End User demand is projected to rise at a CAGR of 9.4–10.0% during 2026–2034. Central laboratories retain volume advantages, automation, and quality oversight, while decentralized settings gain relevance where rapid decisions affect treatment and patient disposition. Procurement increasingly evaluates turnaround time, operator competency, quality control, connectivity, and clinical governance.
- Laboratory Testing: Centralized and hospital laboratories represent the established testing base through automated processing, standardized quality systems, high throughput, and broad assay menus suitable for routine and complex cardiac assessment.
- Point-Of-Care-Testing: Adoption is scaling in emergency departments, ambulances, intensive care units, and remote facilities. Rapid turnaround and reduced transport delays provide strategic value where immediate decisions influence treatment.
Opportunity Snapshot
| End User | Revenue Contribution | Trend Tag | Adoption Stage |
| Laboratory Testing | High | Workflow Automation | Mature |
| Point-Of-Care-Testing | High | Rapid Triage | Scaling |
| Others | Low | Care Decentralization | Emerging |
Cardiac Marker Testing Market Growth Drivers and Impact Analysis
Escalating Clinical Burden of Cardiovascular Disease
Cardiovascular disease continues to be the number one killer globally and hence there is ongoing need for testing in the emergency care, in-patient, out-patient, and preventive care environment. According to the statistics provided by WHO, more than 75% of the cardiovascular deaths are reported from poor and middle income countries. This underscores the need for having capacity to test in markets that are not yet mature. Cardiac marker testing plays an important role in helping healthcare professionals in making differentiation between myocardial injury, heart failure, inflammatory and non-cardiac situations. With expansion of the healthcare system in terms of emergency medicine and referral system, volume of tests goes up due to access rather than prevalence.
Expansion of High-Sensitivity Troponin Protocols
High-sensitivity troponin tests help in identifying smaller changes in biomarkers and allow for faster serial testing algorithms. There are several benefits of high-sensitivity troponin tests in addition to improved analytical capabilities since a shorter rule-out process will save time, optimize flow in the emergency department, and allocate resources to patients who require immediate intervention. As an example, Roche said that just one out of ten patients arriving at the emergency department complaining about chest pain has suffered from acute myocardial infarction, which proves the importance of reliable exclusion strategies. Thus, such adoption will result in continuous reagent sales along with the need for upgrades in equipment and other supplies.
Decentralization of Time-Critical Diagnostic Testing
Cardiac test kits are increasingly being moved closer to patients in ERs, ambulances, ICUs, and regional hospitals. This will cut down on specimen transport and queuing time at laboratories in order to facilitate triaging where laboratory infrastructure is limited. The CARDIAC point-of-care Troponin T from Roche is a test which can be conducted in areas such as ambulances, physician offices, and EDs, thus indicating how the scope of cardiac testing is expanding. It is important to ensure that there is equivalent lab control through operator training, internal controls, external quality assessments, and result transmissions.
Cardiac Marker Testing Market Future Trends
Algorithm-Assisted Interpretation of Serial Biomarker Results
Cardiac Marker Testing Market trends would be increasingly dominated by the combination of test results with patient’s history, electrocardiography and clinical decision-making algorithms. Such systems could make calculations for biomarker deltas, determine sampling intervals, detect unusual patterns, and create standardized guidelines to rule-in, rule-out, or to observe the patient. Roche gained the CE marking in April 2025 for its chest pain triage algorithm that is based on high-sensitivity cardiac troponin tests and clinical guidelines of Europe. The future systems would probably include more explanation, interoperability, audit trail capabilities, and custom hospital-based pathways creation.
Broader Use of Multi-Marker and Prognostic Panels
Test approaches will evolve from single event confirmatory tests to those that have a combined role of diagnostics, prognosis, and monitoring. The interpretation of troponin will include BNP, hs-CRP, renal parameters, metabolic biomarkers, or even new proteins in order to provide a comprehensive understanding of myocardial damage and systemic risks. This will facilitate the development of multiplexing and the creation of menus for the analyzers, but will also increase the need for reference ranges and clinical validation. Providers will focus on test panels that offer actionable differences, as opposed to superfluous information not useful in a therapeutic approach.
Cardiac Marker Testing Market Opportunities
Affordable Point-of-Care Networks in Emerging Health Systems
Emerging markets provide an investment opportunity for compact analyzers, room-temperature-stable consumables, and service models designed for distributed healthcare infrastructure. Companies can partner with ministries, hospital groups, ambulance networks, and diagnostic chains to establish standardized cardiac testing across urban and regional facilities. Effective programs require more than instrument placement. They need operator certification, quality-control schedules, connectivity, maintenance, and reliable consumable replenishment. Local assembly or packaging can reduce import exposure and improve tender competitiveness. Subscription, reagent-rental, and managed-service arrangements may lower initial capital barriers while creating predictable recurring revenue. Market entry should prioritize countries expanding emergency capacity and noncommunicable disease coverage.
Assay Conversion Within Established Analyzer Fleets
Large installed analyzer bases create opportunities to convert laboratories from conventional cardiac assays to high-sensitivity formats without replacing complete automation systems. Vendors can target conversion through clinical evidence, validation support, staff education, middleware configuration, and economic assessments of patient-flow benefits. QuidelOrtho’s 2025 US clearance for the VITROS hs Troponin I Assay demonstrates how menu expansion can unlock demand among existing platform users. Successful conversion strategies should address lot comparison, reference ranges, reporting comments, clinician communication, and legacy-result interpretation. Companies combining assay upgrades with implementation services can reduce switching friction, build customer retention, and expand recurring reagent utilization.
Recent Developments
- November 2025: QuidelOrtho Corporation received US FDA 510(k) clearance for the VITROS hs Troponin I Reagent Pack. The assay quantitatively measures cardiac troponin I in heparin plasma to aid myocardial infarction diagnosis and was scheduled for commercial rollout to US laboratories operating VITROS Systems later in 2025.
- September 2025: Roche Diagnostics International Ltd. announced clinical results for its CE-marked sixth-generation Elecsys high-sensitivity Troponin T assay. The TSIX study program included more than 13,000 participants and evaluated the assay’s ability to identify acute myocardial infarction and support reliable exclusion of patients without infarction.
- April 2025: Roche Diagnostics International Ltd. received CE marking for its navify Chest Pain Triage algorithm, developed with Heidelberg University Hospital. The system combines high-sensitivity troponin testing with guideline-based assessment to provide rule-in, rule-out, or observation recommendations for patients presenting with suspected acute coronary syndrome.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for