
Flexible Packaging Market Trends, Size & Forecast by 2034
Coverage: By Material (Plastics, Paper, Aluminum Foils, and Others), Product Type (Pouches, Bags, Films and Wraps, and Others), and Application (Food and Beverages, Medical and Pharmaceutical, Personal Care and Cosmetic, Industrial, and Others)
- Status : Data Released
- Report Code : TIPRE00004515
- Category : Chemicals and Materials
- No. of Pages : 150
- Available Report Formats :


- Last update date : October 26, 2026


2025 Market Size
US$ 207.40 Bn
Base year value
2034 Forecast
US$ 310.73 Bn
Projected by 2034
CAGR 2026-2034
4.6 %
Growth rate
Addressable Market
US$ 2,353.06 Bn
(2026-2034)
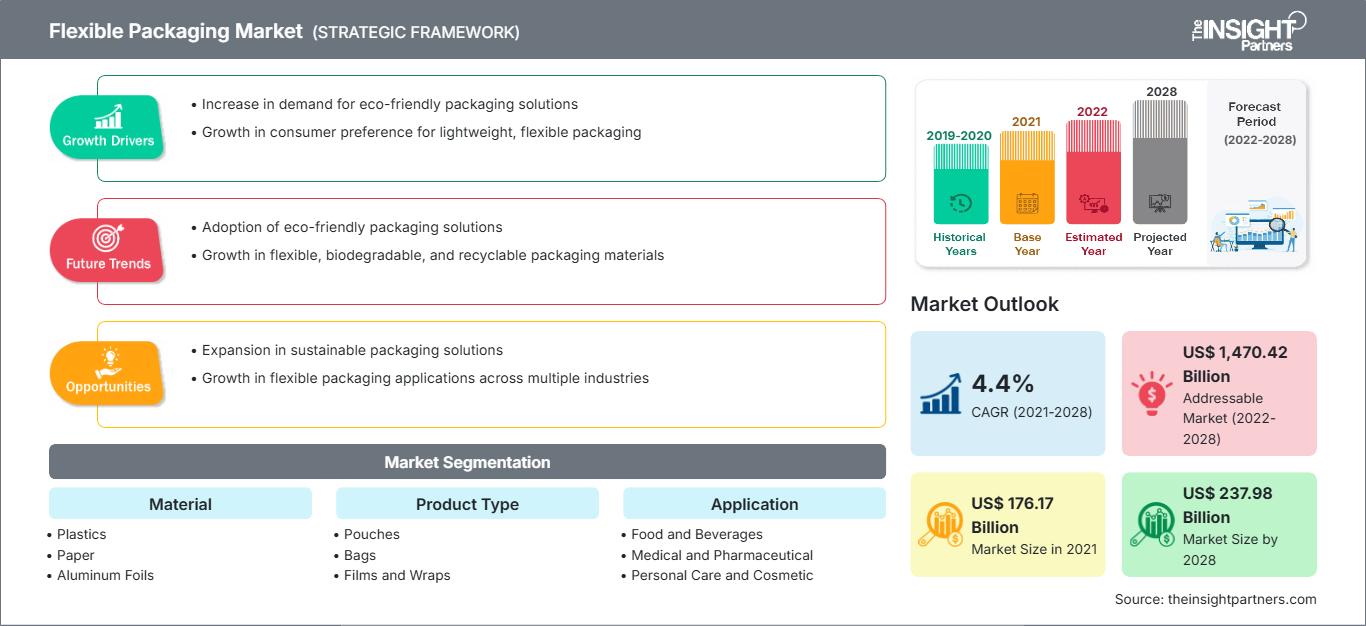
The Flexible Packaging Market is valued at US$ 207.40 Billion in 2025 and is projected to reach US$ 310.73 Billion by 2034, registering a CAGR of 4.6% during 2026–2034. The market encompasses plastic, paper, and aluminum foil formats converted into pouches, bags, films, and wraps for food and beverages, healthcare, personal care, cosmetics, and industrial applications, with sustainability, lightweighting, convenience, and material efficiency shaping purchasing decisions.
It is expected that the growth of North America will proceed steadily due to effective food processing, healthcare packaging, and some flexible replacement of rigid packages. Compound annual growth rate in this region will be around 4.1-4.5% from 2026 till 2034. The growth of the Flexible Packaging Market Size will be supported by innovations in sustainable designs, post-consumer recycling, high-barrier films, and automated pouching systems.
Flexible Packaging Market Assessment and Insights
- North America: North America is projected to account for a 26–30% share in 2025 and grow at a CAGR of 4.1–4.5% between 2026–2034, supported by food, healthcare, convenience packaging, and recyclable film adoption.
- US: The US represents approximately 78–82% of North America's 2025 market and is expected to expand at a 4.0–4.4% CAGR between 2026–2034, led by food and pharmaceutical packaging.
- Europe: Europe is estimated at a 24–27% share in 2025, with Germany, the UK, France, Italy, and Spain supporting development and a 4.0–4.4% CAGR between 2026–2034 through circularity investments and packaging regulation.
- Asia Pacific: Asia Pacific holds approximately 39–42% in 2025 and is expected to register a 5.1–5.6% CAGR between 2026–2034, led by China, India, Japan, and South Korea as packaged consumption and manufacturing capacity expand.
- Largest Segment: Plastics represent the largest material segment, with a 55–60% market share in 2025 and a 4.4–4.8% CAGR between 2026–2034, supported by lightweight, barrier, and converting advantages.
- High Growth Segment: Medical and Pharmaceutical applications hold a 10–14% share in 2025 and are projected to achieve a 5.5–6.2% CAGR between 2026–2034 as sterile and protective formats gain adoption.
- Key companies analyzed in detail: Amcor plc, Huhtamaki Oyj, Mondi plc, Berry Global Group, Inc., Sealed Air Corporation, Sonoco Products Company, Coveris Management GmbH, Constantia Flexibles Group GmbH, FlexPak Services, and Transcontinental Inc.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The Flexible Packaging Market has shifted from traditional multilayer structures to lightweight, better barriers, and more sustainable recyclable alternatives. Innovations in extrusion, coating, lamination, flexography, and digital printing have enabled converters to increase their options and reduce waste. Mono-material PE and PP constructions are gaining increasing traction in regions where recycling facilities exist. More automation is allowing converters to reduce changeovers, better registration, less waste, and more custom designs for brand owners.
Future innovations will focus on recyclable constructions, incorporation of recycled content, barrier coatings, and package design for new collection methods. Asia Pacific will remain key for capacity growth due to its manufacturing and consumer markets. Europe will place emphasis on sustainability through circularity and regulation. North American producers will likely focus on high-performing recyclable films and healthcare packaging. Future investments will increasingly go towards technologies that balance downgauging, barrier technology, machinability, and end of life.
Flexible Packaging Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 207.40 Billion |
| Market Size by 2034 | US$ 310.73 Billion |
| Global CAGR (2026 - 2034) | 4.6% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Flexible Packaging Market Analysis
The demand side is supported by the food & beverages category, convenience packagings, extending shelf life, and logistics advantages provided by light weight packaging. The Flexible Packaging Market expansion is intimately connected with the value chain consisting of polymer/paper makers, foil manufacturers, converters, printers, laminators, pouches, filling equipment makers, retailers, and consumer brands. Food processors are looking for barrier technologies for protecting aroma, moisture, oxygen sensitive and ready-to-eat food products.
Supply-side trends will depend on cost of resin, price of paper/foil/aluminum, energy, printing capabilities, and availability of recycled materials. Flexible packaging companies that have all these processes within their facilities can be more responsive to changes in specification requirements. The healthcare application calls for more stringent process control and traceability. Food packaging calls for more migration control and sealability.
Sustainability engineering is becoming a key factor in competitive positioning rather than capacity alone. According to the Flexible Packaging Market report, Amcor plc, Huhtamaki Oyj, Mondi plc, Berry Global Group, Inc., and Constantia Flexibles Group GmbH compete on the basis of their global coverage, materials engineering, and custom solutions. Meanwhile, the focus of Coveris Management GmbH lies on European converting, whereas Sealed Air Corporation enjoys solid positions in food protection and flexible food packaging.
Investment flows become more focused on recyclable films, mono-material laminates, PCR solutions, printing and converting technologies. Transcontinental Inc. holds a significant presence in the North American flexible packaging market, while FlexPak Services provides custom converting services. Sonoco Products Company has limited its direct participation in the market of flexible packaging due to recent portfolio management. Technical support and regulatory compliance become increasingly important factors in competitive positioning.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Flexible Packaging Market: Strategic Insights
Regional Insights
North America Flexible Packaging Market
North America is forecast to account for 26-30% of the Flexible Packaging Market Share in 2025 and is projected to see CAGR growth of 4.1-4.5% through 2034. US leads regional consumption driven by food packaging, frozen food packaging, snack packaging, beverage packaging, pharmaceutical, personal care, and institutional food service applications. Canada provides growth through food processing and specialty packaging, while Mexico benefits from manufacturing synergy and nearshoring.
Regional converters are developing their capabilities in high barrier structures, recyclable films, digital print, and pouch automation. Attention to recycled content and extended producer responsibility regulations is driving the redesign of packaging specifications. Healthcare provides an additional growth channel as packaging requirements for pharmaceuticals and medical products need controlled barrier and sealing capabilities. Good retail network, significant food manufacturing operations, and converting facilities are likely to maintain North America as an important premium market through 2034.
U.S. Flexible Packaging Market
The United States constitutes about 78–82% of the 2025 market in North America and is anticipated to experience growth of 4.0–4.4% CAGR from 2024 to 2034. The size of the United States market is fueled by leading food processors, pharmaceutical companies, consumer goods producers, and well-established packaging converters operating in the country's national distribution network.
Some of the key players with significant presence in the market include Amcor plc, Sealed Air Corporation, Sonoco Products Company, Berry Global Group, Inc., and Transcontinental Inc., but the portfolio positions vary due to recent changes within the companies. The key applications covered in this research include pouches, films, bags, lidding systems, and vacuum packing. Some key demand segments are retail food, ready-made meals, pet food, healthcare, and personal care.
Europe Flexible Packaging Market
Europe holds a 24–27% share in 2025 and is expected to grow at a 4.0–4.4% CAGR till 2034. The market is dominated by Germany, followed by the UK, France, Italy, and Spain. Regulatory standards, recycling infrastructure, and need for material-efficient packaging drives the investments of converters in this region.
Germany has the advantage of high packaging manufacturing capability, food processing facilities, and machinery capability. In the UK, there is a growing emphasis on incorporating recycled content and tax compliance in packaging. France has its focus on recycling and material-efficient structures, whereas Italy is strong in packaging and food packaging converting. Spain is moving towards flexible packaging in the area of food, beverages, and consumer goods.
APAC Flexible Packaging Market
APAC is estimated at 39–42% of the 2025 market and should record a 5.1–5.6% CAGR through 2034. China is the leading market, followed by Japan, South Korea, India, and Australia. Manufacturing scale, urbanization, packaged-food consumption, and export production support demand.
While China possesses both high conversion capabilities and large consumer base, Japan and South Korea focus on high performance films and superior packaging solutions. India has taken advantage of the growing packaged foods, pharmaceuticals, and personal care. Australia concentrates on recyclable materials and material efficiency. The regional policy initiatives along with increased investment in recycling will drive capacity growth in the region.
Middle East & Africa Flexible Packaging Market
Middle East and Africa provide a small regional platform, yet offer continued growth, with Saudi Arabia, UAE, and South Africa as key markets in the region. The region is estimated to grow at a CAGR of 4.3-4.8% until 2034, driven by food processing, consumer goods, healthcare, and infrastructure developments.
Industrial diversification and food manufacturing in Saudi Arabia, coupled with the UAE being a regional re-export hub, and South Africa being able to manufacture packaging for food, beverages, and households is the driving force for growth in the region. Infrastructure developments in addition to increasing modern retail platforms drive efficient packaging solutions such as bags, films, and pouches.
Segmentation Analysis
Material
The Material segment is expected to expand at a 4.3–4.7% CAGR during 2026–2034. Material selection is governed by barrier requirements, sealing performance, cost, recyclability, printability, and compatibility with filling equipment. Plastics remain dominant because they provide broad processing flexibility, while paper and aluminum foils occupy specialized roles requiring tactile appeal, stiffness, or superior barrier properties.
- Plastics: Plastics remain the principal material because PE, PP, PET, and specialty polymers provide lightweight construction, strong sealing, barrier customization, and compatibility with high-speed converting and filling systems.
- Paper: Paper-based structures are gaining strategic importance where brands seek renewable material positioning and reduced fossil-plastic content, particularly for dry foods, bakery products, bags, and selected consumer applications.
- Aluminum Foils: Aluminum foils serve demanding applications requiring exceptional barrier protection against light, oxygen, and moisture, supporting pharmaceuticals, coffee, dairy, confectionery, and other sensitive products.
Product Type
Product Type is projected to register a 4.5–4.9% CAGR during 2026–2034. Product selection increasingly reflects convenience, dispensing requirements, shelf presentation, filling efficiency, and storage economics. Pouches are gaining application breadth, while films and wraps remain essential for high-volume food and industrial packaging.
- Pouches: Pouches provide strong convenience, resealability, portion control, and lightweighting benefits, making them strategically important for prepared foods, sauces, pet food, beverages, healthcare products, and personal care formulations.
- Bags: Bags support high-volume applications across food, agriculture, household products, and industrial goods, with material and closure choices enabling different load-bearing, moisture-barrier, and handling requirements.
- Films and Wraps: Films and wraps remain foundational packaging formats, serving overwrap, flow-wrap, lidding, shrink, stretch, and form-fill-seal applications where high throughput and controlled material consumption are priorities.
Application
The Application segment is projected to expand at a 4.7–5.1% CAGR during 2026–2034. Demand varies according to product sensitivity, regulatory requirements, shelf-life targets, convenience expectations, and branding needs. Healthcare applications are developing rapidly, while food and beverages continue providing the broadest volume base.
- Food and Beverages: Food and beverage applications represent the principal consumption base, using flexible formats for freshness, barrier protection, portioning, convenience, transportation efficiency, and shelf presentation across numerous packaged-product categories.
- Medical and Pharmaceutical: Medical and pharmaceutical packaging requires stringent barrier performance, cleanliness, traceability, seal integrity, and product protection, making specialized films, pouches, sachets, and laminates strategically valuable.
- Personal Care and Cosmetic: Personal care and cosmetic brands use flexible formats for portability, dispensing, refill concepts, premium decoration, and product differentiation, with sustainability increasingly influencing material and structure selection.
- Industrial: Industrial applications use flexible packaging for chemicals, construction materials, agricultural products, components, and bulk goods where puncture resistance, moisture protection, load performance, and efficient transport are important.
Opportunity Snapshot
| Application | Revenue Contribution | Trend Tag | Adoption Stage |
|---|---|---|---|
| Food and Beverages | High | Barrier Films | Mature |
| Medical and Pharmaceutical | Medium | Sterile Pouches | Scaling |
| Personal Care and Cosmetic | Medium | Refill Pouches | Scaling |
| Industrial | Medium | Heavy-Duty Films | Mature |
Flexible Packaging Market Growth Drivers and Impact Analysis
Expansion of Recyclable and Mono-Material Structures
The transition toward recyclable mono-material structures is becoming a major investment priority because brand owners increasingly need packaging that aligns performance with evolving circularity requirements. PE and PP structures can simplify material composition compared with conventional multilayer designs, although barrier performance and machinability remain technical constraints. Converters are therefore investing in coatings, tie layers, sealant technologies, and process optimization to retain functionality while improving recyclability. The impact extends across resin selection, extrusion, printing, lamination, and qualification procedures. Companies capable of producing structures that run efficiently on existing filling equipment can shorten commercialization cycles for brand customers. This trend also encourages collaboration among resin suppliers, converters, recyclers, equipment manufacturers, and consumer-goods companies.
Growth of Convenience-Oriented Food and Beverage Formats
Changing consumption patterns are increasing the strategic value of lightweight, portable, resealable, and portion-controlled packaging. Prepared meals, sauces, snacks, pet food, coffee, dairy products, and convenience foods increasingly require formats that combine product protection with ease of use. Pouches and flexible films can reduce package weight and storage requirements compared with several rigid alternatives, improving distribution economics. The impact is particularly significant for products requiring high-volume retail replenishment, where transportation and warehouse efficiency influence total packaging costs. Brand owners also value large printable surfaces for product communication and differentiation. As food processors automate filling and sealing, suppliers with compatible film structures and reliable seal performance can gain opportunities to participate in long-term packaging programs.
Increasing Pharmaceutical and Healthcare Packaging Requirements
Healthcare packaging is creating demand for specialized flexible structures with controlled barrier properties, high seal reliability, clean manufacturing environments, and traceability. Pharmaceutical products may require protection from moisture, oxygen, light, contamination, or physical damage, creating opportunities for engineered laminates and high-performance films. Growth in healthcare consumption across Asia Pacific and other emerging markets expands the addressable customer base, while established markets continue demanding compliance-oriented packaging systems. The market impact extends beyond materials because qualification, testing, documentation, and production consistency become critical purchasing criteria. Converters that can provide technical validation and stable global supply are better positioned for pharmaceutical contracts. This application also supports higher-value products because performance and compliance can outweigh simple material-cost considerations.
Flexible Packaging Market Future Trends
Data-Enabled Packaging Development and Digital Converting
Digital technologies are expected to influence packaging development by enabling shorter print runs, faster artwork changes, variable content, and more responsive production planning. Digital printing can support customization without requiring the same plate infrastructure associated with conventional printing, improving economics for targeted campaigns and smaller production batches. Over the forecast period, converters may increasingly combine digital decoration with automated inspection, predictive maintenance, and connected production systems. This could improve quality consistency while reducing waste associated with setup and changeovers. Data-driven production will also help manufacturers compare material utilization, machine efficiency, and defect rates across product lines. The resulting competitive advantage will favor converters capable of integrating digital workflows without compromising food safety, print quality, or high-speed filling performance.
Advanced Barrier Technologies for Lower-Material Structures
Future packaging development in the Flexible Packaging Market Trends is likely to emphasize coatings and surface treatments that deliver stronger oxygen, moisture, aroma, and light barriers without requiring heavy multilayer constructions. This direction is important because downgauging alone can reduce material use but may compromise shelf life if barrier performance declines. Advanced coatings, metallization approaches, and polymer engineering can help maintain protection while reducing overall structure complexity. Research is also likely to focus on recyclable barrier layers compatible with PE or PP recycling streams. As brand owners evaluate packaging through both product-protection and end-of-life criteria, suppliers that can demonstrate measurable performance across the complete package lifecycle will gain strategic relevance. These technologies can also support high-value applications such as pharmaceuticals, coffee, dairy, and sensitive foods.
Flexible Packaging Market Opportunities
Localized Production for Emerging Consumer Markets
Investment in localized flexible packaging production offers opportunities in India, Southeast Asia, Latin America, the Middle East, and selected African markets where packaged consumption is expanding. Local converting capacity can reduce transport distances, shorten lead times, and allow packaging suppliers to adapt specifications to regional filling equipment and consumer preferences. Investors can target integrated plants combining film extrusion, printing, lamination, slitting, and pouch production, thereby improving supply-chain control. Partnerships with food, pharmaceutical, and personal-care manufacturers can provide anchor demand during capacity ramp-up. Opportunities are particularly attractive where modern retail penetration is increasing and domestic manufacturing policies encourage local value addition. However, project economics should account for resin availability, recycling infrastructure, skilled labor, energy reliability, and regulatory requirements.
Recycling-Compatible Packaging Platforms
Companies can create investment opportunities by developing platforms that allow customers to migrate from conventional structures to recyclable formats with limited changes to existing filling and sealing equipment. Such solutions require more than material substitution because seal windows, stiffness, barrier performance, printing, and machinability must remain acceptable. Suppliers can differentiate through application-specific qualification programs, technical support, and structured conversion road maps. Partnerships with recyclers can strengthen claims regarding collection and processing compatibility, while PCR integration can address customer requirements for recycled content. Commercial opportunities in the Flexible Packaging Market Forecast should focus on high-volume categories where redesign can be standardized across multiple products. Food, pet food, personal care, and selected industrial applications offer potential because brand owners frequently manage large packaging portfolios that can benefit from platform-based material solutions.
Recent Developments
- September 2025: New flexible packaging solutions were launched for pharmaceutical and food applications, reflecting the industry's shift toward packaging formats that combine product protection, functional performance, and application-specific requirements. The development highlights continued innovation in flexible structures for demanding food and pharmaceutical packaging uses.
- June 2026: Siegwerk completed its acquisition of Hi-Tech Inks, creating India’s largest flexible packaging inks business with more than 20% market share. The combined operation adds manufacturing facilities in Bhiwadi, Rajasthan, and Vapi, Gujarat, and expands its portfolio across solvent- and water-based inks, metallic and specialty inks, varnishes, and overprint varnishes.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners provided valuable market intelligence that supported our global go-to-market strategy. Their team was professional, responsive, and attentive to our feedback, providing thoughtful analysis and helpful methodological clarifications throughout the project.
Junmo Kim Chief Financial Officer (CFO), Enertech Co., Ltd.
The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for