
Aluminum Casting Market Size, Growth & Demand by 2034
Coverage: By Process (Die Casting, Permanent Mold Casting, Sand Casting); End Use Industry (Transportation, Building and Construction, Industrial, Others) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00009480
- Category : Chemicals and Materials
- No. of Pages : 150
- Available Report Formats :


- Last update date : August 17, 2026


2025 Market Size
US$ 111.14 Bn
Base year value
2034 Forecast
US$ 165.92 Bn
Projected by 2034
CAGR 2026-2034
4.55 %
Growth rate
Addressable Market
US$ 1,257.75 Bn
(2026-2034)
The aluminum casting market was valued at US$ 111.14 billion in 2025 and is projected to reach US$ 165.92 billion by 2034, registering a CAGR of 4.55% during 2026–2034. The industry keeps profiting from the growing replacement of ferrous metals with lightweight aluminum castings in applications ranging from transportation to industrial machines and construction equipment, as well as engineered products. Progress in casting techniques, new alloy design, and process automation help to boost productivity and quality of aluminum cast parts.
North American manufacturers keep investing in lightweight car parts, aerospace parts, and energy-saving industrial equipment, thus raising the demand for aluminum casting products in the region. In North America, the aluminum casting market size will grow at the CAGR of 4.0–4.5% over the forecast period due to the growing number of electric vehicles, reshoring production processes, and high-pressure die casting of large aluminum parts.
Aluminum Casting Market Assessment and Insights
- North America: Accounted for 24–27% share in 2025 and is projected to grow at a CAGR of 4.0–4.5% during 2026–2034. Strong automotive production, aerospace investments, and modernization of industrial manufacturing continue supporting regional demand for precision aluminum castings.
- U.S.: Represented 74–78% of North American demand in 2025 and is anticipated to register a CAGR of 4.1–4.6% through 2034, supported by electric vehicle manufacturing, defense programs, and increasing domestic casting capacity.
- Europe: Held 22–25% share in 2025 and is forecast to expand at a CAGR of 3.8–4.3% during 2026–2034. Germany, Italy, France, and the UK remain leading production hubs driven by automotive engineering, industrial machinery, and sustainable manufacturing initiatives.
- Asia Pacific: Captured 41–44% share in 2025 and is expected to record the highest regional CAGR of 5.2–5.7% during 2026–2034, supported by expanding automotive production, infrastructure investments, and strong manufacturing growth across China, India, Japan, and South Korea.
- Largest Segment – Process: Die Casting: Held 58–62% market share in 2025 and is expected to register a CAGR of 4.8–5.2% owing to its suitability for high-volume manufacturing, dimensional precision, and lightweight structural applications.
- High Growth Segment – End Use Industry: Transportation: Accounted for 44–48% share in 2025 and is projected to expand at a CAGR of 5.1–5.6%, supported by electric vehicles, lightweight mobility platforms, commercial vehicles, and railway modernization.
- Key companies analyzed in detail: Alcoa Corporation, Dynacast, Walbro LLC, Alcast Technologies Ltd., Aluminum Corporation of China Limited (CHALCO), Gibbs Die Casting Corporation, Ryobi Limited, Kaiser Aluminum Corporation, Martinrea Honsel Germany GmbH, Bodine Aluminum, Inc.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The increased use of lightweight engineering material has greatly changed manufacturing considerations throughout all manufacturing sectors around the world. The use of high-pressure die casting, vacuum casting, automated mold handling, and digital inspection has helped increase productivity and minimize the amount of scrap produced. The growing demand for complicated structural parts for electric cars, airplanes, renewable energy systems, and industrial machinery is still inspiring investments in more advanced aluminum foundries that can make highly integrated parts with improved mechanical properties.
Future growth is likely to come from Southeast Asian, Indian, Mexican, Eastern European, and chosen Middle Eastern manufacturing centers as multinational manufacturers diversify their supply chains. Government initiatives supporting domestic manufacturing, lightweight transport solutions, recycling programs, and industrial decarbonization are likely to encourage investments in new aluminum foundries with automated, artificial intelligence-based quality inspection and efficient melting technology.
Aluminum Casting Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 111.14 Billion |
| Market Size by 2034 | US$ 165.92 Billion |
| Global CAGR (2026 - 2034) | 4.55% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Aluminum Casting Market Analysis
With growing need for lighter materials in the transportation, machinery, renewable energy, and construction industries, the global aluminum casting market continues to grow at a faster pace. The supply chain consists of the aluminum producers, recyclers of aluminum, alloys manufacturers, foundries, machining companies, component assemblers, and OEMs. With increased availability of recyclable aluminum and use of sustainable aluminum smelting technologies, there have been improvements in the raw material’s sustainability without impacting its mechanical properties.
The dynamics of supply continue to change as the manufacturers tend to localize their supply chains after the supply chain issues faced recently. With automation technologies, robotic handling, simulation software, and predictive maintenance technologies, there have been advancements in the efficiency of production with reduced waste generation. The increasing use of giga-casting technologies in the manufacturing of electric vehicles increases the need for high-capacity aluminum casting machines.
The competitive intensity in the aluminum casting market report is still high since the players emphasize their technological uniqueness, growth in capacity, sustainability, and cooperation with OEMs for a long term. The companies like Alcoa Corporation, Dynacast, Aluminum Corporation of China Limited, Ryobi Limited, Gibbs Die Casting Corporation, and Martinrea Honsel Germany GmbH keep on innovating in developing lightweight alloys, automatic manufacturing lines, and recycling processes to enhance their competitive position. Collaboration between the aluminum companies and automotive companies plays an important role in developing new generation structural castings in electric mobility.
In the current situation, investments go into the digital foundry that can produce value-added precision castings with enhanced accuracy and decreased energy usage. The companies like Kaiser Aluminum Corporation, Bodine Aluminum, Inc., Walbro LLC, and Alcast Technologies Ltd. keep on innovating in manufacturing process optimization, sustainability, and quality assurance. At the same time, companies introduce simulation-based mold designs, AI-based defect detection process, and recycling process into their manufacturing operations.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
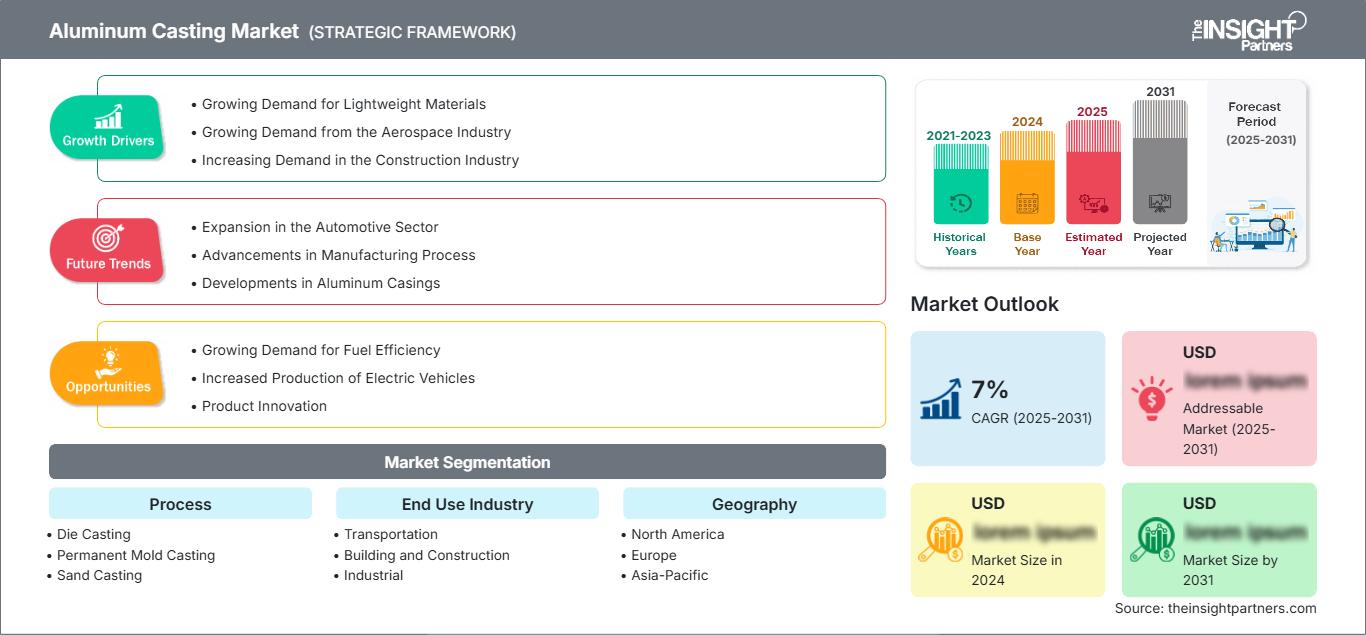
Aluminum Casting Market: Strategic Insights
Regional Insights
North America Aluminum Casting Market
North America had a aluminum casting market share of 28–32% in 2025 and is expected to grow at a CAGR of 4.2–4.6% from 2026–2034. Robust automobile manufacturing, aerospace manufacturing, and rising investment in lightweight industrial machinery keep driving regional demand. The USMCA agreement is in favor of regional manufacturing integration, whereas aluminum's recyclable properties match the sustainability goals that have been set in the transportation industry as well as the industrial sector.
Manufacturers keep growing their high-pressure die casting capacity for batteries, bodies, and vehicles. Rising defense spending, aircraft upgrades, and infrastructure development keep fueling the demand for casting in the United States, Canada, and Mexico. The availability of leading aluminum manufacturers, automobile makers, and suppliers keeps pushing technological innovations and ensures supply of raw materials.
U.S. Aluminum Casting Market
In 2025, the U.S. was estimated to have a market share of 73–77%, and its CAGR from 2026 to 2034 was estimated to be 4.3–4.7%. The demand in the region would come from the applications like automotive lightweighting, aerospace components, and industrial machinery production. Investments that will take place with support from the Inflation Reduction Act and domestic manufacturing programs are expected to drive the capacity growth in advanced aluminum parts.
Manufacturers of electric vehicles are becoming more interested in large aluminum castings, which are used to facilitate easy vehicle assembly with reduced weight. Growth in giga casting, recycling, and investments made by suppliers are helping to strengthen the domestic manufacturing capabilities. Modernization of foundries with automation, simulation, and robotics continues.
Europe Aluminum Casting Market
Europe was a 24-28% share in 2025, which is expected to grow at a CAGR of 4.0-4.4% between 2026 and 2034. The demand for aluminum castings will increase owing to vehicle emissions standards, circular economy initiatives, and advanced manufacturing processes in the application areas of automobiles, industrial machinery, and engineering, with Germany being the leading country in Europe.
The manufacturing of aerospace components, luxury automobiles manufacturing, and investment in low-carbon aluminum manufacturing technologies will benefit the United Kingdom. The future development of electric mobility and decarbonization measures in various industries will ensure stable demand for light-weight castings.
Germany will remain the largest aluminum casting producing country in Europe owing to its highly developed automotive value chain, mechanical engineering industry, and casting firms. Investments in automated foundries, giga casting, and recycled aluminum processing will provide a competitive advantage for the country.
France, Italy, and Spain will provide significant regional demand through automotive manufacturing, industrial equipment, rail infrastructure, and renewable energy. Growing use of recycled aluminum alloys and sustainable manufacturing investments will fuel market growth in Southern Europe.
APAC Aluminum Casting Market
Asia Pacific accounted for 39–43% share in 2025 and is forecast to register the fastest regional expansion with a CAGR of 5.1–5.5% during the forecast period. China dominates regional production owing to its integrated aluminum supply chain, extensive automotive manufacturing, and large industrial equipment sector. Japan, South Korea, and India continue expanding precision casting capacity for transportation and engineering applications.
Government support for electric vehicles, renewable energy infrastructure, and industrial modernization continues strengthening regional demand. Australia contributes through mining equipment and resource processing industries, while Southeast Asian manufacturing expansion further enhances regional casting production capabilities.
Middle East & Africa Aluminum Casting Market
The Middle East & Africa market is projected to grow at a CAGR of 4.4–4.8% through 2034. Saudi Arabia and the UAE continue investing in downstream aluminum processing, supported by abundant primary aluminum production and industrial diversification initiatives. Growing manufacturing activity is creating additional opportunities for value-added cast products.
South Africa remains an important regional manufacturing hub serving automotive and industrial equipment industries. Infrastructure development, energy diversification projects, and increasing localization of industrial production are expected to gradually strengthen aluminum casting demand across the broader Middle East & Africa region.
Segmentation Analysis
Process
The Process segment is projected to expand at a CAGR of 4.5–4.9% during 2026–2034. The aluminum casting market scope continues to broaden as manufacturers increasingly adopt advanced casting processes to improve dimensional accuracy, reduce machining requirements, and produce lightweight yet high-strength components. Process selection depends on production volume, component complexity, alloy characteristics, and end-use requirements across transportation, industrial equipment, and construction applications.
- Die Casting – The largest process segment owing to its ability to manufacture high-volume, dimensionally accurate, and complex components with excellent surface finish. It is extensively used for automotive powertrain, structural, electronics, and industrial machinery applications requiring consistent quality and production efficiency.
- Permanent Mold Casting – Preferred for medium-volume production where superior mechanical properties and improved surface quality are required. The process supports manufacturing of aerospace components, industrial equipment, pumps, valves, and commercial transportation parts with enhanced durability and reduced porosity.
- Sand Casting – Widely utilized for large, customized, and low-volume components because of its design flexibility and lower tooling investment. Heavy machinery, construction equipment, marine systems, and industrial engineering applications continue to generate stable demand for this process.
End Use Industry
The End Use Industry segment is anticipated to register a CAGR of 4.7–5.1% through 2034. Demand is primarily supported by transportation electrification, infrastructure modernization, and industrial automation. Aluminum cast components continue replacing heavier materials due to their excellent strength-to-weight ratio, corrosion resistance, and recyclability, supporting efficiency improvements across multiple industries.
- Transportation – The dominant end-use industry driven by passenger vehicles, commercial vehicles, electric vehicles, railways, marine, and aerospace applications. Manufacturers increasingly adopt aluminum castings to reduce vehicle weight, improve fuel economy, extend battery range, and comply with stricter emission regulations.
- Building and Construction – Aluminum cast products are increasingly incorporated into structural hardware, architectural systems, building equipment, and infrastructure projects because of their corrosion resistance, durability, and low maintenance requirements. Sustainable building initiatives continue supporting long-term demand.
- Industrial – Industrial equipment manufacturers utilize aluminum castings in pumps, compressors, motors, machine tools, robotics, agricultural machinery, and energy systems. Growing factory automation, renewable energy deployment, and modernization of manufacturing facilities continue supporting steady consumption.
Opportunity Snapshot
| End Use Industry | Revenue Contribution | Trend Tag | Adoption Stage |
|---|---|---|---|
| Transportation | High | EV Lightweighting | Mature |
| Building and Construction | Medium | Green Buildings | Scaling |
| Industrial | High | Smart Manufacturing | Scaling |
Aluminum Casting Market Growth Drivers and Impact Analysis
Increasing Adoption of Lightweight Components in Transportation
Growing demand for lightweight materials across automotive, electric vehicles, aerospace, and commercial transportation sectors is significantly influencing aluminum casting adoption. Vehicle manufacturers are replacing conventional steel components with aluminum cast parts to reduce overall weight, improve energy efficiency, and enhance driving range in electric vehicles. Large-scale adoption of structural castings, battery housings, and integrated vehicle components is encouraging investments in advanced die casting technologies. The shift toward vehicle electrification is further accelerating demand for complex aluminum components with improved mechanical performance and manufacturing precision. This trend is expected to strengthen supplier relationships between aluminum producers, casting companies, and automotive manufacturers while supporting continuous process innovation across transportation applications.
Expansion of Electric Vehicle Manufacturing and Giga-Casting Technologies
The rapid expansion of electric vehicle production is creating new opportunities for advanced aluminum casting solutions, particularly through the adoption of large-scale casting technologies. Automakers are increasingly utilizing integrated aluminum structures to reduce assembly complexity, minimize component count, and improve manufacturing efficiency. Giga-casting enables production of larger vehicle sections through single-piece cast components, reducing welding requirements and production time. Increasing investments by automotive OEMs and Tier-1 suppliers in dedicated EV manufacturing facilities are encouraging casting companies to upgrade equipment, develop advanced alloys, and implement digital manufacturing systems. These developments are reshaping supply chains by increasing demand for high-precision casting capabilities and specialized aluminum alloys designed for next-generation mobility applications.
Rising Demand for Recycled Aluminum and Sustainable Manufacturing
Sustainability initiatives across industries are accelerating the adoption of recycled aluminum in casting operations due to its lower energy requirements compared with primary aluminum production. Manufacturers are increasingly integrating closed-loop recycling systems to improve material efficiency, reduce production costs, and meet corporate sustainability targets. Automotive and industrial customers are prioritizing suppliers capable of providing low-carbon aluminum components with traceable material sourcing. Regulatory emphasis on circular economy practices, particularly in Europe and North America, is encouraging investments in recycling infrastructure and energy-efficient foundry operations. The increasing availability of recycled aluminum feedstock is supporting sustainable casting practices while enabling manufacturers to maintain product performance and competitiveness across transportation, construction, and industrial applications.
Aluminum Casting Market Future Trends
Integration of Artificial Intelligence and Digital Foundry Technologies
The aluminum casting market trends are expected to be shaped by increased adoption of artificial intelligence, predictive analytics, and digital manufacturing platforms. Foundries are implementing smart sensors, real-time monitoring systems, and simulation technologies to optimize casting parameters, reduce defects, and improve production consistency. Digital twins are enabling manufacturers to evaluate component performance before physical production, reducing development cycles and material waste. As demand increases for complex automotive and industrial components, advanced process control will become essential for maintaining quality standards. The combination of automation, data analytics, and robotics is expected to transform traditional casting operations into highly efficient, connected manufacturing environments capable of supporting customized production requirements.
Development of Advanced Aluminum Alloys for High-Performance Applications
Aluminum casting manufacturers are increasingly focusing on developing advanced alloys with improved strength, thermal resistance, corrosion performance, and fatigue properties. These materials are expected to support growing demand from electric vehicles, aerospace systems, renewable energy equipment, and industrial machinery. Research efforts are concentrated on improving alloy compositions to enable lightweight designs without compromising durability. Future alloy innovations will support the production of larger structural components, battery-related parts, and precision-engineered products. Increasing collaboration between material suppliers, casting companies, and end-use manufacturers is expected to accelerate commercialization of next-generation aluminum alloys. These advancements will expand application opportunities and improve the competitiveness of aluminum compared with alternative materials.
Aluminum Casting Market Opportunities
Expansion of Aluminum Casting Capacity for Electric Mobility Components
The increasing transition toward electric mobility creates significant opportunities for casting manufacturers to expand production capabilities focused on EV-specific components. Investment opportunities exist in high-pressure die casting facilities, advanced alloy development, and automated manufacturing systems designed for battery trays, motor housings, and structural vehicle components. Companies developing expertise in large-format casting technologies can benefit from increasing partnerships with automotive OEMs seeking localized supply chains. Aluminum Casting Market Forecasts indicate that continued EV production growth will encourage manufacturers to establish dedicated facilities near automotive clusters. Strategic investments in recycling capabilities, process automation, and lightweight component engineering can strengthen supplier competitiveness while supporting long-term demand from global transportation markets.
Increasing Adoption of Sustainable Casting Solutions Across Industries
Growing emphasis on carbon reduction and circular economy practices creates opportunities for companies offering low-carbon aluminum casting solutions. Manufacturers can differentiate themselves through recycled aluminum utilization, renewable energy integration, and environmentally optimized foundry operations. Industrial customers, construction companies, and transportation manufacturers are increasingly evaluating suppliers based on sustainability performance alongside technical capabilities. Opportunities exist for developing closed-loop material systems, improving energy efficiency, and providing traceable aluminum supply chains. Companies investing in sustainable technologies can strengthen customer relationships and align with evolving environmental regulations. These initiatives are expected to support long-term market competitiveness while expanding aluminum casting applications across industries seeking durable and recyclable material solutions.
Recent Developments
- October 22, 2025: Alucast Ltd invested approximately £1 million in new machinery and research activities at its Wednesbury facility to strengthen aluminum casting capabilities for rail, aerospace, and defense applications. The investment includes a new low-pressure die casting machine and development of the ALU-HP1 lightweight alloy, designed to deliver high strength while reducing component weight. The initiative reflects increasing demand for advanced aluminum casting solutions across transportation and industrial sectors.
- May 27, 2025: Golden Aluminum Inc.in collaboration with SMS group, commenced commercial operations of its Nexcast aluminum strip casting technology at its Fort Lupton, Colorado facility. The advanced continuous casting system enables direct conversion of molten aluminum into hot-rolled coils while improving production efficiency, alloy flexibility, and sustainability performance. The development highlights increasing industry focus on next-generation casting technologies to reduce processing steps and enhance resource efficiency.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for