
Attack Surface Management Market Trends, Share & Demand by 2034
Attack Surface Management Market Size and Forecasts (2021 - 2034), Global and Regional Share, Trends, and Growth Opportunity Analysis Report Coverage : By Offering (Solutions, Services), Deployment Mode (Cloud, On-premises), Organization Size (Large Enterprises, SMEs), Vertical (BFSI, Healthcare, Retail & E-Commerce and Others)
- Status : Data Released
- Report Code : TIPRE00039731
- Category : Technology, Media and Telecommunications
- No. of Pages : 150
- Available Report Formats :


- Last update date : August 28, 2026


2025 Market Size
US$ 1.08 Bn
Base year value
2034 Forecast
US$ 5.08 Bn
Projected by 2034
CAGR 2026-2034
18.71 %
Growth rate
Addressable Market
US$ 25.23 Bn
(2026-2034)
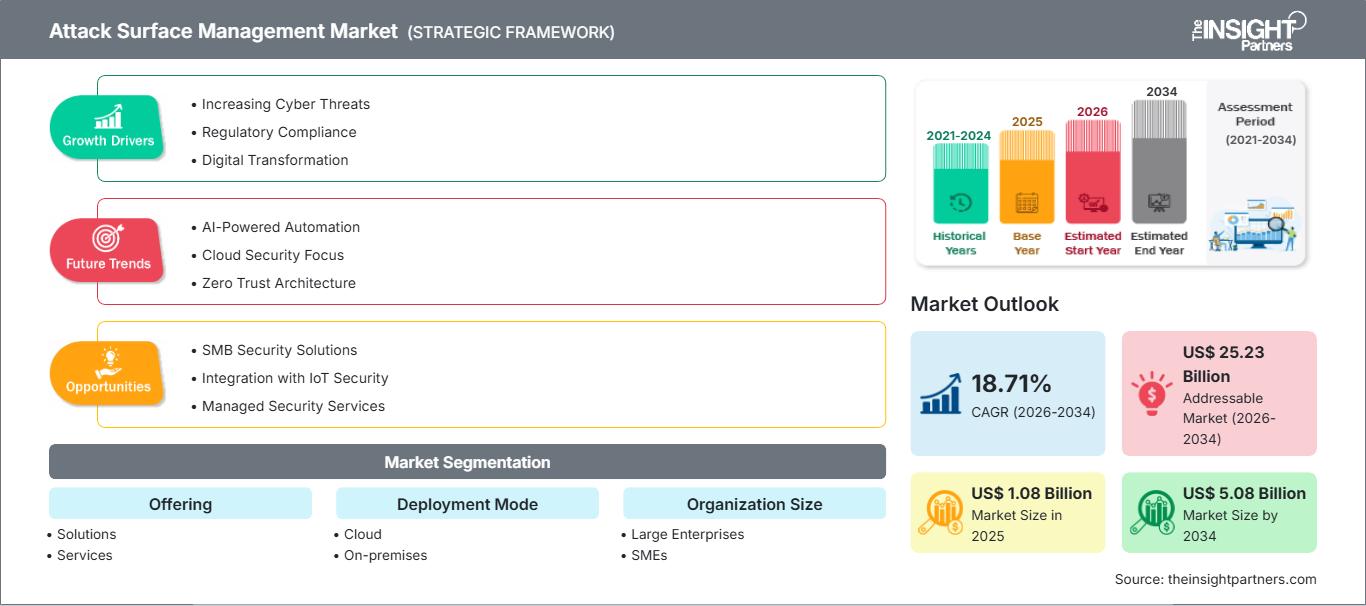
The Attack surface management market was valued at US$ 1.08 Billion in 2025 and is projected to reach US$ 5.08 Billion by 2034, expanding at a CAGR of 18.71% during 2026–2034. Growing enterprise digitalization, increasing adoption of hybrid cloud infrastructure, expanding remote work environments, and the rising sophistication of cyber threats are accelerating investments in continuous external asset discovery and exposure management. Organizations across regulated and non-regulated industries are prioritizing proactive identification of internet-facing assets to strengthen cybersecurity resilience and reduce organizational risk.
Across North America, enterprises continue accelerating investments in cyber exposure management owing to strict regulatory compliance, increasing ransomware incidents, and expanding cloud-native environments. The attack surface management market size in the region is supported by rapid adoption among financial institutions, healthcare providers, and government agencies seeking continuous visibility into digital assets. Growing integration of artificial intelligence with cybersecurity operations and strong spending on managed security services are expected to support a regional CAGR of 17.5–19.0% during the forecast period.
Attack Surface Management Market Assessment and Insights
- North America: Held 36–40% share in 2025 and is expected to grow at a CAGR of 17.5–19.0% during 2026–2034. Mature cybersecurity ecosystems, high cloud adoption, and stringent regulatory frameworks continue driving enterprise investments in external attack surface monitoring.
- US: Accounted for 78–82% of North American revenue in 2025 and is anticipated to register a CAGR of 17.8–19.2% through 2034, supported by expanding cybersecurity investments across BFSI, healthcare, technology, and public sector organizations.
- Europe: Represented 27–31% share in 2025 and is projected to expand at a CAGR of 18.0–19.4%. Germany, the United Kingdom, and France remain leading markets due to stronger cybersecurity regulations, digital transformation initiatives, and increasing cloud adoption.
- Asia Pacific: Captured 22–26% share in 2025 and is forecast to witness the fastest expansion at a CAGR of 20.0–21.8%, led by China, Japan, India, South Korea, and Australia through accelerating enterprise digitalization and government cybersecurity initiatives.
- Largest Segment: Solutions dominated with 67–71% market share in 2025 and are expected to grow at a CAGR of 19.0–20.3%, supported by demand for automated asset discovery, continuous monitoring, and vulnerability prioritization.
- High Growth Segment: Cloud deployment accounted for 60–64% market share in 2025 and is projected to register a CAGR of 19.8–21.2%, driven by scalable SaaS security platforms and expanding hybrid cloud environments.
- Key companies analyzed in detail: Palo Alto Networks, IBM Corporation, Microsoft Corporation, Cisco Systems, Inc., Trend Micro Incorporated, Qualys, Inc., Tenable Holdings, Inc., CrowdStrike Holdings, Inc., Rapid7, Inc., SecurityScorecard Inc.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
Rapid digital transformation has fundamentally changed enterprise cybersecurity priorities by expanding the number of internet-facing assets requiring continuous monitoring. The cloud, remote workers, application transformation, IoT initiatives, and greater reliance on third parties have greatly expanded an organization’s attack surface. Enterprises are turning to exposure management platforms that can detect unknown devices, determine priority vulnerabilities based on risk, and manage vulnerability remediation efforts within a security operations center (SOC).
Market growth will be driven by rising cybersecurity regulations, threat analysis through artificial intelligence, and more investment in integrated cyber risk management platforms. New economies are building out their digital infrastructure using national cybersecurity strategies to spur security modernization at the enterprise level. With the continued expansion of attack surfaces beyond IT environments, organizations will invest in continuous visibility, automated discovery, and predictive risk intelligence.
Attack Surface Management Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 1.08 Billion |
| Market Size by 2034 | US$ 5.08 Billion |
| Global CAGR (2026 - 2034) | 18.71% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Attack Surface Management Market Analysis
Organizations increasingly recognize that traditional perimeter-based security strategies are insufficient for protecting highly distributed digital infrastructures. Attack surface management market growth is therefore being driven by the continuous expansion of cloud applications, unmanaged internet-facing assets, connected operational technology, and remote workforce environments. Enterprises need real-time insight into all external-facing assets to minimize the exposure period and hasten incident response times. The increasing regulatory focus on cyber resiliency also compels businesses to implement an exposure management system that allows them to automatically discover, classify, and prioritize potential vulnerabilities even before attackers use them.
The ecosystem for such technologies consists of technology companies, cloud service providers, managed security service providers, cybersecurity experts, vulnerability intelligence companies, and enterprise security operation centers. Collaboration with endpoint protection systems, security information and event management systems, threat intelligence services, and vulnerability management systems helps enterprises create cyber risk visibility while ensuring efficiency due to automation of the remediation process.
The competitive landscape within the attack surface management market analysis is characterized by continuous innovation surrounding artificial intelligence, attack path analysis, cloud-native security, and integrated exposure management. Vendors, including Palo Alto Networks, Microsoft Corporation, IBM Corporation, Cisco Systems, Inc., Trend Micro Incorporated, Qualys, Inc., Tenable Holdings, Inc., CrowdStrike Holdings, Inc., Rapid7, Inc., and SecurityScorecard Inc. continue expanding platform capabilities through acquisitions, strategic partnerships, and product enhancements that strengthen enterprise cyber resilience.
The trend of investments keeps growing due to the fact that cybersecurity is an important strategic priority of companies. The venture capital investment, mergers and acquisitions pay special attention to such technologies as asset discovery, attack surface intelligence, predictive analytics, and exposure validation. More and more companies tend to prefer cybersecurity platforms that can unite attack surface management with vulnerability assessments, threat detection, identity security, and security operations.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Attack Surface Management Market: Strategic Insights
Regional Insights
North America Attack Surface Management Market
North America accounted for 36–40% of the global attack surface management market share in 2025 and is anticipated to expand at a CAGR of 17.5–19.0% through 2034. The region benefits from mature cybersecurity infrastructure, high cloud adoption, strong enterprise IT spending, and increasingly stringent regulatory frameworks. Ransomware attacks, software supply chain threats, and nation-state cyber operations persist in motivating businesses to adopt continuous attack surface management tools that increase visibility around internet-connected assets and third-party digital environments.
The US and Canada are still making significant investments in artificial intelligence-based cybersecurity tools, zero-trust network architectures, and exposure management platforms. Firms in the financial services, health care, government, tech sector, and critical infrastructures now need automation in discovering unmanaged assets and assessing vulnerabilities continuously. Regulatory mandates related to cybersecurity disclosures, privacy protections, and operational resilience have been in increasing demand among enterprises in almost all industries.
U.S. Attack Surface Management Market
The U.S. represented 78–82% of the North American Attack Surface Management Market revenue during 2025 and is forecast to grow at a CAGR of 17.8–19.2% throughout the study period. Enterprise-level cybersecurity spending is still one of the largest in the world due to growing digital transformation, cloud migrations, ransomware attacks, and highly sophisticated cyber threats that target financial organizations, healthcare providers, governments, and technology firms. Enterprise organizations keep favoring cyber risk management over cybersecurity monitoring.
Some of the major players in the cybersecurity market, such as Microsoft Corporation, Palo Alto Networks, CrowdStrike Holdings, Inc., Rapid7, Inc., Tenable Holdings, Inc., and IBM Corporation, have significant research and development centers located in the country. The increasing use of artificial intelligence, security orchestration, extended detection, and response solutions, and continuous exposure management enhances the maturity of enterprise cybersecurity and increases operational efficiency.
Europe Attack Surface Management Market
Europe captured 27–31% of the global Attack Surface Management Market in 2025 and is projected to register a CAGR of 18.0–19.4% during the forecast period. Strong regulatory frameworks including GDPR and the NIS2 Directive continue encouraging organizations to strengthen cybersecurity governance, digital risk management, and continuous external asset monitoring. Germany remains the regional leader due to its extensive industrial base, advanced manufacturing sector, and strong enterprise cybersecurity investments.
The United Kingdom continues experiencing rapid cybersecurity adoption across banking, government, healthcare, and digital services industries, supported by expanding cloud migration and increasing cyber resilience initiatives. France, Italy, and Spain are witnessing rising investments in critical infrastructure protection, digital public services, financial technology, and enterprise modernization, creating sustained demand for attack surface management platforms capable of identifying emerging cyber risks across increasingly interconnected business environments.
APAC Attack Surface Management Market
Asia Pacific accounted for 22–26% of the global Attack Surface Management Market in 2025 and is expected to record the highest regional CAGR of 20.0–21.8% between 2026 and 2034. Accelerating digital transformation, expanding cloud adoption, and growing cybersecurity awareness continue to support enterprise investments throughout the region.
China leads regional implementation through extensive enterprise digitalization, while Japan emphasizes cyber resilience across manufacturing and financial services. India experiences rapid adoption among IT services and BFSI organizations, whereas South Korea and Australia continue strengthening national cybersecurity frameworks supporting broader enterprise implementation of attack surface management technologies.
Middle East & Africa Attack Surface Management Market
The Middle East & Africa Attack Surface Management Market accounted for 8–10% of the global market in 2025 and is projected to register a CAGR of 19.2–20.8% during 2026–2034. Governments across the region are accelerating cybersecurity investments as digital government initiatives, cloud adoption, and critical infrastructure modernization expand enterprise attack surfaces. Regulatory initiatives and national cybersecurity strategies are encouraging organizations to implement continuous exposure monitoring and automated external asset discovery.
Saudi Arabia leads regional demand through Vision 2030-driven digital transformation and increasing investments in financial services, energy, and public sector cybersecurity. The United Arab Emirates continues to strengthen cyber resilience across smart city and cloud infrastructure projects, while South Africa remains an important market due to growing enterprise digitalization and increasing cybercrime. Across the remaining MEA region, expanding ICT investments and modernization of essential infrastructure continue to create favorable conditions for attack surface management adoption.
Segmentation Analysis
Offering
The Solutions segment accounted for the largest revenue contribution in 2025 and is projected to expand at a CAGR of 19.0–20.3% during the forecast period. Organizations increasingly prioritize automated external asset discovery, attack path visualization, vulnerability prioritization, and continuous monitoring capabilities. The attack surface management market scope continues expanding as enterprises integrate ASM platforms with broader exposure management, threat intelligence, and security operations ecosystems.
- Solutions – Organizations widely deploy software platforms that continuously identify internet-facing assets, prioritize exploitable vulnerabilities, monitor digital risks, and automate remediation workflows across complex enterprise environments.
- Services – Professional consulting, deployment, managed security, integration, and advisory services support enterprises in implementing attack surface management platforms while improving operational efficiency and regulatory compliance.
Deployment Mode
Cloud deployment dominates the market and is expected to register a CAGR of 19.8–21.2% through 2034. Cloud-native platforms provide scalable implementation, centralized visibility, continuous intelligence updates, simplified management, and rapid deployment while supporting increasingly distributed hybrid IT infrastructures.
- Cloud – Cloud-based solutions enable flexible deployment, subscription-based pricing, continuous software updates, and centralized monitoring across geographically distributed digital environments.
- On-premises – Organizations operating highly regulated or security-sensitive environments continue to adopt on-premises deployments to maintain greater control over infrastructure, compliance, and internal cybersecurity governance.
Organization Size
Large Enterprises represented the leading market segment in 2025 and are forecast to grow at a CAGR of 18.6–19.8% throughout the study period. Large organizations operate highly distributed digital infrastructures requiring continuous visibility into cloud assets, internet-facing applications, third-party connections, and unmanaged systems to reduce enterprise cyber risk.
- Large Enterprises – Global organizations deploy advanced exposure management platforms to secure complex infrastructures while improving governance, regulatory compliance, and enterprise-wide cyber resilience.
- SMEs – Small and medium-sized businesses increasingly adopt cloud-native ASM platforms because of lower implementation costs, subscription pricing models, simplified deployment, and growing awareness of cybersecurity risks.
Vertical
The BFSI segment generated the highest market revenue in 2025 and is anticipated to register a CAGR of 18.9–20.1% between 2026 and 2034. Financial institutions continue strengthening cybersecurity investments as digital banking, payment platforms, APIs, and cloud services increase exposure to sophisticated cyber threats.
- BFSI – Financial organizations rely on attack surface management to protect digital banking platforms, payment infrastructure, customer-facing applications, and third-party integrations against evolving cyber risks.
- Healthcare – Healthcare providers implement continuous exposure management to secure electronic health records, connected medical devices, cloud applications, and expanding telehealth ecosystems.
- Retail & E-Commerce – Retail enterprises deploy ASM platforms to protect online storefronts, digital payment systems, customer data, and interconnected supply chain infrastructure from external cyber threats.
Opportunity Snapshot
| Vertical | Revenue Contribution | Trend Tag | Adoption Stage |
|---|---|---|---|
| BFSI | High | Zero Trust | Mature |
| Healthcare | Medium | Medical IoT | Scaling |
| Retail & E-Commerce | Medium | Digital Commerce | Scaling |
| Others | Low | Risk Visibility | Emerging |
Attack Surface Management Market Growth Drivers and Impact Analysis
Expansion of Cloud-Native and Hybrid IT Environments
The rapid migration of enterprise workloads to public cloud, hybrid cloud, and multi-cloud infrastructures has significantly increased the number of externally accessible digital assets requiring continuous monitoring. Organizations frequently deploy applications across multiple cloud providers while maintaining on-premises infrastructure, creating fragmented visibility and increasing cyber exposure. Attack surface management platforms provide continuous discovery of internet-facing assets, cloud resources, APIs, and unmanaged systems to reduce hidden security risks. As enterprises accelerate digital transformation and software modernization initiatives, investments in automated exposure management continue rising across highly regulated sectors, including banking, healthcare, telecommunications, and government, strengthening long-term market expansion highlighted in the Attack Surface Management Market report.
Increasing Sophistication of Cyber Threats and Ransomware Attacks
Criminal networks continue to exploit unidentified internet-exposed assets, compromised credentials, exploited APIs, and third-party application dependencies in order to breach enterprises. Attack surface management tools allow organizations to discover exploitable assets prior to being detected by attackers. This reduces the response time and improves the cyber resilience of the organization. The increasing number of ransomware attacks on critical infrastructure providers, manufacturers, health care organizations, and financial institutions has boosted executive cybersecurity investment.
Growing Regulatory Focus on Cyber Resilience
Cybersecurity regulations around the world are continuing to be tightened with respect to aspects of resilience, digital risk management, breach notifications, and third-party management. The regulations compel businesses to ensure that they have full visibility of their digital assets, as well as prove their ability to continuously monitor and mitigate risks. Attack surface management tools can be leveraged as part of compliance programs to discover unmanaged internet-connected systems, enhance documentation, and improve governance of digital assets distributed across multiple locations. Growing regulatory pressure from different sectors is forecast to drive enterprise demand during the projection period.
Attack Surface Management Market Future Trends
Artificial Intelligence Strengthening Exposure Prioritization
Artificial intelligence and machine learning technologies are increasingly transforming exposure management by automating asset classification, predicting exploitability, correlating threat intelligence, and prioritizing vulnerabilities based on business impact. These attack surface management market trends enable security teams to focus remediation efforts on the highest-risk exposures while reducing alert fatigue. AI-driven analytics are expected to improve decision-making, automate investigation workflows, enhance predictive threat detection, and optimize enterprise cybersecurity operations across increasingly complex digital infrastructures.
Convergence with Unified Exposure Management Platforms
Attack surface management capabilities are increasingly becoming integrated into comprehensive exposure management platforms, combining vulnerability management, attack path analysis, identity security, cloud security posture management, and threat intelligence. Enterprises increasingly prefer unified cybersecurity platforms that consolidate security operations while improving operational efficiency, reducing tool complexity, and providing centralized visibility across hybrid IT environments. This integration trend is expected to redefine enterprise cybersecurity architecture during the forecast period.
Attack Surface Management Market Opportunities
Growing Demand Across Mid-Sized Enterprises
Small and medium-sized organizations are becoming attractive growth opportunities as affordable cloud-native cybersecurity platforms reduce implementation costs and simplify deployment. Attack surface management forecasts indicate increasing adoption among mid-sized enterprises seeking enterprise-grade cybersecurity capabilities without maintaining extensive internal security teams. Vendors introducing subscription-based pricing, managed security offerings, and simplified deployment models are expected to expand addressable markets while improving cybersecurity maturity across organizations with limited technical resources.
Expansion Across Critical Infrastructure Industries
Critical infrastructure sectors, including utilities, transportation, energy, manufacturing, and telecommunications, continue to modernize operational technology and connect industrial assets to digital networks. This transformation significantly expands external attack surfaces, requiring continuous monitoring and proactive risk management. Solution providers capable of integrating operational technology visibility, industrial cybersecurity intelligence, cloud security, and external exposure management into unified platforms are expected to capture substantial long-term investment opportunities as governments strengthen critical infrastructure cybersecurity regulations, supporting growth outlined in the Attack Surface Management Market forecast.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for