
Automotive Antifreeze Market Size, Trends & Growth by 2034
Coverage: By Fluid Type (Ethylene Glycol, Propylene Glycol, Glycerin); Technology (Inorganic Additive Technology, Organic Acid Technology, Hybrid Organic Acid Technology); Application (Passenger vehicle, Commercial vehicle, Construction vehicle) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00021955
- Category : Automotive and Transportation
- No. of Pages : 150
- Available Report Formats :


- Last update date : August 27, 2026


2025 Market Size
US$ 4.66 Bn
Base year value
2034 Forecast
US$ 6.31 Bn
Projected by 2034
CAGR 2026-2034
3.86 %
Growth rate
Addressable Market
US$ 50.93 Bn
(2026-2034)
The automotive antifreeze market was valued at US$ 4.66 Billion in 2025 and is projected to reach US$ 6.31 Billion by 2034, registering a CAGR of 3.86% during 2026–2034. Demand is supported by engine thermal management needs across passenger vehicles, commercial vehicles, and construction vehicles, with ethylene glycol, propylene glycol, and glycerin formulations serving varied performance, toxicity, and climate requirements.
North America remains an important demand center because harsh winters, long-distance vehicle usage, and mature aftermarket replacement cycles sustain coolant consumption. The automotive antifreeze market size in the region is expected to expand at a CAGR range of 3.4–3.8% during 2026–2034, supported by premium coolant adoption, hybrid vehicle parc growth, and wider use of extended-life formulations.
Automotive Antifreeze Market Assessment and Insights
- North America accounted for 24–27% share in 2025 and is expected to grow at a CAGR of 3.4–3.8% during 2026–2034, driven by seasonal replacement demand and premium coolant usage.
- US represented 72–76% of North America demand in 2025 and is projected to grow at a CAGR of 3.3–3.7% through 2034.
- Europe held 21–24% share in 2025 and is likely to expand at a CAGR of 3.1–3.5%, led by Germany, the UK, France, Italy, and Spain.
- Asia Pacific captured 34–38% share in 2025 and is projected to grow at a CAGR of 4.1–4.6%, led by China, India, Japan, and South Korea.
- Largest Segment: Ethylene glycol held 58–62% market share in 2025 and is expected to grow at a CAGR of 3.4–3.8% due to cost effectiveness and broad compatibility.
- High Growth Segmentl: Propylene glycol held 16–19% share in 2025 and is projected to grow at a CAGR of 4.4–4.9% due to lower-toxicity positioning.
- Key companies analyzed in detail: Castrol Limited, Chevron Corporation, Exxon Mobil Corporation, Halfords Group plc, Motul S.A., Prestone Products Corporation, Riverstone Energy Limited, Shell plc, TotalEnergies SE, and Valvoline Global Operations.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
Product evolution is moving from conventional inorganic additive technology toward organic acid technology and hybrid organic acid technology as vehicle manufacturers seek longer service intervals, improved corrosion protection, and compatibility with aluminum-rich engine designs. The automotive antifreeze market growth is also influenced by coolant recycling, concentrated formulations, and higher demand for fluids that perform reliably across extreme ambient conditions.
The future demand of the sector would depend upon the replacement cycles in mature markets and increasing ownership of automobiles in developing economies. Although battery electric vehicles decrease the consumption of coolant, but hybrids and thermal management technologies ensure a demand for specialized products. This positive industry scenario supports those companies that have expertise in formulation, OEM certifications and distribution channels.
Automotive Antifreeze Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 4.66 Billion |
| Market Size by 2034 | US$ 6.31 Billion |
| Global CAGR (2026 - 2034) | 3.86% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Automotive Antifreeze Market Analysis
Demand is based upon the global vehicle parc, where coolant needs to be replaced for purposes of freeze protection, boiling over prevention, and corrosion resistance. There is consistent aftermarket demand from passenger cars, while commercial trucks and construction equipment will have a need for long-lasting coolant, as it’s expensive for them to be idle. Supply depends upon glycol supply, additives, packaging, and private label retailing.
Automotive antifreeze market analysis indicates that premiumization is gradual rather than abrupt. Workshops increasingly prefer long-life coolants that reduce service frequency and protect mixed-metal systems. At the same time, price-sensitive markets continue to consume conventional ethylene glycol products, creating a two-speed demand pattern between developed aftermarket channels and emerging do-it-yourself retail segments.
Competition in this industry comes from lubricants produced by multinational corporations, coolant manufacturers, retailers, and regional blenders. Some of the major competitors include Castrol Limited, Chevron Corporation, Exxon Mobil Corporation, Shell plc, TotalEnergies SE, Motul S.A., Prestone Products Corporation, Valvoline Global Operations, Halfords Group plc, and Riverstone Energy Limited.
Investments are geared toward low-toxicity coolants, extended-life additive systems, and fluids for hybrid/electric platform vehicles. Strategic positioning will involve a closer relationship between validation, sustainable packaging, and channel collaboration. The suppliers who balance global manufacturing scale with local approvals for their products can safeguard their margins while fulfilling diverse climate and vehicle needs.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
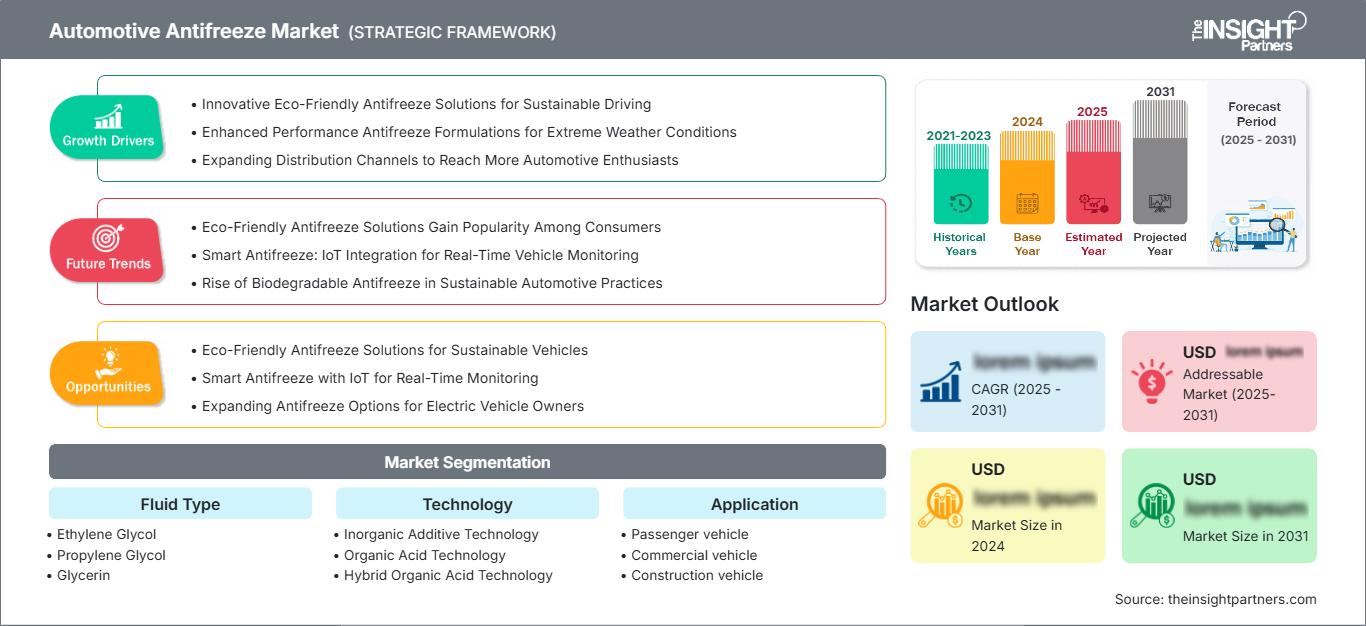
Automotive Antifreeze Market: Strategic Insights
Regional Insights
North America automotive antifreeze market
North America held 24–27% automotive antifreeze market share in 2025 and is projected to grow at a CAGR of 3.4–3.8% during 2026–2034. Demand is supported by cold-weather states, high vehicle miles traveled, pickup and SUV penetration, and strong retail availability of premixed and concentrated coolant products.
The area prefers products having superior life due to the importance of compatibility of products with modern engines and minimal maintenance requirements. Operators of fleet vehicles in logistics, construction, agriculture, and municipalities also promote the demand for coolants that provide protection against corrosion and overheating.
U.S. automotive antifreeze market
The U.S. accounted for 72–76% of North America's automotive antifreeze market demand in 2025 and is expected to grow at a CAGR of 3.3–3.7% through 2034. Vehicle ownership, a huge market of aftermarket chains, and extensive service coverage ensure that coolant exchange becomes a standard maintenance category for both passenger cars and light commercial vehicles.
The company has a significant presence via national retailers, quick-lube stores, dealer service centers, and fleet maintenance services. The application focus is passenger cars, pickups, vans, and commercial fleets, while the hybrid usage helps establish new coolant formulations for the engine, inverters, and battery cooling system.
Europe automotive antifreeze market
Europe accounted for 21–24% share of the automotive antifreeze market in 2025 and is expected to grow at a CAGR of 3.1–3.5% through 2034. Germany leads demand because of its automotive manufacturing base, premium vehicle parc, and stringent service specifications, while the UK and France sustain strong aftermarket replacement volumes.
Italy and Spain contribute through passenger vehicle maintenance, light commercial fleets, and warmer-climate demand for boil-over protection. Environmental regulation and workshop professionalism support the adoption of OAT and HOAT coolants, particularly where OEM approvals, longer drain intervals, and compatibility with aluminum engines influence purchasing decisions.
APAC automotive antifreeze market
APAC held 34–38% share of the automotive antifreeze market in 2025 and is projected to grow at a CAGR of 4.1–4.6% during 2026–2034. China remains the largest contributor, supported by vehicle production, aftermarket scale, and electric mobility supply chains.
India, Japan, South Korea, and Australia add differentiated demand from passenger cars, commercial vehicles, construction equipment, and climate-specific cooling needs. Industrialization, infrastructure activity, and expanding service networks support higher coolant penetration, while local manufacturers compete on price and regional availability.
Middle East & Africa automotive antifreeze market
The Middle East & Africa automotive antifreeze market is projected to grow at a CAGR of 3.6–4.1% through 2034, supported by high-temperature vehicle operation, infrastructure projects, mining, logistics, and energy-sector fleets. Saudi Arabia and the UAE favor high-performance coolants for heat dissipation.
South Africa contributes through passenger vehicles, commercial transport, and aftermarket maintenance, while the rest of MEA remains fragmented. Demand is shaped less by freeze protection and more by corrosion control, boil-over resistance, and durability in dusty, high-load operating environments.
Segmentation Analysis
Fluid Type
Fluid Type is central to the automotive antifreeze market scope because base chemistry determines toxicity profile, heat-transfer efficiency, price, and service suitability. The segment is expected to grow at a CAGR of 3.7–4.1% during 2026–2034 as users balance performance, safety, and environmental expectations.
- Ethylene Glycol remains the dominant choice because it is cost-effective, widely available, and performs reliably across cold and hot climates, making it preferred for passenger and commercial vehicle cooling systems.
- Propylene Glycol is gaining attention where lower toxicity is valued, especially in service environments with stricter handling standards, fleet safety policies, or sustainability-focused procurement preferences.
- Glycerin serves a smaller niche, supported by interest in bio-based inputs and reduced environmental impact, although performance, availability, and cost considerations limit broader adoption.
Technology
According to the Automotive Antifreeze Market report, the Technology segment is projected to grow at a CAGR of 3.8–4.2% during 2026–2034 as coolant formulations continue evolving toward longer service intervals, enhanced thermal stability, and improved protection for aluminum components, rubber parts, seals, and mixed-metal cooling circuits. Increasing demand for high-performance and extended-life antifreeze solutions is encouraging manufacturers to develop advanced technologies that improve engine efficiency, corrosion resistance, and overall cooling system durability.
- Inorganic Additive Technology remains relevant in older vehicles and price-sensitive markets, where conventional service practices and low upfront cost continue to influence coolant selection.
- Organic Acid Technology leads premium adoption because it supports extended drain intervals, improved corrosion protection, and compatibility with modern engine materials across passenger and light commercial vehicles.
- Hybrid Organic Acid Technology bridges conventional and extended-life requirements, offering balanced inhibitor performance for mixed fleets that contain varied vehicle ages, engine types, and service specifications.
Application
The application segment of the automotive antifreeze market is expected to grow at a CAGR of 3.6–4.0% during 2026–2034, supported by recurring coolant replacement across private vehicles, fleet vehicles, and off-highway equipment operating in diverse climate and load conditions.
- Passenger vehicle demand is driven by high vehicle parc, scheduled maintenance, do-it-yourself retail purchases, and growing awareness of overheating prevention and cooling system longevity.
- Commercial vehicle demand is supported by fleet uptime requirements, long operating hours, heavy payloads, and maintenance programs that prioritize thermal stability and corrosion control.
- Construction vehicle demand reflects high-load operation, dusty sites, and continuous engine stress, making durable coolant performance important for excavators, loaders, cranes, and related equipment.
Opportunity Snapshot
| Application | Revenue Contribution | Trend Tag | Adoption Stage |
|---|---|---|---|
| Passenger Vehicle | High | Extended Life | Mature |
| Commercial Vehicle | Medium | Fleet Uptime | Scaling |
| Construction Vehicle | Medium | Heavy Duty | Scaling |
Automotive Antifreeze Market Growth Drivers and Impact Analysis
Expanding Vehicle Parc and Routine Coolant Replacement
The installed vehicle base is the most resilient demand driver, as each internal combustion engine and hybrid vehicle needs coolant replacement. New vehicle production is less variable than coolant replacement, as coolant deteriorates due to heat cycles, loss of additives, contamination, and corrosion. Automotive workshops, retail operations, and fleet garages generate repeat consumption irrespective of new vehicle sales. This demand driver is more applicable in geographical locations where older vehicles, higher miles driven per year, and climatic variations exist. Additionally, this demand driver is favorable for branded products as improper coolant choice leads to seal, radiator, water pump, and aluminum component damage.
Shift Toward Extended-Life Coolant Technologies
Organic Acid Technology and Hybrid Organic Acid Technology are taking shape in the automotive industry due to the desire by car manufacturers and fleet owners to have extended drain intervals and greater protection for their new-age coolant systems. With organic acid technology, fewer maintenance intervals, warranty harmonization, and better protection of mixed metal engines compared to conventional coolants are achieved. This brings value growth irrespective of the volume growth of the product, as superior products normally come at a higher price point.
Growth in Commercial and Construction Vehicle Utilization
The vehicles are subjected to heavy-duty operations, thus necessitating the quality of coolant. The logistics sector growth, infrastructure development, mining operations, and the municipality operations will create increased demand for reliable thermal fluid products. Commercial and construction vehicles may need greater amounts of coolant compared to passenger vehicles; therefore, any increase in the vehicle fleets can lead to significant demand levels. Preventive maintenance will also support the demand for antifreezes meeting the specified requirements and reducing corrosion, cavitation, scaling, and overheating.
Automotive Antifreeze Market Future Trends
Specialized Coolants for Hybrid and Electric Thermal Systems
Automotive antifreeze market trends will increasingly reflect the transition from engine-only cooling to broader thermal management. The cooling of hybrid vehicle engines is not different from that of ordinary engines. However, there will be an increased need for low-conductivity fluid due to the presence of battery packs, inverters and power electronics. There is an expectation that the suppliers will work to improve the formulations for dielectric capability, material compatibility and improved durability. The adoption process will be slow owing to differences in vehicle structures across manufacturers.
Sustainability and Lower-Toxicity Formulation Development
Environmental pressures are putting pressure on producers to enhance the packaging, recyclability, disposal instructions, and availability of low-toxicity fluids. Ethylene glycol could be used for the production of bio-based glycerine formulation, and propylene glycol could also become selectively adopted under certain conditions. Nevertheless, cost-effectiveness and performance requirements are likely to maintain the prevalence of ethylene glycol for most applications. This means that the current trend should rather be viewed as an attempt to provide a more diverse range of product types for various consumers.
Automotive Antifreeze Market Opportunities
Aftermarket Premiumization in Emerging Economies
Automotive antifreeze market Forecasts point to a meaningful opportunity in emerging aftermarket channels as vehicle owners shift from low-cost, generic coolant toward branded, specification-led products. Increasing vehicle complexity, better workshop network connectivity, and increasing awareness about cooling system problems make this possible. Suppliers will be able to generate additional value through packaging of smaller sizes, training of technicians, compatibility charts, and localized language labels. This is especially true for India, Southeast Asia, Latin America, and certain parts of MEA, where there is increasing growth in vehicle parc, but professional coolant selection practices are still evolving.
Fleet Service Partnerships and Technical Programs
The fleet operator is a lucrative target as the failure of the coolant may result in downtime, damage to the engine, and increased operating costs. The suppliers can gain an advantage through coolant testing, drain intervals scheduling, education, and standardization of the products in the mixed fleets. The commercial vehicle, construction equipment, bus, and municipal fleets are ideal candidates as operating conditions are harsh and the decision on maintenance is made at one central location. The long-term services can increase the retention of the brand and help eliminate price wars.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for