
Automotive Blind Spot Detection System Market Share, Growth & Forecast by 2034
Coverage: By Vehicle Type (Passenger Cars, Commercial Vehicles); Technology (Radar Sensor, Ultrasonic Sensor, LIDAR Sensor, Others); End User (Original Equipment Manufacturers (OEM), Aftermarket) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00020867
- Category : Automotive and Transportation
- No. of Pages : 150
- Available Report Formats :


- Last update date : August 11, 2026


2025 Market Size
US$ 4.84 Bn
Base year value
2034 Forecast
US$ 14.75 Bn
Projected by 2034
CAGR 2026-2034
13.17 %
Growth rate
Addressable Market
US$ 85.05 Bn
(2026-2034)
The automotive blind spot detection system market was valued at US$ 4.84 billion in 2025 and is projected to reach US$ 14.75 billion by 2034, registering a CAGR of 13.17% during 2026–2034. Market expansion is being driven by the increasing integration of advanced driver assistance systems (ADAS), stringent vehicle safety regulations, and rising consumer demand for technologies that improve driver awareness and reduce collision risks. Continuous advancements in sensor technologies and electronic control systems are further accelerating product adoption across passenger and commercial vehicles.
North America continues to represent one of the leading regional markets due to the early adoption of ADAS technologies, stringent vehicle safety standards, and strong consumer preference for premium safety features. The automotive blind spot detection system market size across the region is projected to expand at an estimated CAGR of 12.5%–13.2% during the forecast period. Increasing penetration of intelligent mobility solutions, growing production of technologically advanced vehicles, and rising investments in autonomous driving technologies continue to strengthen long-term regional growth.
Automotive Blind Spot Detection System Market Assessment and Insights
- North America: Accounted for 33%–37% share in 2025 and is anticipated to register a CAGR of 12.5%–13.2% during 2026–2034, supported by high ADAS penetration, premium vehicle sales, and evolving automotive safety regulations.
- US: Represented approximately 76%–81% of the North American market in 2025 and is projected to grow at a CAGR of 12.7%–13.4%, driven by increasing production of connected vehicles and growing consumer awareness regarding active safety systems.
- Europe: Held 27%–31% market share in 2025 and is expected to expand at a CAGR of 13.0%–13.8%, led by Germany, France, the United Kingdom, Italy, and Spain owing to stringent vehicle safety mandates and strong automotive manufacturing capabilities.
- Asia Pacific: Accounted for 25%–29% share in 2025 and is forecast to register the fastest regional expansion at a CAGR of 14.2%–15.0%, supported by rising vehicle production, increasing adoption of ADAS, and expanding investments in intelligent transportation technologies across China, Japan, South Korea, and India.
- Largest Segment: Passenger Cars accounted for approximately 72%–76% market share in 2025 and are projected to expand at a CAGR of 13.0%–13.7%, supported by growing integration of advanced safety technologies across mid-range and premium vehicle categories.
- High Growth Segment: Radar Sensor technology represented approximately 46%–50% market share in 2025 and is expected to register a CAGR of 14.0%–14.8%, driven by superior detection accuracy, reliable performance under adverse weather conditions, and widespread OEM adoption.
- Key companies analyzed in detail: Continental AG, DENSO Corporation, Robert Bosch GmbH, Aptiv PLC (formerly Delphi Automotive), Autoliv Inc., ZF Friedrichshafen AG (ZF TRW), Xiamen Autostar Electronics Co., Ltd., Auto-i Corporation, Valeo SA, Ficosa International SA, Preco Electronics LLC.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The automotive blind spot detection system market has undergone a substantial technological transformation with the rapid evolution of advanced driver assistance systems, intelligent sensing platforms, and vehicle electronics. Automotive manufacturers are increasingly integrating radar, ultrasonic, and LiDAR technologies with camera-based perception systems to improve detection accuracy while reducing false alerts. Continuous improvements in semiconductor performance, sensor miniaturization, and software algorithms have enabled blind spot detection systems to become standard safety features across an expanding range of passenger and commercial vehicles.
Future market development of the Automotive Blind Spot Detection System Market is expected to be supported by increasing investments in connected mobility, autonomous driving technologies, and vehicle electrification. Regulatory initiatives promoting mandatory safety equipment, combined with rising consumer preference for intelligent driver assistance features, are encouraging OEMs to expand ADAS integration across multiple vehicle segments. Emerging automotive markets are also witnessing increasing demand as domestic vehicle manufacturers adopt advanced safety technologies to improve competitiveness in global markets, supporting long-term growth in the market.
Analysis
Automotive Blind Spot Detection System Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 4.84 Billion |
| Market Size by 2034 | US$ 14.75 Billion |
| Global CAGR (2026 - 2034) | 13.17% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Automotive Blind Spot Detection System Market Analysis
The increasing implementation of mandatory vehicle safety regulations, together with growing consumer demand for intelligent driver assistance features, continues to accelerate the automotive blind spot detection system market growth. Automobile producers are increasing the deployment of blind spot warning systems in both luxury and economy cars to ensure safer driving conditions and better driver confidence. The increasing number of electric vehicles and connectivity solutions is contributing to higher demands for high-end sensor devices that can offer reliable object detection in varied driving scenarios.
Through the supply chain, component makers are continuing their investments in cutting-edge radar components, ultrasonic sensors, LiDAR solutions, electronic control units, and software platforms. Innovations in semiconductor production technology, artificial intelligence algorithms, and high-performance computing are facilitating faster signal processing and improved detection accuracy. Collaborative efforts between sensor makers, automobile original equipment makers, and software developers are fueling innovations while enhancing integration efficiency within next-generation car platforms.
Competitive intensity continues to increase as global automotive technology providers focus on expanding their ADAS portfolios through research investments, strategic partnerships, and advanced product development. The automotive blind spot detection system market analysis indicates that Continental AG, Robert Bosch GmbH, DENSO Corporation, Valeo SA, ZF Friedrichshafen AG, Aptiv PLC, and Autoliv Inc. continue strengthening their competitive positions through innovations in radar sensing, software-defined vehicle architecture, and integrated safety platforms. Regional manufacturers are also investing in cost-effective solutions to address increasing OEM demand across emerging automotive markets.
There is now growing attention among manufacturers towards scalable sensor platforms, artificial intelligence-based perception systems, and vehicle safety ecosystems that will enable higher driving automation. In terms of investments, efforts are being directed at making the systems more reliable, lowering hardware costs, and making it easy for the systems to integrate with lane changing assistance, adaptive cruise control, collision avoidance, and autonomous driving systems.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
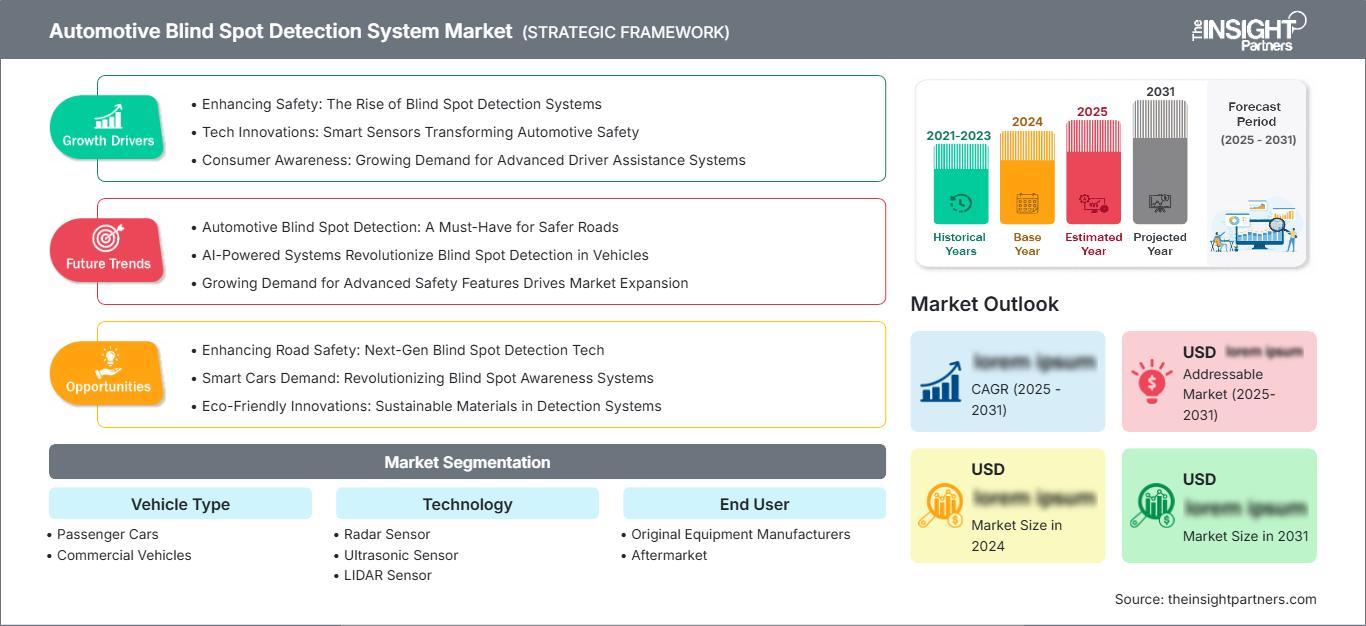
Automotive Blind Spot Detection System Market: Strategic Insights
Regional Insights
North America Automotive Blind Spot Detection System Market
North America accounted for an estimated 33%–37% share of the global automotive blind spot detection system market in 2025 and is projected to expand at a CAGR of 12.5%–13.2% during 2026–2034. The automotive blind spot detection system market share in the region remains significant due to the early commercialization of advanced driver assistance systems, strong regulatory emphasis on vehicle safety, and increasing consumer preference for vehicles equipped with intelligent collision avoidance technologies. Premium passenger cars and light truck penetration rates at high levels will increase the regional demand for blind spot detection systems.
Both the US and Canada remain committed to connected mobility research and next-generation automotive electronics, thus increasing the use of radar- and sensors-based safety systems. Many auto manufacturers include blind spot detection systems as standard equipment on many types of automobiles, while other applications will see more uptake in the aftermarket segment.
U.S. Automotive Blind Spot Detection System Market
The United States represented approximately 76%–81% of the North American Automotive Blind Spot Detection System Market in 2025 and is anticipated to register a CAGR of 12.7%–13.4% through 2034. Growing consumer awareness regarding active safety technologies, rising production of connected vehicles, and increasing deployment of Level 2 and Level 3 driver assistance functions continue to support the expansion of the Automotive Blind Spot Detection System Market. Strong investment in automotive software development and semiconductor innovation further enhances the competitiveness of domestic vehicle manufacturers and supports the ongoing adoption of advanced blind spot detection technologies.
Leading suppliers, including Continental AG, Robert Bosch GmbH, Aptiv PLC, Autoliv Inc., Valeo SA, and DENSO Corporation, maintain strong operational and engineering activities within the U.S. automotive ecosystem. Continuous collaboration between OEMs and technology companies is accelerating sensor integration, software optimization, and functional safety validation, strengthening adoption across passenger vehicles and commercial transportation fleets.
Europe Automotive Blind Spot Detection System Market
Europe held approximately 27%–31% of the global market in 2025 and is projected to expand at a CAGR of 13.0%–13.8% during the forecast period. Germany remains the largest contributor owing to its advanced automotive manufacturing capabilities, strong premium vehicle production, and continuous investment in intelligent safety technologies. Vehicle manufacturers continue integrating sophisticated ADAS solutions to comply with evolving safety regulations while improving driver convenience and vehicle performance, supporting sustained growth in the Automotive Blind Spot Detection System Market.
The United Kingdom continues to witness growing demand for connected vehicles and intelligent safety technologies supported by increasing consumer awareness and regulatory initiatives promoting safer mobility. France, Italy, and Spain are also strengthening regional demand through expanding automotive production, increasing electric vehicle manufacturing, and broader implementation of advanced driver assistance systems. Continued investment in vehicle electronics and sensor technologies is expected to sustain regional competitiveness throughout the forecast period.
APAC Automotive Blind Spot Detection System Market
Asia Pacific accounted for an estimated 25%–29% share of the global market in 2025 and is projected to register the fastest regional CAGR of 14.2%–15.0% during 2026–2034. China remains the leading regional market due to rapid vehicle production, increasing electric vehicle adoption, and significant investments in intelligent transportation technologies.
Japan, South Korea, India, and Australia continue contributing to regional expansion through increasing ADAS integration, supportive government initiatives, growing semiconductor manufacturing capabilities, and expanding production of connected passenger vehicles. Strong investments in autonomous driving research continue to support long-term regional growth.
Middle East & Africa Automotive Blind Spot Detection System Market
The Middle East & Africa market is expected to expand at a CAGR of 11.2%–11.9% throughout the forecast period. Saudi Arabia remains the largest regional market owing to increasing premium vehicle sales, expanding transportation infrastructure, and growing adoption of intelligent automotive technologies.
The UAE, South Africa, and the Rest of MEA are gradually increasing the implementation of advanced vehicle safety systems as consumers prioritize premium automotive features. Government investments in smart mobility initiatives and the modernization of transportation infrastructure are expected to encourage further adoption of ADAS technologies across the region.
Segmentation Analysis
Vehicle Type
The Vehicle Type segment is projected to expand at a CAGR of 13.0%–13.7% during 2026–2034. The automotive blind spot detection system market scope continues to broaden as vehicle manufacturers increasingly integrate advanced safety systems across passenger and commercial vehicle platforms. Growing regulatory requirements, consumer awareness, and continuous improvements in sensor technologies are encouraging OEMs to standardize blind spot detection systems across a wider range of vehicle models.
- Passenger Cars – Continue representing the largest demand category owing to high production volumes, increasing penetration of ADAS features, stronger consumer preference for advanced safety technologies, and expanding adoption across mid-range and premium vehicle segments.
- Commercial Vehicles – Adoption continues increasing as fleet operators prioritize collision prevention, driver safety, and regulatory compliance. Blind spot monitoring systems improve operational safety for trucks, buses, and delivery vehicles operating in urban environments.
Technology
The Technology segment is anticipated to register a CAGR of 13.8%–14.5% throughout the forecast period. Continuous innovation in sensing technologies is improving object detection accuracy, reducing false alerts, and supporting seamless integration with lane change assistance and autonomous driving functions. Manufacturers continue investing in advanced perception technologies to enhance operational reliability under varying environmental conditions.
- Radar Sensor – Remains the dominant sensing technology due to superior performance under adverse weather conditions, long detection range, and extensive integration into advanced driver assistance systems by leading automotive manufacturers.
- Ultrasonic Sensor – Widely deployed in cost-sensitive vehicle platforms where short-range object detection supports parking assistance and complementary blind spot monitoring applications while maintaining affordability and ease of integration.
- LIDAR Sensor – Increasingly adopted in next-generation intelligent vehicles requiring high-resolution environmental perception. Although currently concentrated in premium platforms, technological advancements are expected to improve commercial adoption over time.
End User
The End User segment is expected to grow at a CAGR of 12.8%–13.5% during the forecast period. Original equipment manufacturers continue accounting for the majority of installations owing to factory integration of advanced safety technologies, while aftermarket demand expands through retrofit solutions for existing vehicle fleets seeking enhanced safety performance.
- Original Equipment Manufacturers – Continue generating the largest revenue contribution as automakers increasingly integrate blind spot detection systems during vehicle production to satisfy regulatory requirements and evolving consumer safety expectations.
- Aftermarket – Continues expanding steadily through retrofit installations supported by growing awareness of vehicle safety, improved product availability, and increasing demand from owners of older passenger and commercial vehicles.
Opportunity Snapshot
| End User | Revenue Contribution | Trend Tag | Adoption Stage |
|---|---|---|---|
| Original Equipment Manufacturers (OEMs) | High | Factory Integration | Mature |
| Aftermarket | Medium | Fleet Retrofit | Scaling |
Automotive Blind Spot Detection System Market Growth Drivers and Impact Analysis
Stringent Vehicle Safety Regulations Accelerating ADAS Integration
Regulations are being introduced in major automotive markets around the world that are increasingly stringent with regard to making efforts towards decreasing fatalities on the roads and ensuring safety of vehicle occupants. It has become an essential part of the advanced driver assistance systems that have been installed in many contemporary passenger vehicles and commercial vehicles as well. Automotive OEMs are increasingly adopting this technology in order to comply with the changing requirements of the regulations in terms of improving the safety ratings of vehicles. With the help of changing regulations, increased consumer awareness, and continuous advancements in technology, the adoption of blind spot detection technology has increased among premium cars and ordinary cars alike.
Rapid Growth of Connected and Electric Vehicles
There are numerous chances for advanced sensing solutions due to the rapid deployment of connected cars and BEVs. Contemporary vehicle design incorporates increasing use of radar sensors, cameras, electronic control units, and software-defined platforms, enabling multi-function driver assist capability. Detection of blind spot technology will become part of the intelligent safety system as it will help drivers to be aware of their surroundings during changing lanes and difficult driving conditions. Manufacturers are focused on the development of advanced driver assist systems (ADAS) incorporating blind spot detection with lane keeping assist, adaptive cruise control, and collision avoidance technologies. Thus, electrification and connectivity trends will stimulate demand for advanced sensing solutions in the future.
Advancements in Radar and Sensor Fusion Technologies
The continuous advances in the areas of radar technologies, algorithms for sensor fusion, semiconductor materials and AI have brought great improvements to the accuracy and reliability of blind spot detection systems. The contemporary products incorporate such technologies as radar, ultrasonic sensors, cameras and LiDAR for enhanced perception of the environment in different weather and traffic conditions. The use of these technologies ensures the reduction of false warnings and allows for quicker reaction and reliable operation. The development of software, miniaturization of electronics and powerful processors ensure the system efficiency and reduced manufacturing expenses. With the decreasing costs of sensing technologies, the products will be widely used in cars of different price categories.
Automotive Blind Spot Detection System Market Future Trends
Software-Defined Vehicle Platforms Enhancing ADAS Capabilities
The automotive industry is transitioning toward software-defined vehicle architectures capable of supporting continuous functional upgrades throughout a vehicle's lifecycle. Manufacturers increasingly integrate blind spot detection systems with centralized computing platforms that enable over-the-air software updates and enhanced feature expansion. Artificial intelligence and advanced perception software improve object classification, detection accuracy, and driver notification capabilities while reducing system complexity. Consequently, automotive blind spot detection system market trends indicate growing adoption of scalable software platforms that support higher levels of vehicle intelligence and automated driving capabilities across global automotive production.
Expansion of Multi-Sensor Perception Systems
In the future, blind spot detection system technology is expected to involve more multi-sensor perception platforms that integrate radar, ultrasonic sensors, cameras and LiDAR technology to form a comprehensive detection system. This technology improves environmental understanding, reduces detection blind spots and ensures high levels of safety during operation in difficult situations. Technological improvements in semiconductors and the development of new artificial intelligence algorithms are expected to improve performance and decrease manufacturing cost. Hence, auto companies are focusing on sensor fusion technology that will enable next-generation driver assistance and autonomous driving technologies.
Automotive Blind Spot Detection System Market Opportunities
Expansion Across Emerging Automotive Manufacturing Hubs
Rapid growth in vehicle production across Asia Pacific, Eastern Europe, Latin America, and selected Middle Eastern economies presents substantial opportunities for blind spot detection system manufacturers. Expanding domestic automotive manufacturing capacity, increasing regulatory focus on vehicle safety, and growing consumer demand for intelligent safety technologies continue supporting long-term market expansion. Automotive blind spot detection system market Forecasts indicate that manufacturers establishing regional production facilities, engineering centers, and strategic partnerships with local OEMs will be well positioned to capture increasing demand while improving supply chain resilience and reducing production costs.
Development of Cost-Effective ADAS Solutions for Mass-Market Vehicles
Car makers are now trying to look for inexpensive driver assist systems that can be employed in volume manufacturing of cars. This opens up immense possibilities for companies that can design small-sized radar units, software platforms, and sensing technologies with the ability to perform efficiently even at low prices. The cost-efficiency of these systems is being increased by the improvements in the manufacturing of semiconductors, artificial intelligence, and electronics. The companies that are concentrating on scalable technology platforms, localized manufacturing, and collaborative product development with carmakers will improve their competitiveness in the future.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for