
Flip Chip Technology Market Size, Share & Growth by 2034
Coverage: by Wafer Bumping Process (Copper (Cu) Pillar, Lead-Free, Tin/lead Eutectic Solder, Gold Stud+ Plated Solder); Packaging Technology (2D IC, 2.5D IC, 3D IC); Packaging Type (FC BGA, FC PGA, FC LGA, FC QFN, FC SiP, FC CSP); Product (Memory, LED, CMOS Image Sensor, RF, Analog, Mixed Signal, and Power IC, CPU, SoC, GPU); Application (Consumer Electronics, Telecommunication, Automotive, Industrial Sector, Medical Devices, Smart Technologies, Military and Aerospace) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00012046
- Category : Electronics and Semiconductor
- No. of Pages : 150
- Available Report Formats :


- Last update date : September 10, 2026


2025 Market Size
US$ 38.72 Bn
Base year value
2034 Forecast
US$ 56.38 Bn
Projected by 2034
CAGR 2026-2034
4.26 %
Growth rate
Addressable Market
US$ 431.80 Bn
(2026-2034)
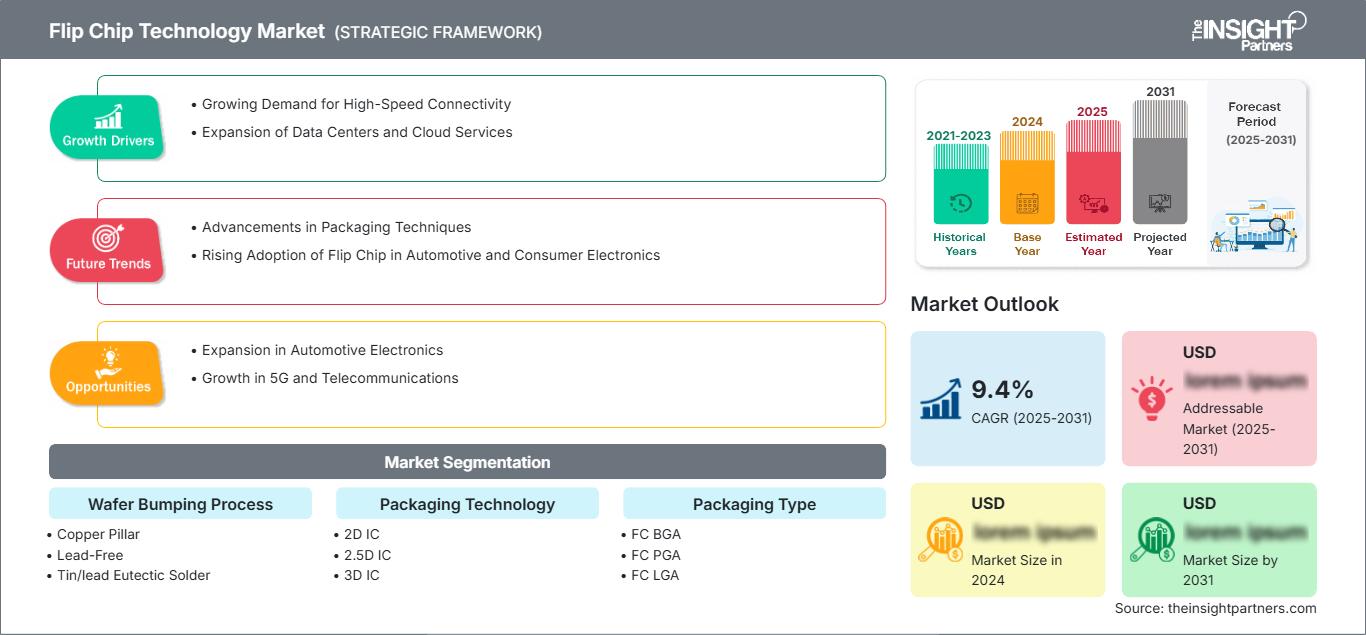
The global Flip Chip Technology market was valued at US$ 38.72 billion in 2025 and is expected to reach US$ 56.38 billion by 2034; it is estimated to record a CAGR of 4.26% during 2026-2034.
Flip Chip Technology Market Assessment and Insights
- North America held 28–31% share in 2025 and is growing at a CAGR of 4.2–4.9% during 2026–2034, led by semiconductor design, high-performance computing, and consumer electronics across the US and Canada.
- US represented 82–85% of North American revenue in 2025 and is growing at a CAGR of 4.4–5.1% during 2026–2034.
- Europe accounted for 15–18% share in 2025 and is growing at a CAGR of 4.0–4.7% during 2026–2034, led by Germany, the UK, France, Italy, and Spain.
- Asia Pacific held 45–48% share in 2025 and is growing at a CAGR of 5.5–6.2% during 2026–2034, led by China, India, Japan, South Korea, and Australia.
- Largest Segment Copper Pillar held 32–35% market share in 2025 and is growing at a CAGR of 5.0–5.7% during 2026–2034.
- High Growth Segment 3D IC represented 18–21% market share in 2025 and is growing at a CAGR of 5.5–6.2% during 2026–2034.
- Key companies analyzed in detail: Amkor Technology; ASE Group; FlipChip International LLC; Intel Corporation; Samsung Electronics; Siliconware Precision Industries Co., Ltd.; STATS ChipPAC Ltd. (JCET Group); Taiwan Semiconductor Manufacturing Company Limited; TF AMD Microelectronics (Penang) Sdn. Bhd.; UTAC (United Test and Assembly Center Ltd); GlobalFoundries; Qualcomm Incorporated.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
Flip Chip technology has progressed from traditional solder bumps to advanced copper pillars and hybrid bonding, which helps increase the density of interconnects and thermal performance, as well as provides superior electrical characteristics for high-demanding semiconductors. The production process now depends on bump pitches, interconnect densities, and tested reliability under various operating conditions and packages. Demand for Flip Chip Technology Market is also determined by semiconductor companies that match flip chip technology to performance and thermal criteria.
Forward investments have started focusing on Asia Pacific, North America, and Europe due to innovations and high demand for semiconductor applications, high-performance computing, and consumer electronics. Regulatory compliance with quality and environmental standards contributes to package qualification. Buyers prefer technologies that provide performance, density, and reliability, along with support services and manufacturing capabilities.
Flip Chip Technology Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 38.72 Billion |
| Market Size by 2034 | US$ 56.38 Billion |
| Global CAGR (2026 - 2034) | 4.26% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Flip Chip Technology Market Analysis
Drivers Flip chip technology market growth drivers include semiconductor performance specifications, miniaturization needs, thermal requirements, and advanced packaging trends. Value Chain Includes bumping services, substrate providers, assembly services providers, and semiconductor manufacturers. Supply dynamics include manufacturing capacity, technology advancement, and semiconductor demand cycles. Flip Chip Technology Market report shows that copper pillar bumping leads through proven performance while 3D IC packaging increases its share through integration benefits. Service capability matters because it affects product performance and time-to-market due to process capability, quality management, and manufacturing capacity.
Competitors include semiconductor packaging companies and foundries. Major competitors are Taiwan Semiconductor Manufacturing Company Limited (TSMC), Intel Corporation, Samsung Electronics, ASE Group, Amkor Technology, Siliconware Precision Industries Co., Ltd. (SPIL), STATS ChipPAC Ltd. (JCET Group), FlipChip International LLC, TF AMD Microelectronics (Penang) Sdn. Bhd., UTAC (United Test and Assembly Center Ltd), GlobalFoundries, and Qualcomm Incorporated. Competitors invest into bumping capability, packaging technology, and customer relationship development. Market leaders include TSMC and Intel because of advanced packaging and semiconductor manufacturing know-how; ASE and Amkor have competitive advantage due to scale of assembly and testing services. Competition positioning is based on performance certification, technology capability, and manufacturing reliability.
Semiconductor demand is growing because semiconductor manufacturers seek higher computing performance while reducing package size and improving electrical and thermal performance. Advanced flip chip technology becomes more relevant for high-performance processors, graphics devices, networking equipment, memory components, mobile electronics, and automotive semiconductors. Growing artificial intelligence and intensive computing trends increase semiconductor manufacturers' demand for high-bandwidth and low interconnect distance architectures with better heat dissipation capabilities. This demand encourages semiconductor manufacturers to develop finer-pitch interconnects and more sophisticated packaging configurations.
Manufacturing capacity investments in the regions and advance of packaging capacity could affect the competitive landscape. Semiconductor manufacturers pay attention to process automation, wafer level packaging, advanced substrate integration, and yield management due to more complicated package configuration requirements. Transition into 3D packaging, chiplet architectures, and hybrid bonding increases competitive landscape opportunities for semiconductor companies with advanced process development and high-volume manufacturing capabilities. Growing complexity of semiconductor design and packaging importance for system performance encourages suppliers who can provide combination of advanced technology, scalable capacity, reliability, and cost efficiency to participate in new opportunities in the Flip Chip Technology Market.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Flip Chip Technology Market: Strategic Insights
Regional Insights
North America Flip Chip Technology Market
North America accounted for 28–31% of Flip Chip Technology Market share in 2025 and is projected to grow at a CAGR of 4.2–4.9% during 2026–2034. The demand for products is driven by the semiconductor design, high performance computing, consumer electronics, and use of advanced packaging in both the US and Canada. The semiconductor industry ecosystem and technological development create continuous demand for flip chip. The companies that facilitate the demand include Intel Corporation, Amkor Technology, GlobalFoundries, Qualcomm Incorporated, and FlipChip International LLC.
U.S. Flip Chip Technology Market
The U.S. represented 82–85% of North American revenue in 2025 and is forecast to grow at a CAGR of 4.4–5.1% during 2026–2034. Application demand is concentrated in high-performance computing, communications devices, consumer electronics, and automotive applications. Company presence is reinforced by Intel Corporation, Amkor Technology, GlobalFoundries, Qualcomm Incorporated, and FlipChip International LLC. Buyers prioritize bumping capability, packaging technology, performance, and reliability, plus design support that reduces development time and improves confidence in flip chip solutions.
Europe Flip Chip Technology Market
Europe held 15–18% share in 2025 and is expected to grow at a CAGR of 4.0–4.7% during 2026–2034. Germany leads through automotive electronics and industrial applications, while the UK supports demand from semiconductor design and communications. France, Italy, and Spain add demand through consumer electronics and automotive applications. Quality and reliability standards favor suppliers with documented performance and capability. Amkor Technology, ASE Group, and Intel Corporation remain visible across automotive and industrial projects.
APAC Flip Chip Technology Market
Asia Pacific accounted for 45–48% share in 2025 and is projected to grow at a CAGR of 5.5–6.2% during 2026–2034. China leads through semiconductor manufacturing and consumer electronics production, while India expands through semiconductor design and electronics growth. Japan and South Korea prioritize advanced packaging for memory and processor applications, while Australia adds communications and industrial applications. Policy support for semiconductor manufacturing and advanced packaging strengthen Flip Chip Technology Market adoption where flip chip capability and supply chain carry significant value.
Middle East & Africa Flip Chip Technology Market
The Middle East & Africa market is projected to grow at a CAGR of 3.5–4.2% during 2026–2034. Saudi Arabia leads through technology infrastructure and semiconductor development, while the UAE adds electronics and technology adoption. South Africa and Rest of MEA rely on technology adoption and infrastructure development. Technology investment and digital transformation create demand for advanced packaging solutions. Suppliers succeed when they combine product quality, technical support, and manufacturing capability.
Segmentation Analysis
Wafer Bumping Process
Wafer Bumping Process is projected to grow at a CAGR of 4.5–5.2% during 2026–2034. Flip Chip Technology Market scope covers Copper Pillar, Lead-Free, Tin/Lead Eutectic Solder, and Gold Stud+ Plated Solder. Selection depends on application requirements and performance needs. Copper Pillar leads through established performance and widespread adoption.
- Copper Pillar provides reliable interconnect with superior electrical and thermal performance.
- Lead-Free bumping addresses environmental compliance and reliability requirements.
- Tin/Lead Eutectic Solder offers established, cost-effective interconnect solutions.
- Gold Stud+ Plated Solder provides specialized interconnect for specific applications.
Packaging Technology
Packaging Technology is forecast to grow at a CAGR of 4.8–5.5% during 2026–2034. 2D IC, 2.5D IC, and 3D IC represent integration levels.
- 2D IC packaging provides established flip chip integration with proven reliability.
- 2.5D IC packaging enables interposer-based integration for enhanced performance.
- 3D IC packaging delivers vertical integration for maximum density and performance.
Packaging Type
Packaging Type is expected to grow at a CAGR of 4.5–5.2% during 2026–2034. FC BGA, FC PGA, FC LGA, FC QFN, FC SiP, and FC CSP address diverse package requirements.
- FC BGA provides ball grid array packaging for high-performance applications.
- FC PGA offers pin grid array packaging for specific processor applications.
- FC LGA provides land grid array packaging for socketed applications.
- FC QFN offers quad flat no-lead packaging for compact applications.
- FC SiP enables system-in-package integration for multi-chip modules.
- FC CSP provides chip-scale packaging for space-constrained applications.
Product
Product is projected to grow at a CAGR of 4.8–5.5% during 2026–2034. Memory, LED, CMOS Image Sensor, RF, Analog, Mixed Signal, Power IC, CPU, SoC, and GPU represent key product categories.
- Memory applications require high-density flip chip interconnects.
- LED applications demand reliable flip chip for lighting and display.
- CMOS Image Sensor applications require advanced packaging for imaging.
- RF applications need high-frequency flip chip solutions.
- Analog applications demand precision interconnect capability.
- Mixed Signal applications require integrated interconnect solutions.
- Power IC applications need robust, high-current interconnects.
- CPU applications demand high-performance flip chip packaging.
- SoC applications require integrated, high-density solutions.
- GPU applications need advanced packaging for graphics processing.
Opportunity Snapshot
| Product | Revenue Contribution | Trend Tag | Adoption Stage |
|---|---|---|---|
| Memory | High | Data Storage | Mature |
| CPU | High | Processors | Mature |
| SoC | High | System Integration | Mature |
| GPU | High | Graphics Processing | Mature |
| RF | High | Wireless | Mature |
Flip Chip Technology Market Growth Drivers and Impact Analysis
Semiconductor Performance Requirements Drive Flip Chip Adoption
Semiconductor performance requirements across processors, memory, and communications devices are driving significant demand for flip chip technology, which enables improved electrical performance, efficient power delivery, and enhanced thermal management. As semiconductor architectures become more powerful and complex, conventional packaging approaches face increasing challenges in supporting higher performance and greater functionality within compact form factors. Flip chip packaging addresses these requirements by providing shorter interconnect paths, improved electrical characteristics, and more effective heat dissipation. Growing application demands are therefore accelerating adoption across advanced semiconductor devices. The practical market impact is increasing demand for advanced flip chip packaging solutions that can support higher performance, power efficiency, thermal control, and evolving semiconductor design requirements.
Miniaturization and Integration Needs Create Flip Chip Demand
Miniaturization and integration requirements across consumer electronics, automotive, and computing applications are driving demand for flip chip technology, which enables compact, high-density semiconductor packages. As devices and systems become smaller while incorporating greater functionality, manufacturers require packaging solutions that maximize space efficiency and support increased interconnect density. Flip chip technology addresses these needs by enabling direct die-to-substrate connections, shorter interconnect paths, and efficient use of package space. Growing integration requirements are expected to sustain demand across advanced electronic applications. This trend particularly benefits suppliers capable of delivering high-density, reliable flip chip packaging that meets demanding requirements for performance, miniaturization, thermal management, and long-term product reliability.
Advanced Packaging Adoption Drives Technology Growth
Advanced packaging adoption across the semiconductor and electronics industries is driving demand for flip chip technology as a foundational solution for 2.5D and 3D integration architectures. As manufacturers pursue greater performance, functionality, and integration within compact packages, flip chip technology provides the high-density interconnection capabilities required by increasingly sophisticated designs. The continued evolution of advanced packaging is therefore supporting consistent demand for flip chip solutions across high-performance applications. This trend creates opportunities for suppliers with established flip chip manufacturing expertise and advanced packaging capabilities. The market impact is increasing demand for reliable, high-density flip chip technologies that can support emerging architectures, complex interconnect requirements, and next-generation semiconductor packaging strategies.
Flip Chip Technology Market Future Trends
Smaller Bump Pitch Enables Higher Interconnect Density
Flip chip technology market trends increasingly point toward smaller bump pitches as semiconductor manufacturers seek higher interconnect density for advanced applications. Reduced bump pitch enables more connections within compact packages, supporting greater integration and increasingly sophisticated semiconductor designs. The next product cycle is expected to combine fine-pitch capabilities with improved reliability, addressing the challenges associated with high-density integration and demanding operating conditions. This shift is significant as semiconductor architectures continue to require greater interconnect density, performance, and functionality within smaller package footprints. Suppliers with strong fine-pitch flip chip expertise will be better positioned to meet evolving customer requirements and capture opportunities as high-density semiconductor packaging becomes increasingly important across advanced applications.
Hybrid Bonding Technology Enables Fine-Pitch Integration
Hybrid bonding technology in flip chip packaging is emerging as an important capability for enabling fine-pitch, high-density interconnects in advanced semiconductor applications. As semiconductor manufacturers pursue greater integration and performance within increasingly compact packages, hybrid bonding can support tighter interconnect spacing and more sophisticated packaging architectures. Next-generation packaging solutions are expected to incorporate hybrid bonding to address growing requirements for interconnect density, electrical performance, and advanced integration. This evolution creates opportunities for suppliers with established flip chip expertise and hybrid bonding capabilities. Companies that can demonstrate reliable hybrid bonding performance while maintaining established flip chip quality and manufacturing consistency will be better positioned to gain credibility with semiconductor designers and capture emerging advanced packaging opportunities.
Flip Chip Technology Market Opportunities
Advanced Flip Chip Solutions for High-Performance Computing
Flip chip technology market forecasts indicate growing opportunities for advanced flip chip solutions in high-performance computing (HPC), where processors and accelerators require exceptional interconnect density, electrical performance, and thermal efficiency. As computing workloads become more demanding, manufacturers increasingly rely on advanced packaging technologies to support higher processing capabilities within compact form factors. Flip chip technology provides the high-density interconnections and performance characteristics required for sophisticated computing architectures. This creates opportunities for suppliers to develop specialized, high-performance packaging solutions tailored to HPC applications. The strongest opportunities are expected in segments where rising demand for processors, accelerators, and AI computing drives the need for advanced flip chip packaging technologies.
3D IC Packaging for Memory and Logic Integration
3D IC packaging for memory and logic integration is creating growing demand for advanced flip chip solutions that support vertical integration and higher component density. As semiconductor developers pursue greater performance and functionality within compact form factors, 3D packaging technologies are becoming increasingly important for integrating multiple dies and reducing interconnect distances. Flip chip technology provides a key foundation for achieving the high-density connections required in advanced 3D architectures. This trend creates opportunities for suppliers with established expertise in 3D packaging, advanced interconnects, and flip chip manufacturing. Companies capable of delivering solutions that combine efficient integration, high performance, thermal management, and long-term reliability will be well positioned to capture opportunities in advanced semiconductor packaging applications.
Recent Developments
- August 2025: Indium Corporation, a leading materials refiner, smelter, manufacturer, and supplier, announced the global availability of WS-910 Flip-Chip Flux, a new water-soluble flip-chip dipping flux designed to meet the demands of cutting-edge semiconductor devices. WS-910 Flip-Chip Flux is designed to provide best-in-class residue cleaning for a water-soluble flip-chip flux, allowing for excellent compatibility with molded and capillary underfill. The new product also offers high tackiness for a flip-chip flux, which is useful when holding large die in place during the reflow process. WS-910 expands Indium Corporation’s extensive line of semiconductor assembly solutions, supporting advanced packaging and high-reliability applications.
- April 2025: Nexperia announced a new portfolio of high signal integrity, bidirectional electrostatic discharge (ESD) protection diodes in innovative flip-chip land-grid-array (FC-LGA) packaging. This new package technology is optimized for protecting and filtering high-speed data communication links which are increasingly used in modern cars. Applications like in-vehicle camera video-links, multi-gigabit automotive Ethernet networks as well as infotainment interfaces like USBx, HDMIx, and PCIex, can be protected against potentially damaging ESD events.
- March 2023: Jupiter Systems, the leading global manufacturer of 21:9 ultra-wide display solutions, formally announced the launch of Zavus Xtreme Pixel (XP) Flip Chip COB MicroLED. This customizable, large, seamless display solution is the latest addition to the company’s 21:9 ultra-wide display offerings, designed to meet the demands of enterprise and industrial companies that require visualization technology as a centerpiece.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners provided valuable market intelligence that supported our global go-to-market strategy. Their team was professional, responsive, and attentive to our feedback, providing thoughtful analysis and helpful methodological clarifications throughout the project.
Junmo Kim Chief Financial Officer (CFO), Enertech Co., Ltd.
The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for