
Industrial Gases Market Growth, Share & Trends by 2034
Coverage: By Product (Oxygen, Nitrogen, Hydrogen, Carbon dioxide, Others); End User Industry (Automotive, Healthcare, Electronics, Aerospace, Construction, Energy & Power, Others) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00009525
- Category : Chemicals and Materials
- No. of Pages : 150
- Available Report Formats :


- Last update date : August 28, 2026


2025 Market Size
US$ 113.16 Bn
Base year value
2034 Forecast
US$ 197.59 Bn
Projected by 2034
CAGR 2026-2034
6.39 %
Growth rate
Addressable Market
US$ 1,405.98 Bn
(2026-2034)
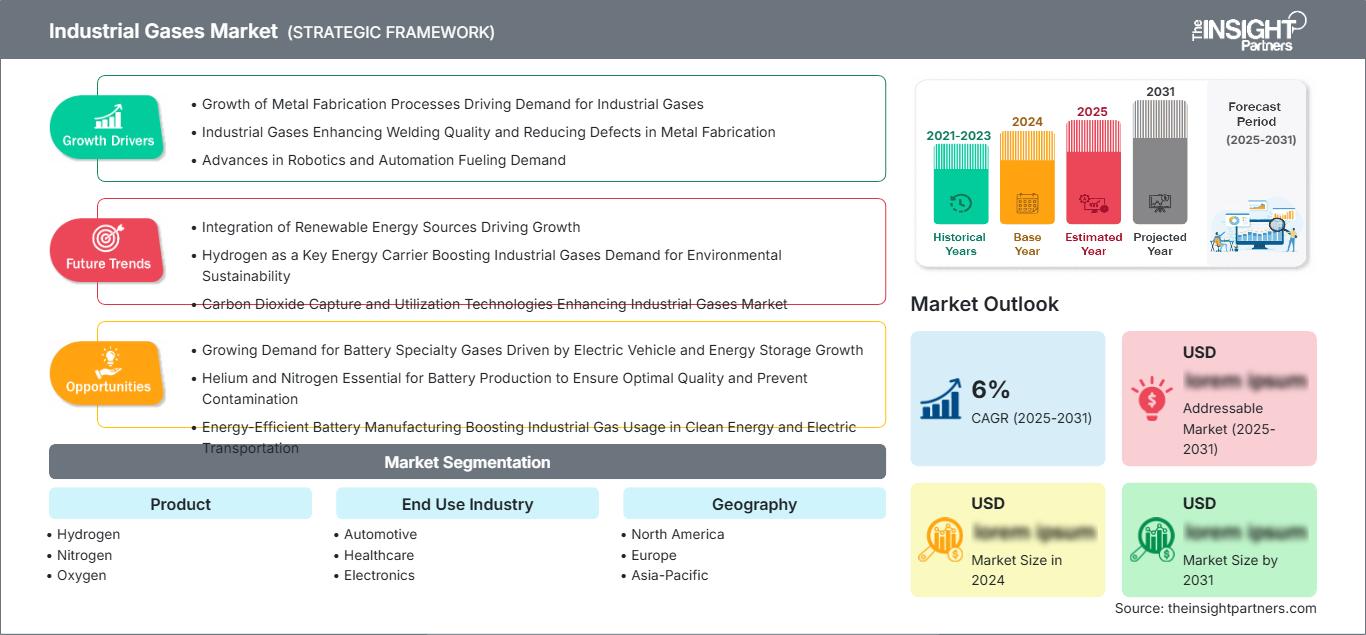
The industrial gases market is projected to grow from US$ 113.16 Billion in 2025 to US$ 197.59 Billion by 2034, registering a CAGR of 6.39% during 2026–2034. Growth reflects expanding requirements for atmospheric and process gases across manufacturing, healthcare, electronics, energy systems, and advanced industrial applications, while investment in hydrogen, carbon management, and high-purity gas infrastructure continues to reshape production and distribution strategies.
North America is expected to remain a strategically important demand center, with growth estimated in the 5.8–6.4% range during 2026–2034. Semiconductor fabrication expansion, aerospace activity, industrial reshoring, and investment in low-carbon ammonia and hydrogen projects are strengthening requirements for nitrogen, oxygen, argon, hydrogen, and carbon dioxide. The industrial gases market size in the region is also supported by established pipeline networks and a high concentration of large industrial customers.
Industrial Gases Market Assessment and Insights
- North America accounted for an estimated 30–34% share in 2025 and is expected to grow at a CAGR of 5.8–6.4% during 2026–2034. Semiconductor investment, aerospace production, healthcare requirements, and large-scale energy projects continue to support demand for atmospheric, process, and specialty gases.
- US represented approximately 78–82% of North American demand in 2025 and is projected to expand at a CAGR of 5.9–6.5% during 2026–2034, supported by semiconductor manufacturing, industrial reshoring, space activity, and low-carbon industrial projects.
- Europe held an estimated 24–28% share in 2025 and is expected to grow at a CAGR of 5.2–5.9% during 2026–2034. Germany, France, the UK, Italy, and Spain remain important markets, supported by manufacturing modernization, healthcare demand, electronics, and decarbonization investments.
- Asia Pacific accounted for an estimated 32–36% share in 2025 and is projected to record a CAGR of 7.2–8.0% during 2026–2034. China, Japan, South Korea, India, and Australia benefit from electronics production, metals, chemicals, infrastructure, and hydrogen-related investment.
- Largest Segment: Nitrogen represented an estimated 27–31% market share in 2025 and is expected to grow at a CAGR of 6.1–6.8% during 2026–2034, supported by electronics, food processing, chemicals, and industrial blanketing applications.
- High Growth Segment: Hydrogen accounted for an estimated 17–21% market share in 2025 and is projected to grow at a CAGR of 8.0–9.0% during 2026–2034, driven by refining, chemicals, ammonia, mobility, and low-emissions industrial investment.
- Key companies analyzed in detail: Air Liquide S.A., Linde plc, Air Products and Chemicals, Inc., Messer SE & Co. KGaA, Nippon Sanso Holdings Corporation, BASF SE, Gulf Cryo Holding Company W.L.L., Yingde Gases Group Co., Ltd., Chengdu Taiyu Industrial Gases Co., Ltd., Ellenbarrie Industrial Gases Limited, Bhuruka Gases Limited, Mohsin Haider Darwish LLC, Southern Gas Limited, Buzwair Industrial Gases Factories, Tripti Gases Private Limited, Universal Boschi Private Limited, and INMATEC GaseTechnologie GmbH & Co. KG.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
Economics of production have gradually evolved from rather standardized merchant supplies to those that are highly customized, digitalized, and customer-oriented. Large-scale plants for air separation, hydrogen production, CO2 capture, and on-site generation facilities are being planned and designed based on long-term contracts with customers. This has enhanced the supply security but has also raised the amount of capital involved. The electronics industry requires increasing supplies of ultra-high-purity gases, whereas industrial decarbonization calls for oxygen, hydrogen, CO2 capture, and related engineering systems.
The outlook increasingly favors markets combining manufacturing expansion with reliable power, logistics, and supportive industrial policy. India, Southeast Asia, the Gulf states, and selected African economies offer expanding opportunities for localized production and distribution. At the same time, regulations related to emissions, clean fuels, semiconductor supply chains, and industrial resilience is encouraging investment in new capacity. The industrial gases market is therefore expected to evolve through a combination of conventional volume growth and higher-value application development.
Industrial Gases Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 113.16 Billion |
| Market Size by 2034 | US$ 197.59 Billion |
| Global CAGR (2026 - 2034) | 6.39% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Industrial Gases Market Analysis
Manufacturing activity remains the fundamental demand base because gases are embedded throughout metals processing, chemicals, fabrication, welding, food preservation, electronics, and healthcare supply chains. The industrial gases market growth is increasingly linked to customer investment cycles rather than broad industrial output alone. The big customers prefer onsite plants and pipelines in cases where the demand for the gases is continuous in nature, while the distributed customers use bulk liquid and packaged gas network systems. Thus, there is a multilayered value chain that includes production, purification, liquefaction, storage, transportation, engineering, and technical services.
The supply dynamics are very much dependent on the availability of electricity, the feedstock economy, logistics intensity, and proximity to the customers. The atmospheric gases can leverage economies of scale due to their air separation technology, while hydrogen economics will depend on natural gas, electricity, carbon handling, and the cost of transportation. Thereby, producers use central plants along with merchant systems and small on-site plants.
Competitive positioning is defined by installed infrastructure, engineering capability, customer relationships, and the ability to finance capital-intensive projects. The industrial gases market analysis indicates that global leaders continue to prioritize large projects linked to electronics, chemicals, refining, and energy transition applications. Air Liquide S.A., Linde plc, and Air Products and Chemicals, Inc. maintain broad international footprints, while Messer SE & Co. KGaA and Nippon Sanso Holdings Corporation strengthen regional and application-specific positions.
The capital investments are now focused more on plants that have guaranteed demand compared to any capacity expansion. BASF SE still holds its importance in terms of integrated chemical plants and industrial gases requirements; regional producers like Gulf Cryo Holding Company W.L.L., Yingde Gases Group Co., Ltd., Chengdu Taiyu Industrial Gases Co., Ltd., and Ellenbarrie Industrial Gases Limited cater to local demands; while Bhuruka Gases Limited, Mohsin Haider Darwish LLC, Southern Gas Limited, Buzwair Industrial Gases Factories, Tripti Gases Private Limited, Universal Boschi Private Limited, and INMATEC GaseTechnologie GmbH & Co. KG add their own specific strengths to the mix.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Industrial Gases Market: Strategic Insights
Regional Insights
North America Industrial Gases Market
North America accounted for an estimated 30–34% of the industrial gases market share in 2025 and is projected to expand at a CAGR of 5.8–6.4% during 2026–2034. The demand for nitrogen, oxygen, argon, and hydrogen gases is growing owing to the growth in the fabrication of semiconductors, aerospace operations, advanced manufacturing, and low-carbon industrial projects. The availability of pipelines and high engineering capacity in the region allows suppliers to connect their production capacity directly to large industrial operations.
Investments made in energy transition have led to further demand for oxygen and hydrogen in ammonia, refining, carbon capture, and chemicals. Linde has made significant investments in support of commercial space and low-carbon ammonia facilities in the US.
U.S. Industrial Gases Market
The U.S. represented approximately 78–82% of North American Industrial Gases Market demand in 2025 and is expected to grow at a CAGR of 5.9–6.5% during 2026–2034. The strong manufacturing industry drives a large consumption base in chemicals, refining, metals, electronics, healthcare, aerospace, and construction. Companies such as Air Liquide S.A., Linde plc, Air Products and Chemicals, Inc., Messer SE & Co. KGaA, and others are the reasons for investing in major facilities connected to pipelines and merchant facilities.
As far as application trends go, the use of ultra-high purity gases in semiconductors' manufacturing, liquid oxygen and liquid nitrogen for commercial space activities, and hydrogen for refineries and chemicals plants is increasing. Investments made recently prove that the capital investment in electronics and large-scale projects continues. Air Liquide made the announcement about US$ 150 million investment in a new Idaho facility that will be used for advanced memory chip manufacturing using nitrogen, oxygen, and argon until 2028.
Europe Industrial Gases Market
Europe held an estimated 24–28% share of the Industrial Gases Market in 2025 and is expected to expand at a CAGR of 5.2–5.9% during 2026–2034. Germany remains the leading regional market due to its chemicals, engineering, automotive, metals, and electronics industries. The UK benefits from aerospace, life sciences, industrial manufacturing, and engineering activity, while France maintains strong demand through chemicals, healthcare, energy, and advanced manufacturing applications.
Germany is expected to remain the principal European demand center as manufacturers invest in semiconductor capacity and lower-emissions industrial processes. Air Liquide has committed significant investment toward industrial gas infrastructure supporting electronics production in the country. France, Italy, and Spain also provide diversified demand through refining, food and beverage processing, healthcare, construction, automotive production, and renewable energy development. Their combined importance supports a broad regional market structure rather than dependence on a single national demand center.
APAC Industrial Gases Market
APAC accounted for an estimated 32–36% share of the Industrial Gases Market in 2025 and is projected to grow at a CAGR of 7.2–8.0% during 2026–2034, making it the fastest-expanding major regional market. China leads through chemicals, metals, electronics, and hydrogen infrastructure, while Japan and South Korea remain important for semiconductor and advanced manufacturing gases. India is supported by infrastructure, steel, automotive, healthcare, and electronics expansion. Australia contributes through mining, metals, and energy-related demand.
Industrial policy and semiconductor investment are reshaping regional supply patterns. China has remained central to electrolyzer deployment, while South Korea continues to attract major investments in electronics-related gas infrastructure.
Middle East & Africa Industrial Gases Market
The Middle East & Africa Industrial Gases Market is expected to grow at a CAGR of 6.5–7.3% during 2026–2034. Saudi Arabia and the UAE lead regional investment through refining, petrochemicals, hydrogen, construction, and infrastructure, while South Africa remains important for mining, metals, chemicals, and healthcare applications.
Energy infrastructure provides the region with large-scale demand anchors, although supply disruptions and project execution risks can affect hydrogen-related investment. The Middle East accounts for around one-sixth of global hydrogen production, underlining its importance within hydrogen-based industrial value chains.
Segmentation Analysis
Product
Product demand of the Industrial Gases Market reflects differences in industrial processes, purity requirements, storage characteristics, and distribution economics. This segment is expected to grow at a CAGR of 6.4–7.1% during 2026–2034. Atmospheric gases retain broad volume demand, while hydrogen and carbon dioxide are increasingly influenced by decarbonization and carbon-management investments. The industrial gases market scope therefore, extends from high-volume commodity applications to highly specialized supply systems supporting electronics and advanced manufacturing.
- Hydrogen supports refining, ammonia, chemicals, metals, mobility, and emerging low-emissions applications, making it strategically important despite significant project economics and infrastructure challenges.
- Nitrogen is the largest product category because inerting, blanketing, food processing, electronics, chemicals, and cryogenic applications create diversified and relatively resilient consumption patterns.
- Oxygen remains essential for steelmaking, combustion enhancement, healthcare, wastewater treatment, chemicals, and gasification, supporting substantial requirements from large industrial facilities.
- Argon serves welding, metals processing, electronics, laboratories, and specialized manufacturing, where inert atmospheres and controlled processing conditions support consistent demand.
- Carbon Dioxide is used across food and beverage, chemicals, welding, refrigeration, water treatment, and carbon-management applications, although availability can depend on linked industrial production sources.
End Use Industry
End-use diversification reduces dependence on any single manufacturing cycle and supports long-term demand across essential industries in the Industrial Gases Market. This segment is projected to grow at a CAGR of 6.3–7.0% during 2026–2034. Automotive and construction require gases for fabrication and welding, while healthcare and electronics emphasize reliability and purity. Energy and power applications increasingly incorporate hydrogen, oxygen, and carbon dioxide management within changing industrial and infrastructure systems.
- Automotive demand is supported by welding, heat treatment, component manufacturing, metal processing, testing, and growing requirements from battery and advanced-material production.
- Healthcare requires reliable oxygen and medical gas supply, creating demand for centralized production, cylinders, bulk storage, and distribution systems with stringent quality controls.
- Electronics is strategically important because semiconductor fabrication requires uninterrupted access to ultra-high-purity atmospheric and specialty gases within highly controlled production environments.
- Aerospace uses industrial gases for propulsion testing, welding, fabrication, cryogenic operations, and launch systems, supporting specialized high-reliability supply contracts.
- Construction consumes gases through metal cutting, welding, concrete-related processes, equipment manufacturing, and infrastructure fabrication, linking demand to broader capital investment cycles.
- Energy and Power increasingly use hydrogen, oxygen, nitrogen, and carbon dioxide in refining, ammonia, gas processing, carbon capture, and emerging low-carbon fuel systems.
Opportunity Snapshot
| End Use Industry | Revenue Contribution | Trend Tag | Adoption Stage |
| Automotive | High | Battery Materials | Mature |
| Healthcare | High | Medical Oxygen | Mature |
| Electronics | High | Chip Fabrication | Scaling |
| Aerospace | Medium | Launch Systems | Scaling |
| Construction | Medium | Infrastructure Welding | Mature |
| Energy and Power | High | Clean Ammonia | Scaling |
Industrial Gases Market Growth Drivers and Impact Analysis
Semiconductor Capacity Expansion Raises High-Purity Gas Requirements
The production of semiconductors is making ultra-high purity nitrogen, oxygen, argon, hydrogen, and process gases more strategically important. New fabrication plants will need continuous supply, duplicate facilities, high purity control, and long-term business contracts. This driver will benefit suppliers who have engineering expertise and enough capital to install their own plants. Linde added to its industrial gases supply contract at Samsung’s Pyeongtaek facility by adding another air separation unit, while Air Liquide has been making investments in semiconductor-related capacities. The effect that it will have on the market is not limited to gas volume, since the customers in the semiconductor industry now demand integration of the supply chain.
Industrial Decarbonization Expands Hydrogen and Oxygen Investment
Decarbonization is increasing demand for hydrogen, oxygen, carbon dioxide handling, and related engineering services. While hydrogen usage is mostly focused on refineries and industries, low-emissions projects are increasing slowly in terms of production and consumption of low-emissions hydrogen. Global demand for hydrogen exceeded 100 million tonnes in 2025, while global low-emissions hydrogen production exceeded 1 million tonnes, thus indicating the level of current demand and the early stage of development of the more environmentally friendly hydrogen production. For gas providers, the decarbonization trend opens up possibilities for developing electrolysis, carbon capture, air separation, ammonia, and pipeline projects in areas with dense industrial clusters.
Healthcare and Essential Manufacturing Strengthen Supply Resilience
Healthcare, food processing, chemicals, and manufacturing need a reliable supply of gases irrespective of any temporary changes in non-essential industrial activities. Healthcare oxygen and nitrogen for preservation/processing and controlled atmosphere uses create a reliable foundation for usage. Security of supply is hence becoming one of the key criteria of purchase, along with pricing and performance. Manufacturers react to that trend by building production centers in regions, storage, remote monitoring, and diversified distribution. It leads to the development of local capabilities, especially in emerging countries that have rapidly growing health care and industrial manufacturing needs at the same time. The result is a more diverse market, where essential use creates regular demand and growth areas generate extra demand for premium products/services.
Industrial Gases Market Future Trends
On-Site and Digitally Managed Supply Models Will Expand
The industrial gases market trends increasingly favor digitally connected production assets designed around customer consumption patterns. Remote monitoring, predictive maintenance, automated replenishment, and real-time purity management can improve reliability and asset utilization. Large customers are also expected to prefer on-site production where consumption volumes justify dedicated infrastructure. This model reduces transportation exposure and strengthens long-term supplier relationships. Future competition will therefore extend beyond molecule production toward engineering integration, operational analytics, and service quality. Suppliers able to combine large-scale air separation or hydrogen assets with digital monitoring and flexible distribution networks should be better positioned to serve increasingly complex manufacturing and infrastructure customers.
Low-Emissions Hydrogen Will Shift Toward Contracted Industrial Hubs
Hydrogen development is expected to become increasingly concentrated around existing industrial demand rather than widely dispersed speculative projects. High costs, uncertain offtake, and infrastructure gaps continue to constrain deployment, favoring facilities linked to refineries, chemicals, ammonia, and other established consumers. The IEA expects committed low-emissions hydrogen production and consumption in industrial applications to expand materially toward 2030. Future projects are therefore likely to prioritize contracted customers, shared infrastructure, and policy-supported industrial clusters. This trend can improve asset utilization, reduce logistics complexity, and create more investable project structures for gas producers and infrastructure partners.
Industrial Gases Market Opportunities
Localized Gas Infrastructure in High-Growth Manufacturing Economies
The industrial gases market Forecasts indicate attractive opportunities for investment in localized production and distribution infrastructure across India, Southeast Asia, and selected Middle Eastern and African industrial centers. Rapid growth in electronics, automotive production, metals, healthcare, and construction can create demand that exceeds the efficiency of long-distance gas transport. Investors can target modular air separation, packaged gases, liquid distribution, and on-site generation systems near emerging industrial clusters. Air Liquide’s expansion through the acquisition of NovaAir demonstrates the strategic value of strengthening localized capabilities in India across multiple industrial sectors. Partnerships with industrial parks and anchor manufacturers can improve utilization and reduce customer-acquisition risk.
Carbon Capture and Low-Carbon Molecules Create Integrated Projects
Integrated projects combining hydrogen, oxygen, nitrogen, carbon dioxide capture, and downstream processing offer opportunities beyond conventional gas supply. Investment can focus on ammonia, refining, chemicals, cement, and other sectors where large emission sources coincide with substantial gas consumption. Linde and other major suppliers are developing projects that combine air separation and decarbonization infrastructure around large industrial customers. The strongest opportunities will involve long-term offtake, shared infrastructure, and customers with identifiable decarbonization pathways. Developers can improve project economics by integrating multiple gas streams and technical services instead of relying on standalone production assets.
Recent Developments
- April 2026: Air Products expanded its US industrial gas footprint with plans to build, own and operate a new air separation unit (ASU) in Cocoa, Florida, reinforcing its push into high-demand industrial and space-sector markets.
- October 2025: Air Liquide announced the acquisition and integration of NovaAir, expanding its industrial gas footprint across East and South India. NovaAir serves customers in steel, automotive, fabrication, electronics, photovoltaic manufacturing, and healthcare, complementing Air Liquide's existing operations in northern and western India and strengthening its ability to provide production, bulk supply, specialty gases, onsite services, and engineering support.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for