
Zero Trust Architecture Market Demand, Share & Growth by 2034
Zero Trust Architecture Market Size and Forecasts (2021–2034), Global and Regional Share, Trends, and Growth Opportunity Analysis Report Coverage : By Offering (Solutions, Services); Organization Size (SMEs and large ); Deployment (Cloud and On-Premises ) Vertical (Consumer Electronics, IT & Telecom, Automotive, Manufacturing, Construction And Building, Healthcare And Medical Devices, Others )
- Status : Data Released
- Report Code : TIPRE00039684
- Category : Technology, Media and Telecommunications
- No. of Pages : 150
- Available Report Formats :


- Last update date : August 04, 2026


2025 Market Size
US$ 40.62 Bn
Base year value
2034 Forecast
US$ 133.88 Bn
Projected by 2034
CAGR 2026-2034
16.08 %
Growth rate
Addressable Market
US$ 828.86 Bn
(2026-2034)
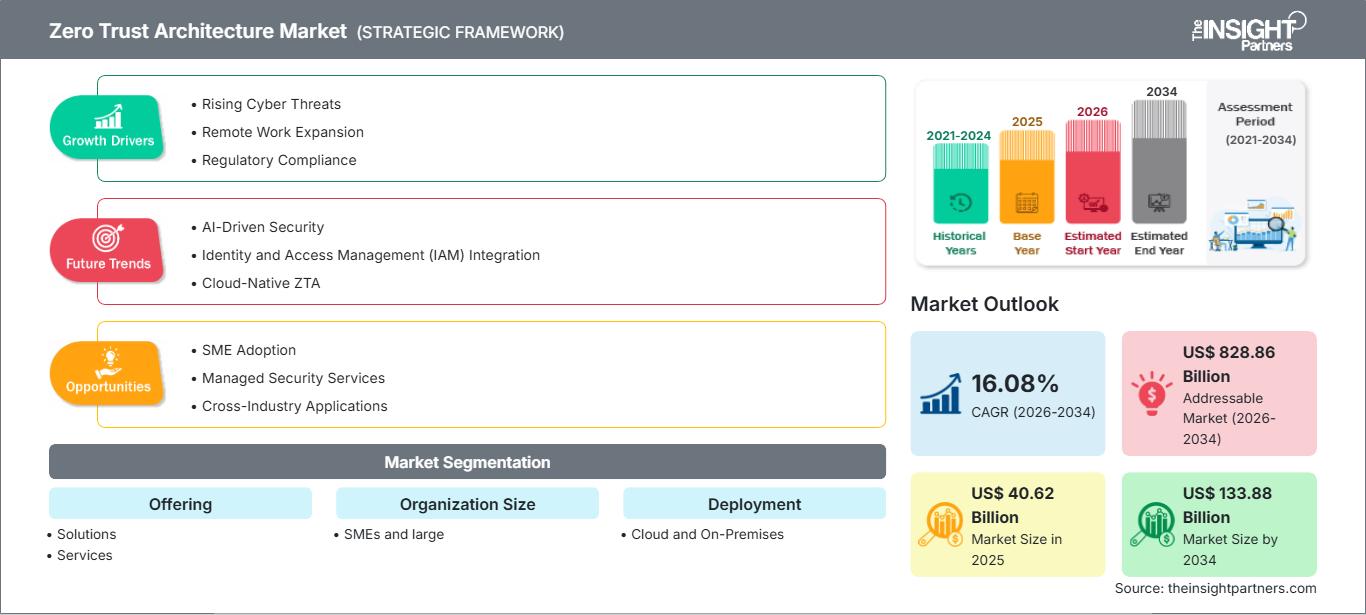
The zero trust architecture market was valued at US$ 40.62 Billion in 2025 and is projected to reach US$ 133.88 Billion by 2034, expanding at a CAGR of 16.08% during 2026–2034. The market is benefiting from rising cybersecurity threats, increasing enterprise migration toward cloud-native environments, and stricter data protection requirements. Organizations across regulated industries are accelerating identity-centric security deployments to reduce lateral movement risks and improve resilience against sophisticated cyberattacks.
Across North America, enterprise spending on identity verification, secure access service edge platforms, and continuous authentication frameworks continues to expand. The zero trust architecture market size in the region is supported by large-scale digital transformation programs, extensive cloud adoption, and regulatory pressure surrounding critical infrastructure protection. Market growth is expected to remain strong, with regional expansion estimated in the range of 14.5%–16.5% CAGR during 2026–2034, supported by public and private sector cybersecurity investments.
Zero Trust Architecture Market Assessment and Insights
- North America: The region remains the leading revenue contributor due to advanced cybersecurity spending, mature cloud infrastructure, and federal security mandates. Share in 2025: 38%–42%. CAGR between 2026–2034: 14.5%–16.5%.
- US: Strong adoption across government, financial services, healthcare, and technology sectors supports regional leadership. Share of North America in 2025: 78%–82%. CAGR between 2026–2034: 14.8%–16.8%.
- Europe: Data sovereignty initiatives and cybersecurity regulations drive adoption across the UK, Germany, France, Italy, and Spain. Share in 2025: 24%–28%. CAGR between 2026–2034: 15.0%–17.0%.
- Asia Pacific: Rapid digitalization, expanding cloud deployments, and growing cybersecurity budgets in China, Japan, India, South Korea, and Australia support expansion. Share in 2025: 22%–26%. CAGR between 2026–2034: 17.5%–19.5%.
- Largest Segment: Solutions dominates implementation spending due to demand for identity governance, network segmentation, and access control technologies. Market share in 2025: 62%–66%. CAGR between 2026–2034: 15.5%–17.5%.
- High Growth Segment: Cloud Deployment benefits from enterprise migration toward hybrid and multi-cloud environments. Market share in 2025: 54%–58%. CAGR between 2026–2034: 18.0%–20.0%.
- Key companies analyzed in detail: Palo Alto Networks, Inc.; VMware LLC; Zscaler, Inc.; Akamai Technologies, Inc.; Microsoft Corporation; Cisco Systems, Inc.; International Business Machines Corporation; Cloud Software Group, Inc. (Citrix); Trellix; Forcepoint LLC.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The market has transformed from the use of security architecture based on perimeters to the implementation of security models centered on identity that can accommodate users, applications, and devices in a distributed environment. The use of the cloud, remote working, and connected operation technology systems has fast-tracked the growth of this market. Security approaches have been shifting towards continuous authentication, micro-segmentation, endpoint visibility, and risk-based access control mechanisms. With the increasing sophistication of cyber attacks, there is a need to incorporate analytics and automation in security processes.
Looking ahead, investment momentum in the Zero Trust Architecture Market is expected to strengthen across the Asia Pacific, the Middle East, and selected European economies where digital infrastructure programs continue to expand. Government cybersecurity frameworks, critical infrastructure protection initiatives, and stricter privacy regulations are creating favorable adoption conditions. Demand from healthcare, telecommunications, manufacturing, and financial institutions is expected to support long-term implementation activity, while cloud-native security platforms and artificial intelligence-enabled monitoring tools improve scalability and operational effectiveness.
Zero Trust Architecture Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 40.62 Billion |
| Market Size by 2034 | US$ 133.88 Billion |
| Global CAGR (2026 - 2034) | 16.08% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Zero Trust Architecture Market Analysis
Growing cyber threats, ransomware incidents, and identity-based attacks continue to accelerate enterprise security modernization efforts. The zero trust architecture market growth trajectory is supported by organizations replacing legacy perimeter defenses with continuous verification frameworks that authenticate users, devices, and applications throughout digital sessions. Adoption is particularly strong among regulated industries where compliance requirements demand enhanced visibility, access governance, and data protection controls.
The broader ecosystem in the Zero Trust Architecture Market includes security software vendors, cloud providers, managed security service providers, systems integrators, and infrastructure specialists. Demand for secure access technologies, identity governance platforms, privileged access management solutions, and micro-segmentation tools is increasing as enterprises expand hybrid work environments. Supply dynamics remain favorable due to ongoing product innovation and growing integration capabilities across cloud, endpoint, and network security platforms.
The competitive environment remains highly dynamic, with established cybersecurity vendors expanding platform capabilities through acquisitions, strategic partnerships, and product innovation. The zero trust architecture market analysis indicates that leading suppliers are focusing on unified security architectures that combine identity management, threat intelligence, endpoint protection, and cloud security into integrated platforms. Such strategies enable customers to simplify deployment while improving security outcomes.
Key players such as Palo Alto Networks, Microsoft Corporation, Cisco Systems, International Business Machines Corporation, Zscaler, Akamai Technologies, VMware, Trellix, Forcepoint, and Citrix are making further efforts towards cloud-based security solutions and AI-powered threat detection. The focus is shifting from one-off products to platform compatibility, policy automation, and scalability. Players that are able to provide cloud and multi-cloud solutions in an easy-to-implement manner are likely to gain a competitive edge in the coming years.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Zero Trust Architecture Market: Strategic Insights
Regional Insights
North America zero trust architecture market
North America accounted for approximately 38%–42% of global revenue in the Zero Trust Architecture Market in 2025 and remains the largest regional contributor. The region benefits from extensive cybersecurity spending, high cloud adoption rates, and a strong regulatory focus on protecting critical infrastructure. Federal cybersecurity modernization programs, increasing ransomware threats, and growing digital transformation investments continue supporting enterprise implementation across government agencies and private organizations.
The region is expected to expand at a 14.5%–16.5% CAGR during 2026–2034. Large enterprises are accelerating the deployment of identity verification, privileged access management, and network segmentation technologies. The zero trust architecture market share remains substantial in North America because of advanced technology ecosystems, established vendor presence, and strong demand from financial services, healthcare, defense, and telecommunications sectors seeking improved cyber resilience and operational security.
U.S. zero trust architecture market
The United States represents approximately 78%–82% of North American revenue in the Zero Trust Architecture Market in 2025. Federal cybersecurity directives, expanding cloud migration initiatives, and increasing awareness of identity-centric security frameworks support sustained adoption. Large enterprises and public institutions continue prioritizing security modernization programs designed to address sophisticated cyber threats targeting critical digital assets and operational systems.
Growth in the country is projected at 14.8%–16.8% CAGR during 2026–2034. The presence of leading cybersecurity vendors, advanced cloud infrastructure, and significant research and development investment contributes to market maturity. Demand remains particularly strong across government, banking, healthcare, technology, and defense applications, where continuous authentication and access governance capabilities play a critical role in strengthening enterprise security strategies.
Europe zero trust architecture market
Europe held approximately 24%–28% of global revenue in the Zero Trust Architecture Market in 2025 and continues to benefit from regulatory frameworks emphasizing privacy, data protection, and cyber resilience. The region is projected to grow at a 15.0%–17.0% CAGR during 2026–2034. Strong implementation activity is observed across financial services, healthcare, manufacturing, and public-sector organizations seeking advanced security controls and compliance capabilities.
In addition, the UK is one of the leaders of adoption as it is characterized by high digital infrastructure development, high cybersecurity budgeting, and higher enterprise cloud adoption rates. The country of Germany is aided by industrial cybersecurity policies, as well as its high degree of manufacturing digitization initiatives. In addition, countries such as France, Italy, and Spain have been continuously investing in their cybersecurity budgets.
APAC zero trust architecture market
Asia Pacific represented approximately 22%–26% of global revenue in the Zero Trust Architecture Market in 2025 and is expected to register the fastest regional expansion. Growth is forecast at a 17.5%–19.5% CAGR during 2026–2034, supported by digital transformation initiatives, cloud adoption, and rising cybersecurity awareness across major economies. China, Japan, India, South Korea, and Australia remain key contributors as governments and enterprises increase investments in cyber resilience, identity security, and cloud-native protection frameworks.
China and Japan remain significant contributors, while India and South Korea are experiencing rapid implementation growth. Australia continues to strengthen cybersecurity frameworks across public and private sectors. Government digitalization programs, expanding internet penetration, and increasing enterprise investments in cloud infrastructure support sustained market development across the region.
Middle East & Africa zero trust architecture market
The Middle East & Africa Zero Trust Architecture Market continues to benefit from infrastructure modernization, digital government initiatives, and growing cybersecurity awareness. Energy, utilities, telecommunications, and financial services sectors are increasingly implementing identity-centric security frameworks to strengthen operational resilience and improve protection against evolving cyber threats.
Regional growth is expected at a 16.5%–18.5% CAGR during 2026–2034. Saudi Arabia and the United Arab Emirates lead adoption through smart city and digital economy initiatives, while South Africa remains an important market for enterprise cybersecurity investment. Continued infrastructure development and cloud adoption are expected to support long-term implementation activity.
Segmentation Analysis
Offering
The Offering segment is projected to expand at a 15.5%–17.5% CAGR during 2026–2034. The zero trust architecture market scope within this segment continues to broaden as organizations invest in integrated security technologies that improve visibility, access governance, and threat detection. Demand is supported by increasing cyber risk exposure, regulatory requirements, and enterprise efforts to modernize legacy security infrastructure while improving operational efficiency.
- Solutions: Solutions account for the largest portion of spending due to the broad deployment of identity management, authentication, network segmentation, and access control technologies supporting enterprise-wide cybersecurity transformation initiatives.
- Services: Services remain strategically important as organizations require consulting, integration, deployment, training, and managed security capabilities to accelerate implementation and improve operational effectiveness.
Organization Size
The Organization Size segment is expected to register a 15.8%–17.8% CAGR during 2026–2034. Adoption continues expanding across both large enterprises and smaller organizations as cyber threats become increasingly sophisticated. Cost-efficient cloud delivery models and managed services are improving accessibility while enabling organizations to strengthen security postures without extensive infrastructure investments.
- SMEs: Small and medium-sized enterprises increasingly adopt identity-centric security models to address ransomware risks, improve compliance, and secure expanding digital operations with limited internal cybersecurity resources.
- Large: Large organizations remain major adopters due to complex IT environments, extensive regulatory obligations, and significant requirements for access governance, continuous authentication, and enterprise-scale security visibility.
Deployment
The Deployment segment is forecast to grow at a 17.0%–19.0% CAGR during 2026–2034. Organizations are evaluating deployment strategies based on regulatory requirements, operational flexibility, scalability, and existing infrastructure investments. Hybrid approaches remain common as enterprises balance performance, compliance, and security considerations across diverse operating environments.
- Cloud: Cloud deployment benefits from scalability, faster implementation, subscription-based consumption models, and strong alignment with hybrid workforce strategies and multi-cloud application environments.
- On-Premises: On-premises deployment remains relevant for organizations requiring greater control over sensitive data, regulatory compliance, and integration with established security and infrastructure environments.
Vertical
The Vertical segment is projected to expand at a 16.2%–18.2% CAGR during 2026–2034. Industry-specific adoption patterns are influenced by cybersecurity maturity, digital transformation activity, regulatory requirements, and exposure to operational disruption risks. Critical infrastructure operators and highly regulated sectors remain among the most active adopters of advanced security frameworks.
- Consumer Electronics: Growing connected-device ecosystems and supply chain complexity encourage stronger identity management and access control implementations across production and service environments.
- IT & Telecom: High network complexity, extensive cloud utilization, and increasing cyberattack exposure support substantial adoption of continuous verification and advanced access management solutions.
- Automotive: Connected vehicle development, software-defined architectures, and increasing digital integration are driving stronger cybersecurity investment throughout automotive value chains.
- Manufacturing: Industrial automation, smart factory deployments, and operational technology connectivity increase demand for segmentation, visibility, and secure access management capabilities.
- Construction And Building: Digital project management platforms, connected infrastructure, and cloud-based collaboration tools support growing cybersecurity modernization requirements.
- Healthcare And Medical Devices: Protection of sensitive patient information, connected medical equipment, and regulatory compliance requirements continue driving adoption of advanced security architectures.
Opportunity Snapshot
| Vertical | Revenue Contribution | Trend Tag | Adoption Stage |
| Consumer Electronics | Medium | Device Identity | Scaling |
| IT & Telecom | High | Secure Access | Mature |
| Automotive | Medium | Connected Vehicle | Scaling |
| Manufacturing | High | OT Security | Scaling |
| Construction And Building | Low | Digital Projects | Emerging |
| Healthcare And Medical Devices | High | Clinical Security | Scaling |
Zero Trust Architecture Market Growth Drivers and Impact Analysis
Expansion of Cloud-Native Enterprise Infrastructure
The migration of the enterprise workload to public, private, or hybrid cloud computing infrastructures is leading to an increased need for identity-based security solutions. Enterprises are dealing with a large number of users, devices, applications, and flows in distributed infrastructures where traditional perimeters provide minimal protection. Cloud operations mandate the need for constant authentication, policy enforcement, and access controls. Enterprises are looking to invest in modern security architectures that help them achieve better visibility and resiliency. In addition to this, as the adoption of multi-cloud infrastructures grows, enterprises are looking at unified security platforms that can help secure their users and workloads irrespective of their locations.
Rising Sophistication of Cyberattacks and Ransomware Activity
Organized gangs of cyber criminals are shifting from using network penetration methods to going after identities, credentials, and privileged accounts. The increase in the number of ransomware attacks, supply chain attacks, and credential attacks is leading to the need for continuous authentication. Organizations are incorporating identity governance, endpoint validation, behavioral analysis, and access management systems to minimize the surface area and prevent lateral movement in the network. Operators of critical infrastructure, financial organizations, healthcare companies, and government departments still continue to concentrate on increasing their cyber resilience. Advanced security frameworks are also being backed by cyber risk awareness at the board level.
Strengthening Regulatory and Compliance Requirements
Governments and regulatory agencies around the globe are imposing tough cybersecurity requirements with the objective of ensuring that vital infrastructures, personal data, and various other digital services are secure from all threats. Identity and access management, data security and monitoring requirements are becoming increasingly prevalent in compliance frameworks. Organizations that operate in regulated industries have been required to exhibit better security governance and risk management processes. Privacy protection, operational resilience, and critical infrastructure security requirements are driving technology adoption. Organizations are implementing advanced security architectures to ensure that they are more ready for audits while minimizing any risks associated with compliance. Developments in the realm of regulations in North America, Europe, Asia Pacific, and the Middle East will continue to drive market growth.
Zero Trust Architecture Market Future Trends
Artificial Intelligence Integration Across Security Operations
The zero trust architecture market trends increasingly reflect the integration of artificial intelligence and machine learning into security operations. Future platforms are expected to provide predictive threat detection, behavioral analytics, automated policy recommendations, and adaptive authentication capabilities. Organizations will use AI-enabled systems to evaluate contextual risk in real time while reducing manual intervention requirements. As enterprise environments become more complex, automation will improve scalability and operational efficiency. Security vendors are expected to prioritize intelligent orchestration capabilities that enhance threat response while supporting compliance and governance objectives. These developments are likely to strengthen adoption across highly regulated and digitally mature industries.
Convergence of Identity, Network, and Endpoint Security
Future security architectures are expected to become increasingly unified as organizations seek simplified management and stronger protection across distributed environments. Vendors are combining identity management, network security, endpoint protection, cloud workload security, and analytics into integrated platforms. This convergence supports consistent policy enforcement and improved visibility across enterprise ecosystems. Organizations are expected to prioritize solutions capable of securing hybrid work environments and multi-cloud infrastructures through centralized administration. As interoperability becomes a key purchasing criterion, technology providers will continue developing broader security ecosystems. The resulting platform consolidation is expected to influence procurement strategies and competitive positioning throughout the forecast period.
Zero Trust Architecture Market Opportunities
Cybersecurity Modernization Across Emerging Economies
Emerging markets continue investing in digital infrastructure, cloud computing, smart city initiatives, and critical infrastructure modernization. These developments create substantial opportunities for technology providers capable of delivering scalable security solutions tailored to local regulatory and operational requirements. Governments and enterprises are increasingly recognizing the importance of identity-centric security models for protecting expanding digital ecosystems. Investments in telecommunications networks, financial technology platforms, healthcare digitization, and industrial automation are creating new implementation opportunities. The availability of cloud-delivered solutions also improves accessibility for organizations with limited cybersecurity resources. Long-term expansion across Asia Pacific, the Middle East, Africa, and parts of Latin America is expected to support sustained market development and new revenue generation opportunities.
Managed Security Services and Platform Consolidation
Organizations increasingly seek comprehensive security outcomes rather than managing multiple standalone products. This shift creates opportunities for managed service providers, systems integrators, and platform vendors capable of delivering integrated solutions. The growing complexity of cyber threats and cybersecurity skills shortages are encouraging enterprises to outsource portions of security operations. The zero trust architecture market Forecasts indicate increasing demand for subscription-based services that combine monitoring, policy management, identity governance, and threat detection capabilities. Vendors that provide simplified deployment, interoperability, and measurable security outcomes are expected to benefit from expanding customer requirements. Strategic partnerships and ecosystem development are likely to remain important competitive differentiators.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for