
Anti Neurofilament L Antibody Market Demand, Share & Growth by 2034
Coverage: By Drug Classification (Catecholamines Anorexiants, Serotonin Anorexiants); Route of Administration (Oral, Subcutaneous); End User (Hospitals, Retail Pharmacies, Online) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00008551
- Category : Life Sciences
- No. of Pages : 150
- Available Report Formats :


- Last update date : August 13, 2026


2025 Market Size
US$ 359.73 Mn
Base year value
2034 Forecast
US$ 970.48 Mn
Projected by 2034
CAGR 2026-2034
11.66 %
Growth rate
Addressable Market
US$ 5,850.21 Mn
(2026-2034)
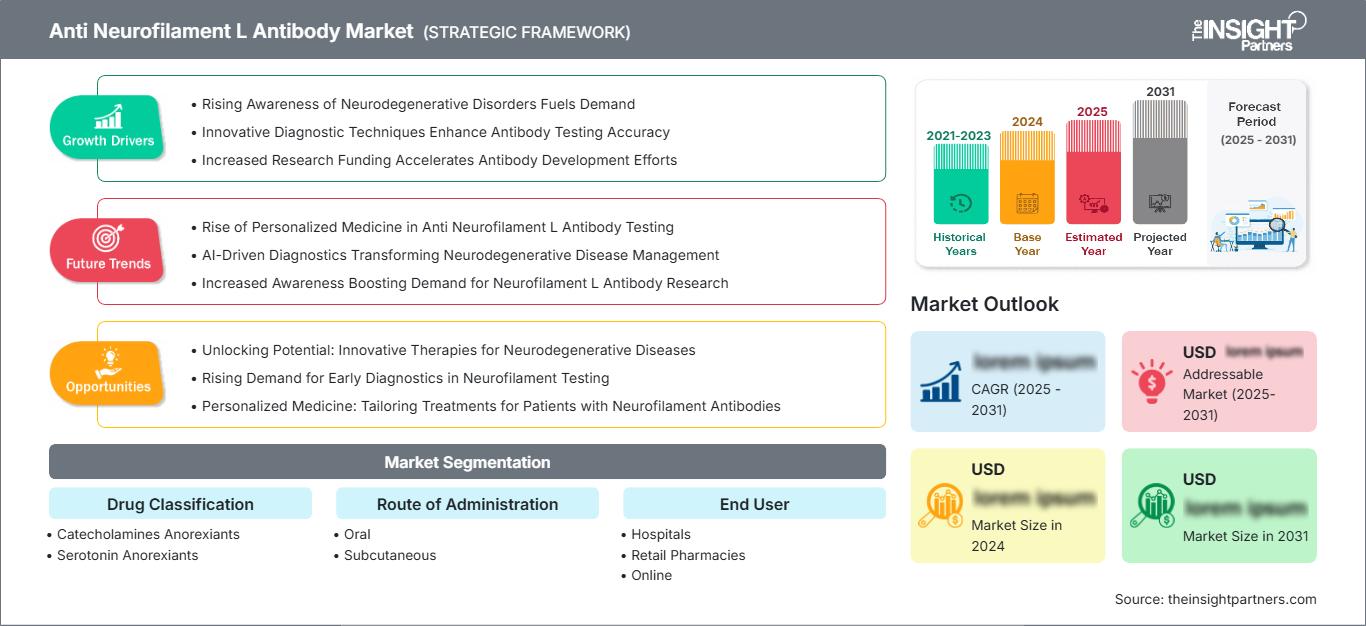
The anti neurofilament l antibody market was valued at US$ 359.73 Million in 2025 and is projected to reach US$ 970.48 Million by 2034, registering a CAGR of 11.66% during 2026–2034. Market expansion reflects rising use of neurofilament-light-chain-related assays, antibody-enabled biomarker workflows, neurological disorder research, and prescription or specialty channel models linked to neurodegeneration, metabolic neurology, and chronic therapy monitoring.
Within North America, the anti neurofilament l antibody market size is supported by academic neurology networks, biomarker validation programs, specialty pharmacies, and strong access to advanced diagnostic platforms. The region is estimated to expand at a CAGR range of 10.7–11.3% during 2026–2034, driven by multiple sclerosis monitoring, traumatic brain injury research, and broader neurodegenerative disease trial activity.
Anti Neurofilament L Antibody Market Assessment and Insights
- North America held 40–43% share in 2025 and is expected to grow at a CAGR between 2026–2034 of 10.7–11.3%, supported by neurological research funding, diagnostics infrastructure, specialty pharmacies, and biomarker adoption.
- US accounted for 82–86% of North America in 2025 and is projected to grow at a CAGR between 2026–2034 of 10.6–11.2%, led by clinical trials and specialty access.
- Europe held 27–30% share in 2025 and is expected to grow at a CAGR between 2026–2034 of 10.1–10.7%, with Germany, the UK, France, Italy, and Spain leading adoption.
- Asia Pacific represented 21–24% share in 2025 and is expected to grow at a CAGR between 2026–2034 of 12.6–13.2%, led by China, Japan, South Korea, India, and Australia.
- Largest Segment Drug Classification held 58–62% market share in 2025 and is expected to grow at a CAGR range of 11.2–11.8% during 2026–2034, supported by prescription categorization.
- High Growth Segment Online recorded 9–12% market share in 2025 and is projected to grow at a CAGR range of 14.0–14.6% during 2026–2034 as digital dispensing expands.
- Key companies analyzed in detail: Akrimax Pharmaceuticals, LLC, Teva Pharmaceutical Industries Ltd., F. Hoffmann-La Roche Ltd, Arena Pharmaceuticals GmbH, Novo Nordisk A/S, Abbott Laboratories, Epic Pharma, LLC, Patheon Pharmaceuticals Inc., Recordati Rare Diseases Inc., MOVA Pharmaceutical Corporation.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The development of clinical and business processes has shifted from individualized antibody procurement to more advanced techniques including biomarker-based workflow, companion tools for research, and monitoring in treatment. The anti neurofilament l antibody industry is influenced by the reproducibility of assays, specificity of antibodies, subcutaneous and oral drug delivery, pharmacy route, and contract manufacturing facility availability. The production process becomes characterized by batch validation, scalability and sterility of production, cold chain management, and improved quality documentation in hospitals and drugstores.
During the forecast period, growth will be driven by developing neurology clinics, the increasing usage of blood markers, and acceptance of measurable disease activity endpoints. WHO states that neurological diseases contribute to disability in a large extent and gaps in treatments are still high in low-income countries.
Anti Neurofilament L Antibody Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 359.73 Million |
| Market Size by 2034 | US$ 970.48 Million |
| Global CAGR (2026 - 2034) | 11.66% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Anti Neurofilament L Antibody Market Analysis
The need for anti neurofilament l antibodies in neurology clinics, metabolic centers, and research labs will drive the growth of the anti neurofilament l antibody market. Purchasers need validated antibody inputs, efficient medicine delivery and treatment methods that allow for correlating biological activity with patient monitoring. This ecosystem comprises diagnostic firms, manufacturing firms, raw material suppliers, hospitals, retail pharmacies, web-based sales platforms, laboratory centers, neurologists, endocrinologists, and reimbursement organizations.
The supply chain is still contingent upon consistency, documentation, formulation and logistics of oral and/or subcutaneous treatments. Hospitals usually lead the complicated process of treatment or testing, whereas retail pharmacies assist with recurring deliveries. Web-based sales are now coming into play where prescription renewal can become more accessible.
Anti neurofilament l antibody market analysis reveals a heterogeneous competitive base that includes major pharmaceutical companies, specialty manufacturers, diagnostic companies, and contract development organizations. F. Hoffmann-La Roche Ltd. and Abbott Laboratories increase the diagnostic and biomarkers angle, while Novo Nordisk A/S and Arena Pharmaceuticals GmbH highlight the metabolic and chronic therapies angle.
Competitive positioning varies according to capabilities. Teva Pharmaceutical Industries Ltd., Epic Pharma, LLC, and Akrimax Pharmaceuticals, LLC provide expertise in generics or specialty distribution, while Patheon Pharmaceuticals Inc. offers manufacturing capability. Recordati Rare Diseases Inc. and MOVA Pharmaceutical Corporation contribute experience in niche markets, thus resulting in competitive dynamics determined by accessibility, validation, and supply assurance.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Anti Neurofilament L Antibody Market: Strategic Insights
Regional Insights
North America anti neurofilament l antibody market
North America held 40–43% share in 2025 and is projected to grow at a CAGR range of 10.7–11.3% during 2026–2034. The anti neurofilament l antibody market share is supported by advanced neurological testing, central laboratory capacity, academic clinical research, specialty pharmacy access, and higher adoption of biomarker-based monitoring in multiple sclerosis and neurodegenerative studies.
The US provides most regional demand, while Canada adds structured hospital and university research participation. Roche’s 2026 CE-marked Elecsys NfL test reflects broader validation of neurofilament light chain as a clinically meaningful blood biomarker in relapsing-remitting multiple sclerosis, complementing MRI and clinical assessment.
U.S. anti neurofilament l antibody Market
The U.S. accounted for 82–86% of North America in 2025 and is forecast to grow at a CAGR range of 10.6–11.2% during 2026–2034. Demand is concentrated in academic hospitals, neurology practices, obesity and metabolic clinics, specialty pharmacies, and research institutes using biomarker-driven endpoints for disease monitoring.
Company presence is reinforced by Abbott Laboratories, F. Hoffmann-La Roche Ltd, Novo Nordisk A/S, Teva Pharmaceutical Industries Ltd., and Patheon Pharmaceuticals Inc. Application trends include laboratory validation of neurofilament light chain, chronic prescription refill management, online channel use, and clinical trial workflows that require consistent antibody and drug supply.
Europe anti neurofilament l antibody Market
The market shares of Europe in 2025 stood at 27–30%, with expected growth in the coming period from 2026–2034 with a CAGR rate of 10.1-10.7%. Germany has been leading adoption through university hospitals, diagnostic facilities and research in neurological disorders. The UK has contributed with NHS guidelines, biomarkers in academia and regulated medicine availability.
France, Italy, and Spain have been contributing through specialty hospitals, retail pharmacies and increasing interest in blood based monitoring. Development in the markets have been driven by CE marked diagnostics, reimbursement considerations, clinical evidence requirements and European emphasis on early detection of neurological diseases.
APAC anti neurofilament l antibody Market
The market share of APAC was 21–24% in 2025 and is forecasted to register a CAGR in the range of 12.6–13.2% over 2026–2034. China drives the regional market due to its hospital modernization, domestic biologicals, and clinical trials activities. Advanced diagnostics drive Japan and South Korea, and specialty pharmacy and trials drive India and Australia.
Drivers in the industry comprise of contract manufacturing, development of bioscience parks, and penetration of digital pharmacies. Chronic diseases, healthy aging, and domestic diagnostics policy focus improve adoption, but affordability and availability of specialists outside metropolitan areas vary.
Middle East & Africa anti neurofilament l antibody Market
The Middle East & Africa market is expected to have a CAGR between 10.9–11.5% for the years 2026–2034. The leading adopter region is Saudi Arabia, which uses its tertiary hospitals, investments in specialty pharmacies, and neurological care services to dominate this segment.
South Africa continues to be the main provider from the sub-Saharan region, with demand originating from hospitals and pharmacies. Growth in the rest of the MEA will depend on infrastructure, neurologists, and medicines, although investments from both public and private sectors have been improving the situation.
Segmentation Analysis
Drug Classification
The Drug Classification segment is projected to grow at a CAGR range of 11.2–11.8% during 2026–2034. The anti neurofilament l antibody market scope by drug classification is shaped by therapeutic positioning, physician prescribing preference, safety monitoring, and the ability to connect metabolic or neurological risk signals with long-term therapy management. Commercial demand reflects both established prescription frameworks and evolving biomarker-linked decision support.
- Catecholamines Anorexiants retain relevance in tightly managed prescribing environments where appetite-related mechanisms, patient selection, cardiovascular risk evaluation, and controlled dispensing shape physician confidence and pharmacy oversight.
- Serotonin Anorexiants support demand where serotonergic pathways are considered within monitored treatment plans, with strategic importance tied to safety history, labeling clarity, and patient adherence.
Route of Administration
The Route of Administration segment is projected to grow at a CAGR range of 11.7–12.3% during 2026–2034. Oral products benefit from convenience and retail fulfillment, while subcutaneous options support differentiated dosing, specialist initiation, and stronger adherence in selected chronic-care pathways. Route selection is increasingly influenced by safety monitoring, tolerability, training requirements, patient preference, and payer controls.
- Oral administration remains commercially important because it aligns with routine pharmacy dispensing, lower administration complexity, and patient familiarity in chronic treatment management.
- Subcutaneous delivery is gaining attention where longer dosing intervals, specialist supervision, and biologic-style patient training can improve persistence and differentiate premium therapies.
End User
The End User segment is projected to grow at a CAGR range of 12.1–12.7% during 2026–2034. Hospitals lead initiation for complex patients and specialist programs, while retail pharmacies sustain recurring access. Online channels are growing fastest because digital refill pathways, telehealth links, and home delivery improve convenience for patients whose therapy or monitoring schedule is long term.
- Hospitals support specialist diagnosis, biomarker testing coordination, subcutaneous initiation, adverse-event management, and procurement of validated products used within structured care pathways.
- Retail Pharmacies remain central to repeat dispensing, patient counseling, prescription substitution management, inventory continuity, and access to oral therapies across community settings.
- Online channels are scaling where regulations permit e-prescriptions, home delivery, refill reminders, and direct-to-patient models for eligible chronic therapies.
Opportunity Snapshot
| Segment Name | Revenue Contribution | Trend Tag | Adoption Stage |
|---|---|---|---|
| Hospitals | High | Specialist Initiation | Mature |
| Retail Pharmacies | High | Refill Access | Mature |
| Online | Medium | Digital Fulfillment | Scaling |
Anti Neurofilament L Antibody Market Growth Drivers and Impact Analysis
Rising adoption of neurofilament light chain monitoring
Neurofilament light chain is gaining clinical value as a biomarker of neuroaxonal injury, particularly in multiple sclerosis, traumatic brain injury, Alzheimer’s disease research, and other neurological disorders. Roche’s Elecsys NfL CE mark in 2026 supports broader acceptance of blood-based monitoring in relapsing-remitting multiple sclerosis, where routine MRI access can be constrained. This driver increases demand for validated antibodies, analytical platforms, and associated treatment workflows. The commercial impact is stronger laboratory procurement, more biomarker-linked trials, and better alignment between diagnostics, therapy selection, and disease activity monitoring. Companies with robust validation packages gain credibility in hospital and research accounts.
Growth in chronic metabolic and neurological therapy needs
The segmentation profile links monitored therapies with oral and subcutaneous administration, reflecting the convergence of chronic disease management, specialty dispensing, and biomarker-informed patient oversight. Obesity, metabolic dysfunction, neuroinflammation, and neurodegenerative risk increasingly overlap in clinical research and real-world care pathways. Novo Nordisk’s 2026 high-dose semaglutide developments illustrate how subcutaneous chronic therapies are expanding in weight-related indications, which influences distribution expectations and payer review practices. For the anti neurofilament l antibody market, the impact is greater need for evidence-based patient selection, safety monitoring, refill persistence, and channel coordination across hospitals, retail pharmacies, and online access models.
Expansion of digitally supported prescription channels
Online distribution is moving from convenience retailing to structured chronic therapy support through e-prescriptions, refill reminders, home delivery, and telehealth-linked eligibility checks. This matters for long-term therapies where missed prescriptions can disrupt outcomes and increase follow-up burden. Digital channels are especially relevant for oral treatments and maintenance regimens after physician initiation. The market impact includes broader geographic reach, higher refill persistence, and better data capture for adherence. However, growth depends on regulatory control, patient authentication, pharmacy counseling, and clear escalation pathways for adverse events or treatment changes, especially when products require specialist oversight.
Anti Neurofilament L Antibody Market Future Trends
Blood-based biomarker integration in routine neurology
Blood-based monitoring is expected to be one of the most important anti neurofilament l antibody market trends as hospitals and laboratories seek scalable alternatives that complement MRI, cerebrospinal fluid testing, and clinical examination. Standardized assays for neurofilament light chain can support earlier reassessment, track biological disease activity, and improve trial endpoint design. Future adoption will depend on reference ranges, reimbursement acceptance, and workflow integration with neurology visits. Companies that provide validated antibodies, automated assay compatibility, and clinician education will be positioned to benefit as biomarker use shifts from specialist research into routine monitoring.
Convergence of specialty pharmacy and biomarker evidence
Specialty pharmacy models will increasingly incorporate diagnostic documentation, treatment eligibility, adherence tracking, and outcomes reporting. This trend is likely to strengthen as subcutaneous therapies, chronic metabolic treatments, and neurologically monitored products require payer evidence beyond prescription volume. Pharmacies may become important data partners by linking dispensing patterns with laboratory markers and clinical follow-up. The largest commercial benefit will arise where pharmacy networks help reduce therapy discontinuation, manage prior authorization, and support real-world evidence packages that manufacturers need for formulary negotiations and lifecycle management.
Anti Neurofilament L Antibody Market Opportunities
Validated antibody supply for clinical laboratories
Manufacturers can invest in high-specificity antibody production, reference-standard documentation, and compatibility testing for automated laboratory platforms. anti neurofilament l antibody market Forecasts indicate that demand will rise as neurofilament light chain becomes more common in multiple sclerosis monitoring, drug development, and neurodegenerative research. Opportunity areas include lot-to-lot reproducibility, scalable manufacturing, laboratory training, and partnerships with diagnostic platform providers. Companies that reduce validation burden for hospitals and research institutes can command stronger procurement preference. This opportunity is particularly attractive where clinical laboratories need dependable inputs for regulated or near-regulated biomarker workflows.
Channel partnerships for chronic specialty access
Pharmaceutical firms, contract manufacturers, and pharmacy networks can build integrated access programs that combine physician initiation, refill continuity, patient education, and online reordering where regulations allow. The opportunity is strongest for oral and subcutaneous therapies requiring long-term adherence, safety monitoring, or dose escalation. Partnerships can reduce treatment interruption, support payer documentation, and improve geographic reach beyond major hospitals. Commercial gains will depend on credible governance, secure data exchange, and pharmacist involvement in counseling. Firms that coordinate hospitals, retail networks, and online platforms can improve patient continuity while preserving clinical oversight.
Recent Developments
- April 2026: F. Hoffmann-La Roche Ltd received CE mark approval for the Elecsys Neurofilament Light Chain blood test to detect neuroinflammation in adults with relapsing-remitting multiple sclerosis, enabling a minimally invasive option that complements MRI and clinical assessment while expanding standardized biomarker monitoring on cobas systems.
- March 2026: Novo Nordisk A/S received U.S. FDA approval for Wegovy HD, a 7.2 mg higher-dose semaglutide injection for adults with obesity or overweight with at least one weight-related condition, after review under the Commissioner’s National Priority Voucher pilot program.
- February 2024: Abbott Laboratories and Fujirebio announced a partnership to develop a research-use-only neurofilament-light-chain neurology biomarker assay for Abbott’s Alinity i system, targeting availability by 2025 and supporting research across multiple sclerosis, Alzheimer’s disease, traumatic brain injury, and cognitive impairment.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for