
Automotive Engine Valves Market Demand, Trends & Forecast by 2034
Coverage: By Technology (Spring Return Valve, Tappet Valve, Dismodromic Valve, Quattrovalvole Valve); Fuel Type (Gasoline, Diesel); End User (Commercial Vehicle, Passenger Vehicle, Electric Vehicle,) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00005239
- Category : Automotive and Transportation
- No. of Pages : 150
- Available Report Formats :


- Last update date : August 13, 2026


2025 Market Size
US$ 6.15 Bn
Base year value
2034 Forecast
US$ 8.62 Bn
Projected by 2034
CAGR 2026-2034
3.81 %
Growth rate
Addressable Market
US$ 67.04 Bn
(2026-2034)
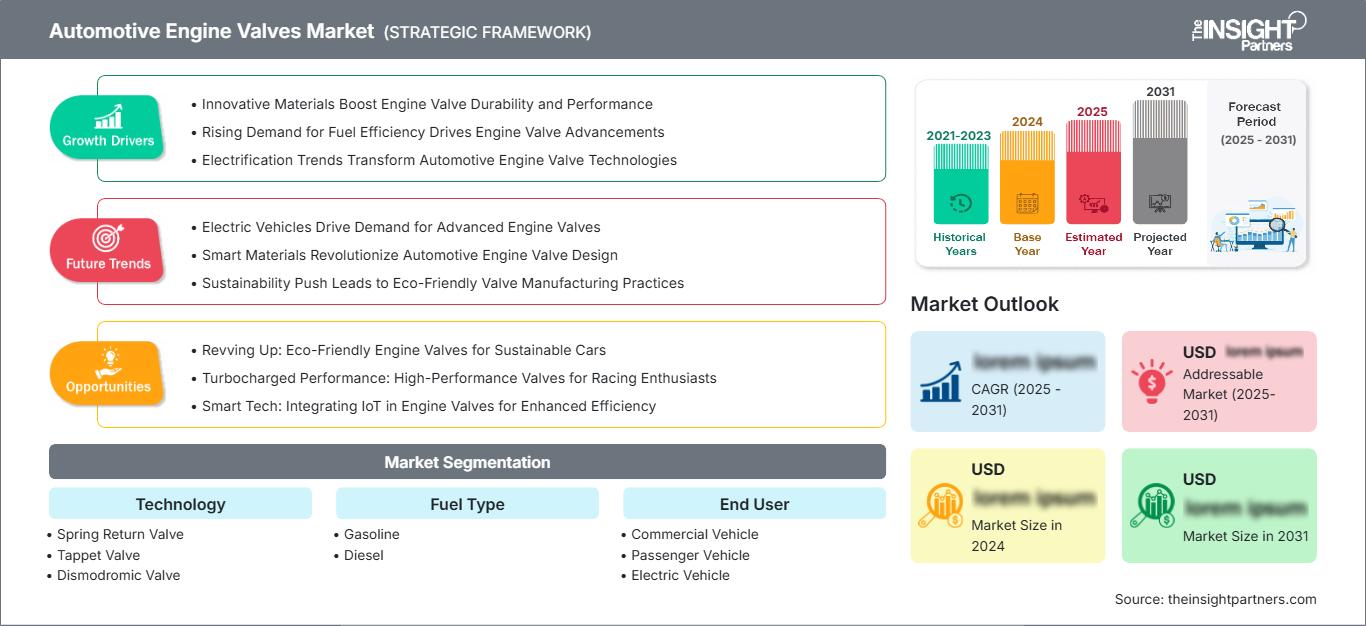
The automotive engine valves market was valued at US$ 6.15 Billion in 2025 and is projected to reach US$ 8.62 Billion by 2034, registering a CAGR of 3.81% during 2026–2034. Automotive engine valves remain indispensable components for regulating air-fuel intake and exhaust gas discharge within internal combustion engines. Ongoing improvements in valve metallurgy, lightweight designs, and precision manufacturing continue to support engine durability, combustion efficiency, and compliance with increasingly stringent emission regulations across global automotive production.
Driven by continued production of gasoline, diesel, and hybrid vehicles, the automotive engine valves market size in North America is expected to expand at a CAGR of 3.3–3.9% through 2034. Regional demand is supported by advanced engine manufacturing capabilities, increasing investments in fuel-efficient powertrains, and sustained replacement demand from commercial fleets and passenger vehicle aftermarket applications.
Automotive Engine Valves Market Assessment and Insights
- North America: Accounted for 28–32% share in 2025 and is projected to expand at a CAGR of 3.3–3.9% during 2026–2034. Stable automotive production, advanced engine manufacturing, and continuous investments in efficient combustion technologies continue to support regional demand for high-performance engine valves.
- U.S.: Represented 75–79% of the North American market in 2025 and is anticipated to register a CAGR of 3.4–4.0% through 2034. Strong OEM production, extensive commercial vehicle manufacturing, and advanced engine development activities sustain long-term market demand.
- Europe: Held 25–29% market share in 2025 while growing at a CAGR of 3.5–4.1%. Germany leads regional demand, followed by the United Kingdom, France, Italy, and Spain due to their established automotive manufacturing ecosystems and premium vehicle production.
- Asia Pacific: Captured 36–40% market share in 2025 and is forecast to register the highest CAGR of 4.3–4.9% during 2026–2034. China, Japan, India, and South Korea continue expanding engine component manufacturing through increasing automotive production and localization initiatives.
- Largest Segment: Spring Return Valve accounted for 48–52% market share in 2025 and is expected to expand at a CAGR of 3.5–4.1%, supported by widespread adoption across conventional passenger and commercial vehicle engines.
- High Growth Segment: Passenger Vehicle represented 63–67% market share in 2025 and is projected to register a CAGR of 4.2–4.8%, driven by sustained passenger vehicle production and continued improvements in fuel-efficient engine technologies.
- Key companies analyzed in detail: Aisin Corporation, BorgWarner Inc., Continental AG, Cummins Inc., Aptiv PLC, DENSO Corporation, Hitachi Astemo, Johnson Electric Holdings Limited, Robert Bosch GmbH, Schaeffler AG.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The automotive engine valves market continues evolving through advances in metallurgy, precision forging, laser hardening, and lightweight material engineering. Engine manufacturers have begun to concentrate on providing better thermal resistance, wear characteristics, and dimensional accuracy as a means of coping with the greater combustion temperatures that have become characteristic of new downsized and turbo engines. Advanced automation and digital inspection technologies have enabled improvements in manufacturing uniformity and a reduction in defect rates in large automotive component factories.
In future years, innovations in local manufacturing of engine components, sustainable production systems, and advanced combustion technologies may define industrial competition. Hybrid vehicle manufacturing, automotive production in the Asia Pacific region, and fleet upgrades will sustain growth in engine valve demand in the long term.
Automotive Engine Valves Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 6.15 Billion |
| Market Size by 2034 | US$ 8.62 Billion |
| Global CAGR (2026 - 2034) | 3.81% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Automotive Engine Valves Market Analysis
Increasing production of fuel-efficient internal combustion and hybrid vehicles continues driving the automotive engine valves market growth worldwide. Modern engines require highly durable intake and exhaust valves capable of operating under elevated temperatures and pressures while maintaining efficient combustion performance. Technological developments in turbocharging, direct fuel injection, and variable valve timing systems raise the need for high-precision valves produced from heat-resistant alloys using advanced surface treatments. The improvements in the automation of production processes, materials science, and precision machining add to the development of the products’ quality and reliability.
The industry value chain involves alloy producers, forging companies, machinery, coatings firms, valve makers, Tier-1 suppliers, OEMs, and the aftermarket industry. Localization of car production, automated quality control, and production process automation increase supply chain efficiency and cut down the costs of manufacturing. A good cooperation between engine producers and valve suppliers is an important driver of innovations in the field of advanced valves.
According to a comprehensive analysis of the market of automotive engine valves, competition differentiation is becoming reliant upon innovations in materials used in manufacturing valves, precise manufacturing processes and expertise in engineering and thermal durability. Investments in the production of lightweight valves and friction-reducing coatings, along with the introduction of digital manufacturing solutions, are made by manufacturers in order to increase the efficiency of engines while complying with new emission standards.
Leading players in the market, such as Robert Bosch GmbH, DENSO Corporation, Schaeffler AG, Aisin Corporation, BorgWarner Inc., Continental AG, Cummins Inc., Hitachi Astemo, Johnson Electric Holdings Limited, and Aptiv PLC, are further improving their positions in the market via modernization of production process, innovations, acquisitions and increasing production globally.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Automotive Engine Valves Market: Strategic Insights
Regional Insights
North America Automotive Engine Valves Market
North America accounted for 28–32% of the automotive engine valves market share in 2025 and is projected to expand at a CAGR of 3.3–3.9% during 2026–2034. There is the presence of a well-developed ecosystem of car manufacturing plants, a strong presence of commercial vehicles and investment in high-performance internal combustion and hybrid engines. Requirements of advanced valves will be sustained by the emission norms, engine downsizing and use of variable valve timing technology in passenger cars, pickup trucks and commercial vehicles.
Continued efforts in the form of investments made by manufacturers in automation of forging process, machining and laser surface hardening and digital inspection technology to increase the durability of valves and manufacturing will be sustained. The growing production of hybrid engines will sustain the demand for high-temperature resistant valves offering higher combustion efficiency and longevity.
U.S. Automotive Engine Valves Market
The U.S. represented 75–79% of the North American market in 2025 and is anticipated to register a CAGR of 3.4–4.0% throughout the forecast period. It is the home to one of the largest automotives industry that boasts of the participation of several OEMs, engine building plants, and highly developed networks of suppliers who are specialists in engine valve manufacturing. The increasing demand for trucks, SUVs, and commercial vehicles ensures the sustained demand for high-quality engine valves.
Domestic engine valve makers improve their manufacturing processes with automation, robotic milling and metallurgical treatment. Increasing involvement in the production of hybrid cars and growing demand for replacing engines in an already large vehicle parc ensure the sustainable market growth. Leading suppliers of engine valve parts from around the globe help advance valve technologies.
Europe Automotive Engine Valves Market
Europe held 25–29% market share in 2025 and is projected to register a CAGR of 3.5–4.1% through 2034. Germany remains the largest regional market because of its globally recognized automotive industry, premium vehicle manufacturing, and advanced engine engineering capabilities. Strong emphasis on fuel efficiency, lower emissions, and precision manufacturing continues to support the adoption of technologically advanced engine valve systems.
The United Kingdom maintains demand through premium vehicle manufacturing, motorsport engineering, and specialized engine development programs. Germany continues to lead regional production through extensive OEM investments in advanced combustion technologies and hybrid powertrains. France, Italy, and Spain collectively contribute significant manufacturing capacity supported by established automotive clusters, advanced machining expertise, and continuous investments in efficient engine technologies, strengthening regional demand for precision engine valve components.
APAC Automotive Engine Valves Market
Asia Pacific accounted for 36–40% market share in 2025 and is expected to record the highest CAGR of 4.3–4.9% during the forecast period. China leads regional production, while Japan, India, South Korea, and Australia continue strengthening automotive manufacturing through industrial modernization, localization initiatives, and expanding engine component production capacity.
Rapid vehicle production, supportive industrial policies, growing domestic demand, and increasing exports continue to strengthen regional manufacturing competitiveness. China remains the largest production hub, while India demonstrates significant growth potential through expanding passenger vehicle manufacturing and increasing investment in automotive component production.
Middle East & Africa Automotive Engine Valves Market
The Middle East & Africa market is forecast to expand at a CAGR of 3.1–3.7% during 2026–2034. Saudi Arabia continues promoting industrial diversification and automotive manufacturing, while the United Arab Emirates supports demand through premium vehicle imports and aftermarket activities. South Africa remains the leading regional automotive production center.
Infrastructure development, localization initiatives, and increasing commercial transportation activities continue to support the gradual adoption of advanced engine components across the region. Although production volumes remain comparatively smaller than major automotive markets, ongoing industrial investments and fleet modernization programs are expected to provide steady long-term growth opportunities.
Segmentation Analysis
Technology
The Technology segment is projected to expand at a CAGR of 3.6–4.2% during the forecast period. The automotive engine valves market scope continues evolving as manufacturers develop advanced valve mechanisms capable of improving combustion efficiency, engine responsiveness, and emission performance. Continuous innovation in valve actuation technologies, lightweight alloys, and precision engineering is strengthening adoption across modern gasoline, diesel, and hybrid engines.
- Spring Return Valve remains the dominant technology because of its proven reliability, simple mechanical architecture, cost efficiency, and extensive use across passenger cars, commercial vehicles, and heavy-duty engine platforms.
- Tappet Valve supports precise valve operation in modern engines by improving timing accuracy, reducing mechanical wear, and enabling stable performance under demanding operating conditions.
- Dismodromic Valve is primarily utilized in high-performance engines where mechanically controlled valve operation enables higher engine speeds, improved responsiveness, and enhanced combustion efficiency without conventional valve springs.
- Quattrovalvole Valve improves engine breathing through multiple intake and exhaust valves per cylinder, enhancing combustion efficiency, fuel economy, and overall engine performance across advanced automotive applications.
Fuel Type
The Fuel Type segment is expected to register a CAGR of 3.4–4.0% between 2026 and 2034. Continued production of internal combustion and hybrid vehicles supports steady demand for advanced valve technologies designed to withstand higher combustion temperatures while improving engine efficiency and durability.
- Gasoline engines account for the largest share owing to their widespread use in passenger vehicles, ongoing hybrid powertrain production, and continuous improvements in combustion efficiency through advanced valve technologies.
- Diesel engines maintain stable demand across commercial vehicles, construction equipment, and heavy-duty transportation, where durability, high torque output, and fuel efficiency remain critical operational requirements.
End User
The End User segment is projected to grow at a CAGR of 3.8–4.4% throughout the forecast period. Vehicle production trends, emission regulations, and ongoing engine efficiency improvements continue influencing the adoption of advanced valve technologies across different vehicle categories.
- Commercial Vehicle applications require durable engine valves capable of sustaining prolonged operation under heavy loads while ensuring reliability and fuel efficiency.
- Passenger Vehicle represents the largest demand segment because of high global production volumes, increasing hybrid vehicle manufacturing, and continuous adoption of advanced combustion technologies.
- Electric Vehicle demand remains comparatively limited because battery electric vehicles do not utilize conventional internal combustion engine valve systems. However, hybrid electric vehicles continue to support demand for advanced engine valve technologies.
Opportunity Snapshot
| End User | Revenue Contribution | Trend Tag | Adoption Stage |
|---|---|---|---|
| Commercial Vehicle | Medium | Fleet Efficiency | Mature |
| Passenger Vehicle | High | Hybrid Engines | Mature |
| Electric Vehicle | Low | Hybrid Transition | Emerging |
Automotive Engine Valves Market Growth Drivers and Impact Analysis
Stringent emission regulations driving advanced valve technologies
Emission standards being introduced in North America, Europe, and the Asia Pacific region by governments have continued to become more stringent, necessitating improved combustion efficiency and reduced greenhouse gas emissions from automobiles. Engine valves that have been developed through the use of heat-resistant metals, nitriding process, and machining provide for efficient airflow, reduced combustion losses, and increased thermal efficiency. They also offer a solution to variable valve timing, which improves engine performance and reduces fuel consumption. With ongoing developments in internal combustion and hybrid engines in line with environmental regulations, the demand for efficient valves is likely to be steady throughout the forecast period.
Growing hybrid vehicle production supporting sustained component demand
Though battery electric vehicles do away with the need for any components of the traditional engine, hybrid electric vehicles continue to employ complex internal combustion engines with intricate intake and exhaust valves. The global automobile manufacturers have been increasing their line-ups of hybrid vehicles by blending their aims of cutting emissions with the customer’s preference for high mileage and existing fueling system. Hybrid engines often function in different thermal environments, and thus, there is a need for valves with better resistance against wear and stable dimensions. Thus, the valve component makers keep on making investments in the field of advanced metallurgy, lightweight valves, and manufacturing technology.
Precision manufacturing and advanced metallurgy improving durability
Advancements made in forging technology, CNC machining, laser hardening of the surface layer, and quality inspection systems have brought about a considerable improvement in the performance of valves and their manufacturing process. Modern cars' valves must be able to function well at higher temperatures produced through combustion without any deformation or fatigue. Alloy steels and surface coating, along with the heat treatment process, ensure protection against corrosion, oxidation, and wear. Such manufacturing methods decrease the number of warranty claims, increase the engine's reliability, and allow manufacturers to produce more complicated valves.
Automotive Engine Valves Market Future Trends
Expansion of intelligent manufacturing across engine component production
Manufacturers are increasingly integrating digital manufacturing technologies, robotics, machine vision inspection, predictive maintenance, and artificial intelligence into valve production facilities. These automotive engine valve market trends enable improved dimensional accuracy, lower production waste, enhanced process consistency, and faster product development cycles. Smart factories also strengthen traceability and quality assurance while reducing operating costs. As automotive OEMs continue emphasizing manufacturing efficiency and supply chain resilience, digitally connected production environments are expected to become a defining competitive advantage for leading valve manufacturers.
Increasing adoption of lightweight high-performance valve materials
Innovations in materials are anticipated to become more common as producers aim for increased engine efficiency and reduced vehicle emissions. New titanium alloys, advanced stainless steels, innovative surface treatments, and improvements in heat treatments are continuously increasing the durability of the components while making them lighter. Lighter valve assemblies help to increase the performance of the engine by improving fuel efficiency. These innovations are likely to contribute to future hybrid and high-performance internal combustion engines.
Automotive Engine Valves Market Opportunities
Expanding manufacturing investments across emerging automotive economies
Increasing automotive production across India, Southeast Asia, Mexico, and selected Middle Eastern countries presents attractive long-term investment opportunities for component manufacturers. Automotive engine valves market Forecasts indicate that localized production, government-supported industrial development, and expanding domestic vehicle demand will encourage suppliers to establish regional forging, machining, and assembly facilities. Local manufacturing improves supply chain resilience while reducing logistics costs and delivery times. Companies capable of developing strategic partnerships with regional OEMs and Tier-1 suppliers are expected to strengthen competitive positioning while expanding access to high-growth automotive production hubs.
Advanced hybrid powertrain technologies creating new product opportunities
Hybrid vehicle production is expected to remain a significant growth avenue for engine valve manufacturers despite increasing electrification. Hybrid engines require durable valve systems capable of frequent start-stop operation, higher thermal cycling, and improved combustion efficiency. Suppliers investing in lightweight materials, precision manufacturing, and advanced surface engineering will be well-positioned to support evolving OEM requirements. Strategic collaboration with powertrain developers, continued research into advanced alloys, and expanded production capabilities are expected to create sustainable long-term revenue opportunities across global automotive markets.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for