
Cloud Workload Protection Platform (CWPP) Market Trends, Demand & Growth by 2034
Coverage: By Cloud Type (Public Cloud, Private Cloud, And Hybrid Cloud); Application (Workload Configuration and Vulnerability Management, Network Segmentation, System Integrity Measurement, Digital Asset Management [DAM], Denial-of-Service Attack [DoS], Others); Enterprise Size (SMEs, Large Enterprises); Industry (BFSI, IT and Telecom, Healthcare, Retail, Government, Education, Manufacturing, Others) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00028603
- Category : Technology, Media and Telecommunications
- No. of Pages : 150
- Available Report Formats :


- Last update date : August 06, 2026


2025 Market Size
US$ 8.86 Bn
Base year value
2034 Forecast
US$ 58.72 Bn
Projected by 2034
CAGR 2026-2034
23.38 %
Growth rate
Addressable Market
US$ 263.01 Bn
(2026-2034)
The Cloud workload protection platform market was valued at US$ 8.86 Billion in 2025 and is projected to reach US$ 58.72 Billion by 2034, expanding at a CAGR of 23.38% during 2026–2034. The increasing migration of enterprise workloads to multi-cloud environments, rising cybersecurity threats, and growing adoption of cloud-native applications are accelerating the deployment of cloud workload protection platforms. Organizations across regulated industries continue investing in unified workload security solutions to strengthen visibility, compliance, and operational resilience.
Across North America, digital transformation initiatives, widespread cloud adoption, and increasing cybersecurity investments continue to reinforce long-term demand for workload security technologies. The cloud workload protection platform market size is expected to expand steadily across the region with an estimated CAGR of 22.2–23.1% during 2026–2034. Growing implementation of zero-trust security frameworks, containerized applications, and hybrid cloud infrastructure remains a primary driver supporting sustained technology adoption among enterprises of all sizes.
Cloud Workload Protection Platform (CWPP) Market Assessment and Insights
- North America: The region maintains leadership owing to mature cloud infrastructure, strong cybersecurity spending, and extensive enterprise cloud migration. Share in 2025: 39–43% and anticipated to grow at a CAGR between 22.2–23.1% during 2026–2034.
- US: The country represents the largest national market due to significant cloud investments and the presence of major cybersecurity vendors. Share in 2025: 83–87% of North America and projected to expand at a CAGR between 22.3–23.2% during 2026–2034.
- Europe: Strong data protection regulations and increasing enterprise cloud modernization continue driving adoption across Germany, the UK, and France. Share in 2025: 24–28% and expected to register a CAGR between 21.5–22.4% during 2026–2034.
- Asia Pacific: Rapid cloud infrastructure expansion, digital economy initiatives, and cybersecurity investments across China, Japan, India, and South Korea continue supporting regional growth. Share in 2025: 23–27% with a CAGR between 25.2–26.3% during 2026–2034.
- Largest Segment: Public Cloud dominates due to widespread enterprise cloud migration, scalability, and continuous deployment of cloud-native workloads. Market share in 2025: 46–50% and expected to grow at a CAGR between 23.6–24.5% during 2026–2034.
- High Growth Segment: Hybrid Cloud is anticipated to witness the fastest expansion as organizations increasingly adopt multi-environment security strategies. Market share in 2025: 27–31% and forecast to expand at a CAGR between 25.8–27.0% during 2026–2034.
- Key companies analyzed in detail: VMware, Inc., Musarubra US LLC, Check Point Software Technologies Ltd., Palo Alto Networks, Inc., CrowdStrike Holdings, Inc., Aqua Security Software Ltd., Rapid7, Inc., Broadcom Inc., Technosprout Pvt. Ltd., GlobalDots.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
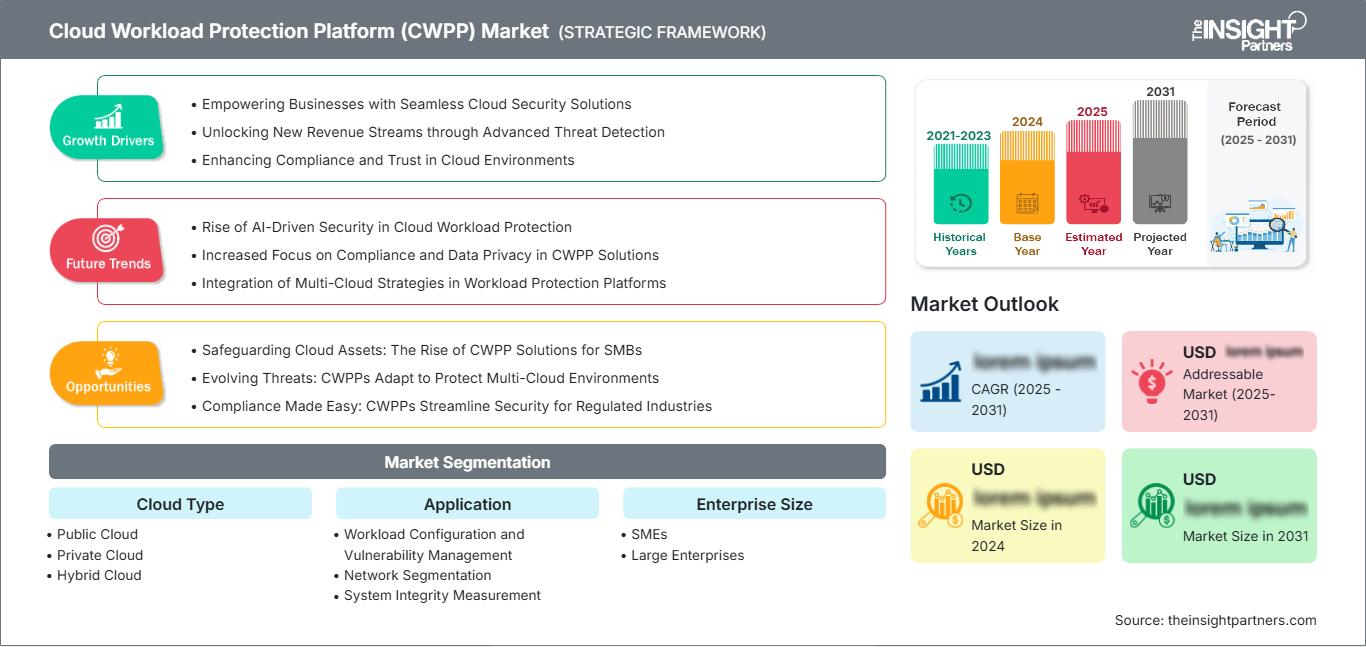
The evolution of the cloud workload protection platforms could be viewed as a consequence of rapid developments in the realm of enterprise computing, where enterprises are shifting from the on-premise infrastructure towards the cloud-native architecture. The adoption of technologies as containers, Kubernetes, serverless computing, and the DevSecOps approach is reshaping the requirements for workload security. Enterprises require integrated platforms that can ensure visibility, policy management, runtime security, vulnerability scanning, and compliance monitoring.
Future growth will be fueled by the increase in the usage of cloud services in enterprises from developing countries, increasing cybersecurity requirements, and investments in AI-powered security operations centers. Governments and companies pay much attention to cyber resilience through their cybersecurity strategies, digital infrastructure modernization, and critical infrastructure protection efforts. Increasing demand for unified cloud security platforms capable of protecting virtual machines, containers, APIs, and cloud-native applications is expected to create sustained long-term investment opportunities across multiple industry verticals, driving growth in the Cloud Workload Protection Platform Market.
Cloud Workload Protection Platform (CWPP) Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 8.86 Billion |
| Market Size by 2034 | US$ 58.72 Billion |
| Global CAGR (2026 - 2034) | 23.38% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Cloud Workload Protection Platform (CWPP) Market Analysis
The cloud workload protection platform market growth continues to accelerate as organizations migrate mission-critical applications to public, private, and hybrid cloud environments. Increasing ransomware attacks, software supply chain threats, and misconfigured cloud resources have elevated demand for unified workload security solutions capable of delivering continuous monitoring, runtime protection, vulnerability management, and compliance automation. Enterprises are prioritizing integrated platforms that secure virtual machines, containers, Kubernetes clusters, and serverless workloads while supporting zero-trust security architectures and reducing operational risk across distributed cloud ecosystems.
The expanding value chain includes cloud infrastructure providers, cybersecurity software developers, managed security service providers, system integrators, and enterprise technology partners working together to strengthen workload protection capabilities. Continuous innovation in artificial intelligence-driven threat detection, behavioral analytics, automated incident response, and policy orchestration is enabling organizations to improve their security posture while maintaining operational efficiency. Growing adoption of DevSecOps practices further supports demand for integrated workload protection throughout the software development lifecycle.
The cloud workload protection platform market analysis highlights an increasingly competitive environment where vendors differentiate through platform integration, threat intelligence, workload visibility, and cloud-native security capabilities. VMware, Inc., Palo Alto Networks, Inc., CrowdStrike Holdings, Inc., Check Point Software Technologies Ltd., and Broadcom Inc. continue expanding cloud security portfolios through innovation and strategic partnerships. Meanwhile, Aqua Security Software Ltd., Rapid7, Inc., Musarubra US LLC, Technosprout Pvt. Ltd., and GlobalDots focus on specialized workload protection, compliance management, managed security services, and cloud optimization to strengthen their market positioning.
Strategic investments continue emphasizing artificial intelligence, automation, cloud-native application protection, and unified security management across increasingly distributed enterprise environments in the Cloud Workload Protection Platform Market. Vendors are expanding strategic alliances with hyperscale cloud providers, managed service partners, and enterprise software developers to improve interoperability and customer adoption. Ongoing investment in runtime protection, vulnerability prioritization, identity security, and threat intelligence integration is expected to strengthen competitive differentiation while supporting evolving enterprise cybersecurity requirements across global cloud ecosystems.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Cloud Workload Protection Platform (CWPP) Market: Strategic Insights
Regional Insights
North America Cloud Workload Protection Platform Market
North America accounted for 39–43% of the cloud workload protection platform market share in 2025 and continues to lead the global industry due to advanced cloud infrastructure, high enterprise cybersecurity spending, and early adoption of cloud-native technologies. The region is projected to register a CAGR of 22.2–23.1% during 2026–2034, supported by increasing deployment of hybrid cloud environments, zero-trust security strategies, and stringent compliance requirements across highly regulated industries.
The presence of leading cloud service providers, cybersecurity vendors, and technology innovators creates a favorable ecosystem for continuous platform advancement. Financial institutions, healthcare organizations, government agencies, and technology enterprises continue strengthening investments in workload protection to secure containerized applications, virtual machines, and Kubernetes environments. Increasing adoption of artificial intelligence-enabled threat detection and automated security operations further supports sustained regional expansion.
U.S. Cloud Workload Protection Platform Market
The U.S. represents 83–87% of the North American market and is expected to expand at a CAGR of 22.3–23.2% during 2026–2034. Strong enterprise cloud adoption, increasing cyberattack frequency, and continuous investment in digital infrastructure position the country as the largest national market. Organizations across banking, healthcare, manufacturing, and government sectors continue modernizing cloud security architectures to strengthen resilience against evolving cyber threats.
The nation also benefits from globally known cybersecurity companies and cloud computing vendors that are constantly innovating new workload protection features. Today, businesses are adopting more and more integrated security systems that have runtime security, identity management, workload compliance, and automation of incident response. The widespread use of DevSecOps and cloud native application development is pushing further the need for workload protection solutions.
Europe Cloud Workload Protection Platform Market
Europe accounted for 24–28% of the global market in 2025 and is projected to expand at a CAGR of 21.5–22.4% during 2026–2034. Germany leads the regional market because of its strong industrial digitalization initiatives, expanding enterprise cloud adoption, and growing cybersecurity investments. The United Kingdom continues to strengthen demand through rapid financial services digitization, cloud migration strategies, and the increasing implementation of cyber resilience regulations across public and private organizations.
France, Italy, and Spain are still making their contributions to regional growth by means of national programs of digital transformation and a growing number of cloud computing solutions for enterprises. France can use the growing investment in cloud technologies and cybersecurity. The situation with the adoption of cloud solutions in Italy is getting better because of manufacturing and financial companies.
APAC Cloud Workload Protection Platform Market
Asia Pacific represented 23–27% of the global market in 2025 and is forecast to register the fastest regional expansion with a CAGR of 25.2–26.3% during 2026–2034. China remains the leading market owing to rapid cloud infrastructure development, enterprise digitalization, and increasing investment in cybersecurity technologies.
The region is still enhancing its demand via cloud-first government policies, a growing digital economy, and growing adoption of hybrid clouds. Growth in the understanding of cloud security dangers in the enterprises and growing cybersecurity framework investment are likely to drive future growth in the region.
Middle East & Africa Cloud Workload Protection Platform Market
The Middle East & Africa market is projected to expand at a CAGR of 20.0–21.0% during 2026–2034, supported by accelerating cloud adoption, digital transformation strategies, and expanding investments in cybersecurity infrastructure. Saudi Arabia leads regional demand due to increasing government investment in digital services, smart city initiatives, and national cybersecurity programs.
The United Arab Emirates and South Africa continue to strengthen enterprise cloud adoption through investments in secure digital infrastructure and regulatory modernization. Organizations across the remaining Middle East & Africa region are gradually implementing cloud security platforms to protect critical workloads, improve regulatory compliance, and support resilient digital transformation across public and private sectors.
Segmentation Analysis
Cloud Type
The Cloud Type segment defines the deployment environments secured by cloud workload protection platforms and represents one of the most significant areas within the cloud workload protection platform market scope. The segment is expected to expand at a CAGR of 23.7–24.6% during 2026–2034, driven by accelerating enterprise cloud migration, increasing adoption of cloud-native applications, and growing emphasis on unified security across distributed computing environments. Organizations continue prioritizing flexible security architectures capable of protecting workloads regardless of deployment model.
- Public Cloud: Continues to represent the largest deployment environment as enterprises increasingly migrate business-critical workloads to scalable cloud infrastructure requiring continuous monitoring, runtime protection, vulnerability assessment, and compliance management.
- Private Cloud: Remains important for organizations operating highly regulated environments where enhanced control, data sovereignty, customized security policies, and dedicated infrastructure are required to support sensitive business applications.
- Hybrid Cloud: Experiences rapid adoption because organizations increasingly operate workloads across public and private cloud environments. Unified security platforms enable centralized visibility, policy consistency, and efficient protection across complex multi-cloud infrastructures.
Application
The Application segment is projected to register a CAGR of 24.1–25.0% during 2026–2034 in the Cloud Workload Protection Platform Market, supported by growing enterprise demand for integrated cloud security capabilities addressing evolving cyber threats, regulatory compliance, and operational resilience. Organizations increasingly implement comprehensive workload protection platforms that combine multiple security functions into unified cloud-native environments, reducing complexity while improving threat detection and response.
- Workload Configuration and Vulnerability Management: Enables continuous identification of security misconfigurations, software vulnerabilities, and compliance gaps while supporting automated remediation across cloud-native workloads and virtual infrastructure.
- Network Segmentation: Strengthens workload isolation by controlling communication between cloud resources, reducing lateral movement opportunities for attackers and improving overall enterprise security posture.
- System Integrity Measurement: Provides continuous verification of workload integrity by monitoring unauthorized changes, configuration drift, and runtime anomalies that could compromise cloud environments.
- Digital Asset Management: Improves visibility into cloud assets through centralized inventory, classification, lifecycle management, and policy enforcement, enabling organizations to strengthen governance across distributed cloud infrastructure.
- Denial-of-Service Attack: Supports detection and mitigation of distributed denial-of-service attacks by monitoring workload behavior, network traffic patterns, and abnormal resource consumption to maintain service availability.
Enterprise Size
- The Enterprise Size segment is anticipated to expand at a CAGR of 22.9–23.8% during 2026–2034, as organizations of every scale continue increasing investment in cloud security technologies. Digital transformation, remote work environments, and rising cyber risks are encouraging businesses to implement workload protection platforms that enhance visibility, automate compliance, and secure distributed cloud applications.
- SMEs: Increasingly adopt cloud workload protection platforms through subscription-based deployment models that deliver enterprise-grade security, simplified implementation, and cost-effective protection for expanding cloud environments.
- Large Enterprises: Continue representing the largest customer base because of extensive hybrid cloud infrastructure, complex regulatory requirements, and significant investment in integrated cybersecurity strategies supporting multinational business operations.
Industry
The Industry segment is forecast to record a CAGR of 23.5–24.4% during 2026–2034, reflecting widespread cloud adoption across critical sectors seeking stronger workload protection, regulatory compliance, and cyber resilience. Industry-specific security requirements continue driving demand for scalable cloud-native protection platforms capable of supporting diverse operational environments.
- BFSI: Prioritizes advanced workload protection to secure financial applications, customer information, payment systems, and regulatory compliance within increasingly complex hybrid cloud infrastructures.
- IT and Telecom: Represents a major adopter because cloud-native applications, virtualization, and digital service delivery require continuous workload monitoring and runtime security.
- Healthcare: Expands implementation to protect electronic health records, connected medical systems, and research data while maintaining compliance with healthcare privacy regulations.
- Retail: Deploys workload protection to secure e-commerce platforms, digital payment infrastructure, customer databases, and omnichannel retail operations against evolving cyber threats.
- Government: Focuses on safeguarding critical public infrastructure, digital citizen services, and confidential information through comprehensive cloud workload protection strategies.
- Education: Continues increasing adoption to protect cloud-based learning platforms, research environments, and institutional information systems supporting remote education initiatives.
- Manufacturing: Implements workload protection platforms to secure industrial cloud applications, connected production systems, operational technology integration, and digital supply chain environments.
Opportunity Snapshot
| Industry | Revenue Contribution | Trend Tag | Adoption Stage |
|---|---|---|---|
| BFSI | High | Zero Trust | Mature |
| IT and Telecom | High | Cloud Native | Mature |
| Healthcare | Medium | Data Security | Scaling |
| Retail | Medium | Digital Commerce | Scaling |
| Government | Medium | Critical Infrastructure | Scaling |
| Education | Low | Secure Learning | Emerging |
| Manufacturing | Medium | Industrial Cloud | Scaling |
Cloud Workload Protection Platform (CWPP) Market Growth Drivers and Impact Analysis
Accelerating Enterprise Migration to Multi-Cloud Environments
Enterprises in various sectors are still moving their mission-critical applications to public, private, and hybrid clouds, which is resulting in a greater need for workload security. Applications that run on the cloud, including cloud-native applications, containers, Kubernetes clusters, and virtual machines, should be continually monitored to avoid any kind of compromise through unauthorized access or misconfiguration, and even from cyberattacks. Advanced protection platforms help in ensuring visibility, compliance, runtime security, and policy enforcement in dispersed environments. With the growing adoption of multi-cloud systems in enterprises, there is a growing demand for workload security solutions.
Growing Frequency of Advanced Cybersecurity Threats
Ransomware, supply chain attacks, credential theft, and cloud misconfigurations keep putting companies at risk. As enterprises adopt cloud technology, cyber attackers find cloud workloads more attractive since most of the critical business information is hosted in a distributed environment. Cloud workload protection solutions ensure the resiliency of businesses through continuous threat monitoring, behavioral analysis, vulnerability assessment, and automation of responses. Integrations with security information and event management and extended detection and response solutions provide additional insight into incidents. The increased attention that companies are paying to cyber resilience and regulation compliance keeps urging them to invest in comprehensive workload protection solutions.
Increasing Adoption of DevSecOps and Cloud-Native Development
In software development processes, security is being embedded into the entire lifecycle of application development to find out any weaknesses before moving on to deployment. The DevSecOps approach involves continuous security testing, validation of infrastructure as code, and automated compliance, and all of these processes result in an increased need for workload protection platforms. There is increased collaboration between the developers, operators, and security team members while deployment time is reduced and the risk of any security problems is mitigated. Cloud workload protection platform helps in accomplishing this process through automated scanning, runtime protection, enforcement of policies, and monitoring of configurations.
Cloud Workload Protection Platform (CWPP) Market Future Trends
Artificial Intelligence Transforming Cloud Threat Detection
Artificial intelligence is becoming a core capability for modern cloud security platforms by enabling predictive analytics, behavioral monitoring, and automated threat prioritization across complex cloud environments. The cloud workload protection platform market trends indicate growing enterprise demand for intelligent security systems capable of identifying abnormal workload behavior before incidents escalate. Machine learning models improve anomaly detection, reduce false positives, and support faster incident response. Vendors are increasingly integrating generative artificial intelligence, security copilots, and automated investigation capabilities to improve analyst productivity while strengthening enterprise cyber resilience.
Unified Cloud Security Platforms Gaining Enterprise Preference
Increasingly, organizations favor integrated security solutions that provide the ability to secure their workloads, identities, applications, APIs, and cloud infrastructure via a single management console. This approach helps organizations simplify their operations while gaining better visibility within their hybrid and multi-cloud environments. The trend is seen in vendors’ continued development of platform features such as cloud security posture management, cloud infrastructure entitlement management, workload protection, and runtime security as a part of an integrated platform. Increased demand for unified cybersecurity operations will further drive investment in cloud-native security platforms.
Cloud Workload Protection Platform (CWPP) Market Opportunities
Expanding Security Adoption Across Emerging Digital Economies
Rapid cloud adoption across Asia Pacific, Latin America, and the Middle East is creating significant opportunities for cybersecurity vendors seeking long-term expansion. Cloud workload protection platform market Forecasts suggest continued investment in cloud infrastructure, enterprise digitalization, and cybersecurity modernization across developing economies. Organizations increasingly require scalable workload protection platforms to secure expanding cloud deployments while meeting evolving regulatory requirements. Vendors establishing regional partnerships, localized support services, and cloud-native managed security offerings are expected to strengthen competitive positioning and capture growing enterprise demand in high-growth digital markets.
Industry-Specific Security Platforms for Regulated Sectors
In the case of very regulated industries such as banking, healthcare, government, and manufacturing industries, there is an increasing need for cloud security platforms that will meet the specific needs of each industry. The vendors can take advantage of developing specific platforms that cater to the needs of each industry in terms of financial regulations, healthcare protection regulations, industrial cybersecurity regulations, and governmental regulations. Such features like advanced compliance reporting, automated auditing, and threat intelligence for the specific industry can help make the product portfolio more competitive.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for