
Epoxy Curing Agents Market Demand, Trends & Forecast by 2034
Coverage: by Type (Amines, Polyamide, Imidazoles, Polymercaptan, Anhydrides, Others); Application (Adhesives, Coatings, Composites, Electronics, Others) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00005084
- Category : Chemicals and Materials
- No. of Pages : 150
- Available Report Formats :


- Last update date : September 01, 2026


2025 Market Size
US$ 6.35 Bn
Base year value
2034 Forecast
US$ 10.05 Bn
Projected by 2034
CAGR 2026-2034
5.90 %
Growth rate
Addressable Market
US$ 76.96 Bn
(2026-2034)
The Epoxy Curing Agents Market was valued at US$ 6.35 Billion in 2025 and is projected to reach US$ 10.05 Billion by 2034, registering a CAGR of 5.90% during 2026–2034. The demand growth is backed by the increased application of epoxy resins in coating formulations, adhesive applications, composites, and electronic encapsulation systems. The emphasis in the formulation is on the properties of fast curing, thermally stability, chemical resistance, low emission, processability, and adaptability to tough industrial substrates.
The North American Epoxy Curing Agents Market size is driven by the existing industries for coatings, construction, transport, aerospace, and electronics manufacturing. The projected compound annual growth rate of 5.3 to 6.1% in 2026 through 2034 is influenced by the replacement of the old solvent-based systems, rehabilitation, demand for protective coatings, and composite materials.
Epoxy Curing Agents Market Assessment and Insights
- North America: North America is estimated to represent a 22–26% share in 2025, with growth at a 5.3–6.1% CAGR between 2026–2034. Demand benefits from infrastructure maintenance, aerospace manufacturing, industrial coatings, electronics, and advanced composite applications.
- US: The US accounts for an estimated 72–76% share of North American demand in 2025 and is projected to expand at a 5.4–6.2% CAGR during 2026–2034, supported by industrial refurbishment and aerospace applications.
- Europe: Europe represents approximately 23–27% of global demand in 2025 and is expected to grow at a 4.8–5.7% CAGR through 2034. Germany, Italy, France, the UK, and Spain provide strong demand from automotive, industrial coatings, renewable energy, and electronics.
- Asia Pacific: Asia Pacific holds an estimated 34–38% share in 2025 and is projected to grow at a 5.8–6.7% CAGR during 2026–2034. China, Japan, South Korea, and India lead demand through electronics, construction, automotive, wind energy, and manufacturing expansion.
- Largest Segment: Amines are estimated to command a 39–43% market share in 2025 and grow at a 5.5–6.3% CAGR, reflecting broad formulation flexibility and ambient-temperature curing.
- High Growth Segment: Electronics is estimated to hold a 17–21% share in 2025 and expand at a 6.4–7.3% CAGR, supported by encapsulation, insulation, semiconductor packaging, and electrical reliability requirements.
- Key companies analyzed in detail: Aditya Birla Chemicals (Thailand) Private Limited, Atul Limited, BASF SE, Cardolite Corporation, Evonik Industries AG, Hexion Inc., Huntsman Corporation, KUKDO CHEMICAL CO., LTD., Mitsubishi Chemical Group Corporation, Olin Corporation.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The shift in technology development is away from commodity hardeners to application-specific chemistries where curing kinetics, pot life, viscosity, toughness, and resistance are optimally balanced. Amine, polyamide, imidazole, anhydride, and specialty formulations will be developed for processes at lower temperatures, high solid coating systems, electronics, and composite applications. Regional supply resilience, feedstock integration, application laboratory facilities, and custom formulation support will become key production approaches. These developments will increase the scope of curing agent technologies beyond commodity ingredients to critical formulation inputs.
In the future, manufacturing in emerging markets in Asia will generate more formulation development investments and resources. Increasing pressure to reduce volatile organic compounds emissions will drive the development of low-emission and solvent-free curing systems, whereas renewable raw materials will enable product differentiation. Modernizing infrastructure, electric mobility, renewable energy systems, and increased electronics content in manufactured goods will ensure continued demand for curing agents which provide predictability of processing and durability.
Epoxy Curing Agents Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 6.35 Billion |
| Market Size by 2034 | US$ 10.05 Billion |
| Global CAGR (2026 - 2034) | 5.90% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Epoxy Curing Agents Market Analysis
Demand is highly associated with the use of epoxy resin, where the curing agent will affect processing characteristics and the final thermoset structure. In coatings, the key factor would be the need for corrosion protection and abrasion resistance. On the other hand, bonding and curing times are very important in adhesives while strength and heat resistance are the primary considerations in composites. Electronics require the properties of electrical insulation and dimensional stability.
The supply chain in the Epoxy Curing Agents Market encompasses the suppliers of the basic feedstocks, curing agent makers, epoxy resin makers, formulators, distributors, component makers, and industrial end users. Supply is still affected by petrochemical intermediaries, specialty amines, aromatic materials, and bio-sourced feedstocks. Companies with wide-ranging chemistry capabilities have the flexibility to vary formulations according to changes in raw material supply and regulations. The regional manufacturing capability of producers is now gaining significance with customers demanding reduced delivery time.
Diversified chemical companies and specialized chemical companies mentioned in the Epoxy Curing Agents Market highlights concentrating on the curing technology form the competitive environment. The BASF SE has diversified amine products. On the other hand, the Evonik Industries AG is competing by having Ancamine specialty technologies. The Huntsman Corporation provides the ARADUR family of products in the polyamide, polyamidoamine, amine, anhydride, and related chemistries. The Cardolite Corporation provides phenalkamines and phenalkamides products from the cashew nutshell liquid. Atul Limited has a diversified manufacturing base of India.
Positioning of the formulators has become a combination of specialization and diversification. Formulations have become more important than volumes. Companies such as Hexion Inc., Olin Corporation, Mitsubishi Chemical Group Corporation, KUKDO CHEMICAL CO., LTD., Aditya Birla Chemicals (Thailand) Private Limited, and Atul Limited can offer alternate sources of supply regionally and internationally. Investment priorities include reliability of capacity, development of applications, renewable feedstocks, low-emission chemistries, and rapid curing.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
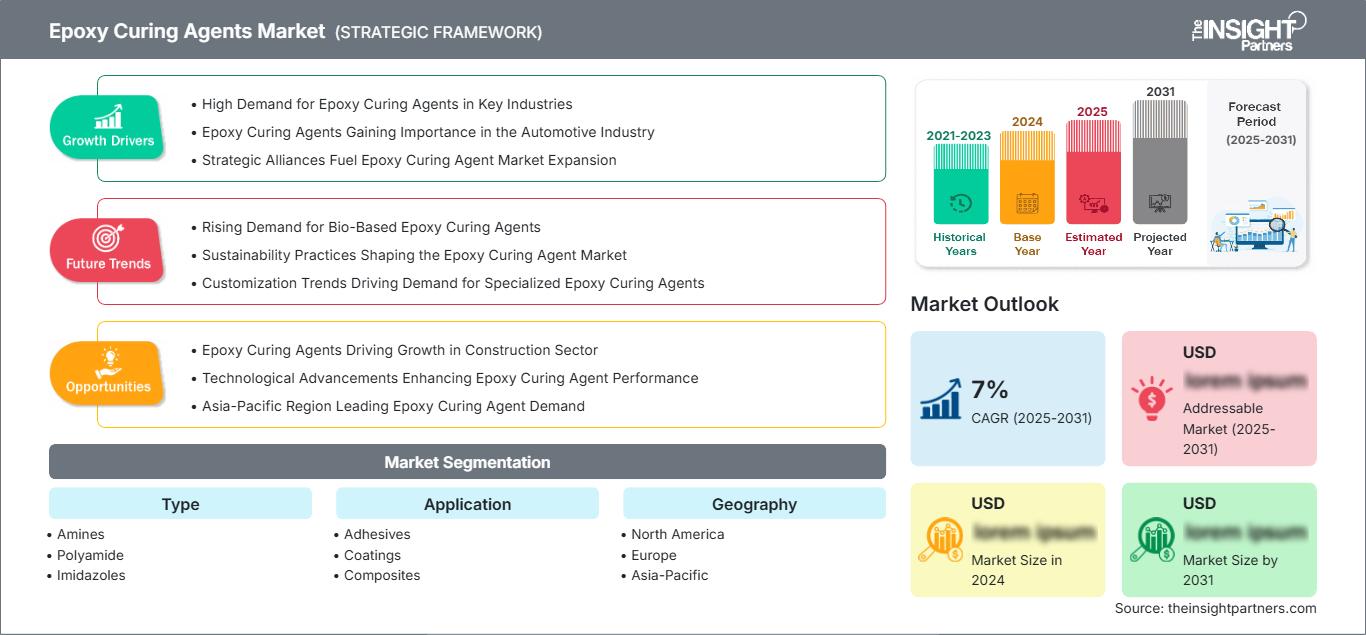
Epoxy Curing Agents Market: Strategic Insights
Regional Insights
North America Epoxy Curing Agents Market
North America is expected to be responsible for 22-26% of the Epoxy Curing Agents Market Share in 2025, with a forecasted CAGR of 5.3-6.1% until 2034. North America enjoys strong existing markets for aerospace, automotive, construction, electronics, marine and industrial maintenance applications. Protective coatings will continue to be important since epoxy coating systems can provide corrosion protection for steel structures, pipelines, floors, bridges and machinery. In addition to this, demand will be driven by composite production for aircrafts, wind power components, recreation equipment and transportation infrastructures. Technical requirements will increasingly demand low emission, fast cure, moisture resistance and high solids materials.
North America's supply industry encompasses leading chemical producers as well as specialty formulators for domestic and export markets. The United States will be the primary demand market whereas Canada will contribute through infrastructure, energy, transportation and industrial applications. Increasingly, buyers from the region will consider performance of the curing agents in the overall formulation and not just the purchase cost. This drives suppliers to produce application-specific products that have longer working life, faster curing properties and better resistance to moisture, temperature fluctuations and chemicals.
U.S. Epoxy Curing Agents Market
The U.S. accounts for about 72-76% of North American demand in 2025, growing at a 5.4-6.2% CAGR up to 2034. Market presence of the U.S. is a result of its heavy industrial infrastructure, aerospace production, automobile manufacturing, electronics, construction, and protective coating demand. Uses vary from factory floors and anticorrosive coatings to structural adhesives, composites, and electrical encapsulants. Technical centers and supply chains of local and multinational producers allow fast customization of formulations according to demands of industry consumers.
Reconstruction of old facilities and necessity to use durable materials with long-term maintenance cycles affect demand as well. Aerospace and defense sectors use high temperature and high strength epoxies; electronics producers use curing systems providing precise curing process, low ionic contamination, resistance to thermal cycling and electrical insulation. Thus, the market of the U.S. is relatively diverse, so dependence on one sector of applications is unlikely, and manufacturers should develop specialty curing agents.
Europe Epoxy Curing Agents Market
It is expected that Europe will have an 23–27% market share in 2025 and a 4.8–5.7% CAGR until 2034. Leading countries include Germany due to its automotive, machinery, coatings, electronics, and manufacturing industries. Demand in the UK comes from applications in aerospace, infrastructure, marine, and advanced manufacturing. France, Italy, and Spain generate demand in transportation, construction, renewables, industrial maintenance, and coatings.
In Germany, high performance of engineering industry creates a need for epoxy systems requiring careful processing. Electrification of automobiles also creates additional demand in adhesives, insulation, and composite materials. At the same time, European formulators are adjusting their products to meet environmental regulations through reduction in the solvents and development of high-solids or solvent-free formulations. All these factors work to advantage of curing agents demonstrating good properties in terms of low emissions and efficient processing.
In France, Italy, and Spain, there are infrastructure rehabilitation, industrial coatings, construction, equipment for renewable energy, transportation, and marine applications. Procurement in southern European markets gives more weight to regulations, safety of workers' health, durability, and long-term performance.
APAC Epoxy Curing Agents Market
APAC accounts for an estimated 34–38% of world demand in 2025 and is expected to register a 5.8–6.7% CAGR until 2034. In the region, the largest markets are China, Japan, South Korea, India, and Australia. Demand from electronics, automotive, construction, wind energy, electrical equipment, and industrial coatings is critical. Growth in manufacturing capacity and infrastructure spending will drive the consumption of epoxy materials in both commodity and specialty uses.
Increasing importance is being placed on local production, electronics grade quality, and rapid technical service. China and South Korea capitalize on electronics/semiconductor clusters; Japan on advanced manufacturing; India on infrastructure/industrial growth; and Australia on mining/infrastructure demand. Government investments in manufacturing, renewable energy, and transportation will increase the demand for durable adhesives, coatings, composites, and electrical encapsulants.
Middle East & Africa Epoxy Curing Agents Market
Demand in Middle East and Africa is relatively low, however, fueled by oil and gas, infrastructure, construction, industrial flooring, marine equipment, and utilities. Saudi Arabia and UAE are dominant players in the region while South Africa is significant industrial player. It is anticipated that the region will witness growth of 4.7% to 5.6% CAGR till 2034 since infrastructure and energy projects require anticorrosive products.
The main driving force for demand in Saudi Arabia is the massive investments into industries and infrastructure development in the country, while in UAE – construction, transport, marine and energy projects, and South Africa – mining, manufacturing, infrastructure maintenance and power industry. Rest of MEA is still highly fragmented market with demand driven by projects. Moisture-resistant and fast-curing systems are strategic for difficult conditions.
Segmentation Analysis
Type
The type segment in the Epoxy Curing Agents Market remains central to formulation selection because curing chemistry determines reaction rate, working life, mechanical properties, thermal behavior, chemical resistance, and application temperature. Amines are expected to retain the largest position, while specialty chemistries gain attention where low emissions, rapid curing, high-temperature resistance, or specific processing windows are required. The overall type segment is modelled to expand at a 5.4–6.2% CAGR during 2026–2034.
- Amines: Amines hold the strongest position because they provide broad formulation flexibility, ambient-temperature curing, and compatibility with coatings, adhesives, composites, and electrical applications.
- Polyamide: Polyamide curing agents remain important for protective coatings and adhesives where flexibility, adhesion, chemical resistance, and tolerance to less-than-ideal substrates are valued.
- Imidazoles: Imidazoles serve specialized applications requiring accelerated curing and strong thermal performance, particularly where latent or elevated-temperature curing behavior improves manufacturing efficiency.
- Polymercaptan: Polymercaptan systems address applications requiring exceptionally rapid curing, including repair and bonding formulations where short processing cycles provide operational advantages.
- Anhydrides: Anhydrides are strategically important in electrical and electronic systems because they support high-temperature performance, dimensional stability, and durable encapsulation.
Application
The application segment in the Epoxy Curing Agents Market is driven by different performance priorities across industrial users. Coatings emphasize corrosion protection and surface durability, adhesives require adhesion and controlled cure, composites demand strength and thermal stability, and electronics require electrical insulation and reliable encapsulation. Application-specific formulation development should support a 5.7–6.5% CAGR during 2026–2034 as manufacturers move toward higher-performance epoxy systems.
- Adhesives: Adhesives require balanced viscosity, wetting, bond strength, toughness, and cure speed, supporting curing-agent demand across construction, transportation, industrial assembly, and engineered components.
- Coatings: Coatings remain a major outlet because epoxy systems provide durable protection for concrete and metals exposed to chemicals, moisture, abrasion, and corrosive environments.
- Composites: Composite applications prioritize high mechanical strength, thermal stability, fiber adhesion, and predictable cure behavior for aerospace, automotive, wind, infrastructure, and advanced manufacturing.
- Electronics: Electronics applications require precise curing, low moisture uptake, electrical insulation, thermal stability, and dimensional reliability across encapsulation, potting, circuit protection, and power components.
Opportunity Snapshot
| Application | Revenue Contribution | Trend Tag | Adoption Stage |
| Adhesives | High | Structural Bonding | Mature |
| Coatings | High | Low VOC | Mature |
| Composites | Medium | Lightweight Structures | Scaling |
| Electronics | Medium | Thermal Management | Scaling |
Epoxy Curing Agents Market Growth Drivers and Impact Analysis
Low-VOC and Solvent-Free Formulation Requirements
Environmental requirements are encouraging formulators to reduce solvent dependence while preserving application performance. Low-VOC and solvent-free epoxy systems require curing agents that provide adequate flow, pot life, surface appearance, adhesion, and cure under practical production conditions. This is particularly relevant for flooring, industrial maintenance, protective coatings, and enclosed manufacturing environments. The commercial impact extends beyond regulatory compliance because lower-emission systems can reduce ventilation requirements and improve workplace conditions. Suppliers that combine low emissions with fast property development can command stronger positions in specification-driven projects. Product development is therefore shifting toward reactive or highly efficient chemistries that minimize the need for additional solvents or reactive diluents while maintaining coating quality and durability.
Infrastructure Protection and Industrial Asset Rehabilitation
Aging industrial assets, bridges, floors, pipelines, tanks, and energy infrastructure require maintenance systems capable of extending service life without lengthy shutdowns. Epoxy curing agents market influence adhesion, chemical resistance, cure speed, moisture tolerance, and final coating durability, making them critical to rehabilitation performance. Demand is consequently moving toward formulations that can cure reliably under difficult site conditions, including low temperatures, high humidity, and imperfect substrates. Rapid-return-to-service technologies can improve project economics by reducing downtime and accelerating maintenance schedules. Suppliers that develop curing agents for concrete, steel, marine assets, and chemical-processing environments can address a broad range of refurbishment requirements. The driver also supports premium specialty products because failure costs often exceed the initial material price.
Expansion of Advanced Electronics and Electrical Systems
The increasing complexity of electrical and electronic equipment is raising requirements for encapsulation, insulation, bonding, and protection materials. Epoxy systems must withstand thermal cycling, moisture exposure, mechanical stress, and electrical loads while maintaining dimensional stability. Curing agents directly influence glass transition behavior, adhesion, crosslink density, and processing characteristics, making chemistry selection important for reliability. Growth in power electronics, electric vehicles, telecommunications equipment, industrial automation, and renewable-energy systems is creating additional application opportunities. Manufacturers are consequently developing formulations with tighter process windows and improved thermal and electrical performance. Suppliers capable of delivering consistent purity, controlled reaction kinetics, and application-specific technical support can strengthen relationships with electronics manufacturers and compounders seeking repeatable production quality.
Epoxy Curing Agents Market Future Trends
Bio-Based and Mass-Balance Curing Chemistry
Bio-based and mass-balance approaches are likely to become more visible as formulators seek lower-carbon alternatives without sacrificing established processing performance. Cashew nutshell liquid-derived technologies demonstrate how renewable feedstocks can be incorporated into specialty curing systems, particularly phenalkamines and phenalkamides. Future development will likely focus on increasing renewable content while preserving viscosity, cure speed, chemical resistance, color stability, and mechanical properties. Certification, traceability, and lifecycle assessment will become increasingly important when customers compare competing formulations. The most commercially attractive products will be drop-in or near-drop-in alternatives requiring minimal reformulation. This trend can also create differentiation for suppliers that control renewable feedstock sourcing, maintain consistent quality, and provide documented environmental attributes alongside technical performance.
Application-Specific Fast-Cure Systems
Future product development in the Epoxy Curing Agents Market Trends is expected to emphasize curing agents engineered around precise application conditions rather than broad generic performance. Protective coatings may require fast cure at low temperatures, flooring systems may prioritize moisture tolerance and rapid return to service, while electronics require controlled thermal behavior and reliable encapsulation. Such requirements are encouraging suppliers to optimize reaction kinetics, pot life, surface quality, and final properties simultaneously. Digital formulation tools and application testing can accelerate this development by allowing producers to evaluate curing behavior across temperature, humidity, substrate, and resin combinations. Competitive differentiation will increasingly depend on solving specific processing problems rather than simply offering a larger product catalogue. This approach should support higher-value specialty chemistry across multiple industrial applications.
Epoxy Curing Agents Market Opportunities
Regional Manufacturing and Supply Localization
The concentration of chemical production in selected regions creates opportunities for manufacturers to establish localized curing-agent capacity, blending operations, and technical centers closer to customers. Asia Pacific Epoxy Curing Agents Market Forecast is particularly attractive because electronics, automotive, infrastructure, and renewable-energy manufacturing are expanding simultaneously. India offers an additional opportunity through industrialization, construction, and growing advanced-materials capabilities. Local production can reduce transportation exposure, improve delivery reliability, and enable formulation customization for regional climate and processing conditions. Companies entering these markets should prioritize flexible plants capable of producing multiple chemistries rather than relying on a single high-volume grade. Partnerships with distributors, resin manufacturers, and application formulators can accelerate customer qualification and reduce the time required to establish technical credibility.
Premium Curing Solutions for Composite and Energy Applications
Composite manufacturing and energy infrastructure provide opportunities for higher-value curing agents where mechanical performance and long-term durability are critical. Wind components, electrical equipment, battery-related systems, transportation structures, and advanced industrial components require controlled curing and strong resistance to thermal and environmental stress. Suppliers can capture value by developing formulations optimized for infusion, pultrusion, filament winding, bonding, or encapsulation rather than selling undifferentiated curing agents. Application laboratories and joint development programs can strengthen customer retention because qualification often depends on demonstrated process compatibility. Investment in specialty amines, anhydrides, latent systems, and low-viscosity formulations can therefore create opportunities for premium positioning. The strongest prospects are likely to emerge where material performance directly influences asset reliability, production efficiency, or maintenance costs.
Recent Developments
- April 30, 2026: Evonik Industries AG strengthened its epoxy curing agent portfolio in the Americas with Ancamine® 2868 and Ancamine® 2844, targeting protective, marine, and industrial coatings exposed to low temperatures and high humidity. Ancamine® 2868 enables rapid thin-film curing as a crosslinkable accelerator, while Ancamine® 2844 provides ultra-fast curing and rapid property development at temperatures as low as 5°C, supporting faster return to service and corrosion protection.
- April 16, 2026: Evonik Industries AG launched Ancamine® 2875, a modified polyamine epoxy curing agent designed for ultrafast curing, extended working time, and moisture vapor barrier performance. The product is formulated without alkylphenol accelerators and is certified to meet ASTM F3010 requirements. It targets demanding flooring and coating applications, including systems applied to cold and damp concrete, while supporting low-emission formulations and faster return to service.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for