
Industrial Rugged Embedded Computers Market Trends, Share & Demand by 2034
Coverage: By Type (Handheld Computers, Tablets, Fixed Mounted Devices); Vertical (Forklift, Manufacturing Facility, Vehicle) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00019784
- Category : Electronics and Semiconductor
- No. of Pages : 150
- Available Report Formats :


- Last update date : September 21, 2026


2025 Market Size
US$ 2.03 Bn
Base year value
2034 Forecast
US$ 3.71 Bn
Projected by 2034
CAGR 2026-2034
6.91 %
Growth rate
Addressable Market
US$ 25.90 Bn
(2026-2034)
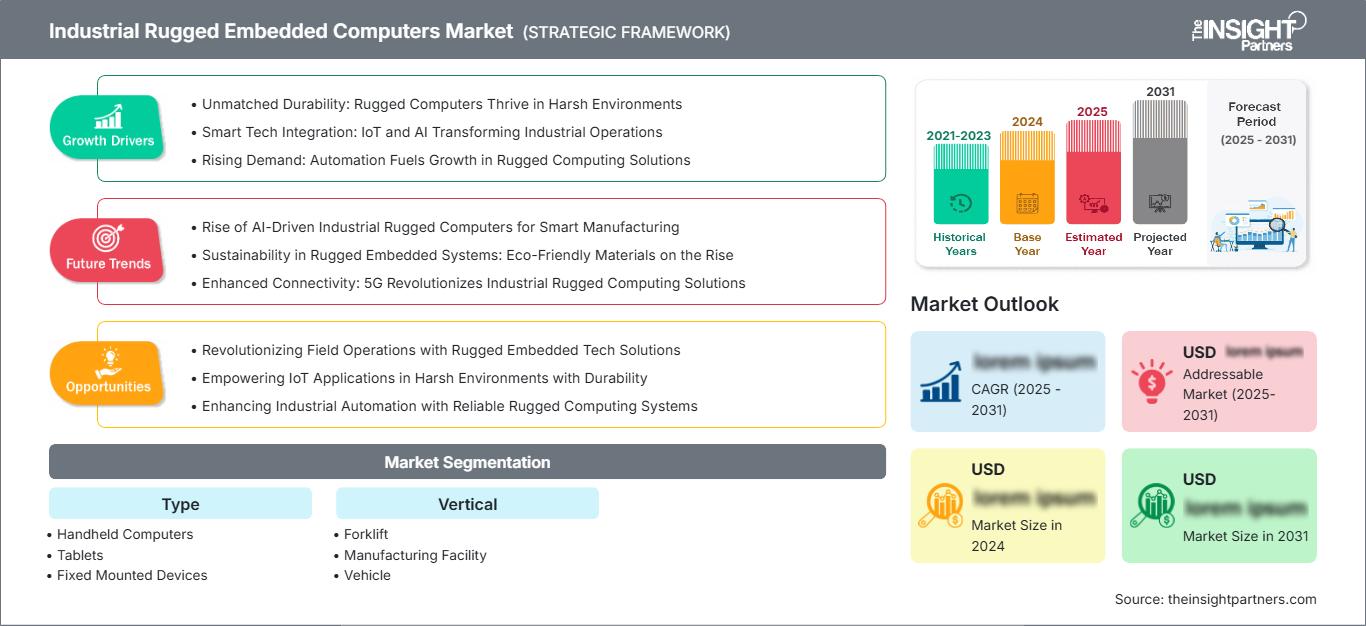
The Industrial Rugged Embedded Computers Market was valued at US$ 2.03 Billion in 2025 and is projected to reach US$ 3.71 Billion by 2034, registering a CAGR of 6.91% during 2026–2034. The market reflects sustained demand for computing platforms that combine processing capability with resistance to shock, vibration, dust, moisture, temperature variation, and extended operating cycles across industrial environments.
North America is positioned for steady expansion, with an estimated CAGR of 6.5–7.5% during 2026–2034. Industrial automation, warehouse modernization, and resilient edge-computing requirements are strengthening procurement, while the Industrial Rugged Embedded Computers Market size is also influenced by demand for long-lifecycle devices in manufacturing, logistics, energy, and transportation.
Industrial Rugged Embedded Computers Market Assessment and Insights
- North America: The region is estimated to hold a 31–35% Industrial Rugged Embedded Computers Market share in 2025 and grow at a CAGR of 6.5–7.5% between 2026–2034, supported by industrial automation, logistics digitization, and rugged edge-computing deployments.
- US: The US represents approximately 75–80% of North American demand in 2025, with a 6.6–7.6% CAGR between 2026–2034 driven by manufacturing, logistics, defense-related technology, and critical infrastructure.
- Europe: Europe is estimated at a 24–28% share in 2025 and a 5.8–6.8% CAGR through 2034, with Germany, the UK, France, Italy, and Spain supported by factory modernization and industrial digitalization.
- Asia Pacific: Asia Pacific is estimated to account for 25–29% in 2025 and expand at a 7.2–8.2% CAGR, led by China, Japan, South Korea, and India as factories adopt connected automation and edge computing.
- Largest Segment: Fixed Mounted Devices represent an estimated 42–46% market share in 2025, with a 6.1–7.1% CAGR between 2026–2034, reflecting persistent factory and vehicle integration requirements.
- High Growth Segment: Tablets are estimated at a 25–29% market share in 2025 and are expected to record a 7.8–8.8% CAGR between 2026–2034 as mobile industrial workflows expand.
- Key companies analyzed in detail: Acura Embedded Systems Inc.; Advantech Co., Ltd.; ARBOR Technology Corp.; Crystal Group Inc.; Datalogic S.p.A.; Dell Inc.; Honeywell International Inc.; JLT Mobile Computers AB; SINTRONES TECHNOLOGY CORP.; Zebra Technologies Corporation.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
Product development in the Industrial Rugged Embedded Computers Market is now favoring fanless designs, high processing densities, fast wireless connections, and edge computing platforms designed for artificial intelligence. End users of industrial products now value lifecycle support, thermal stability, rugged enclosures, and compatibility with legacy automation systems. In parallel, manufacturing approaches are embracing modular designs that allow processor refreshment without platform change and minimize qualification effort and extended equipment lifecycles.
Funding considerations are being focused on connected factories, smart warehouses, automated material handling, and onboard computing capabilities. Deployments in Southeast Asia and India are augmenting established deployments in North America and Europe. The cybersecurity needs, industrial networking standards, and manufacturing upgrades programs funded by governments have also made the procurement of devices with secure local processing, reliable communication capabilities, and software updates a priority.
Industrial Rugged Embedded Computers Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 2.03 Billion |
| Market Size by 2034 | US$ 3.71 Billion |
| Global CAGR (2026 - 2034) | 6.91% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Industrial Rugged Embedded Computers Market Analysis
The Industrial Rugged Embedded Computers Market growth is highly dependent on the automation investments, warehouse digitalization, and transition of industrial applications to edge computing. The original equipment manufacturer dictates the processors, memory, displays, storage, wireless modules, and rugged enclosure based on the operating environment. The system integrator configures devices used for forklifts, production workstations, mobile machinery, and industrial vehicles, with the help of software companies that assist in fleet management, diagnostics, cybersecurity, and application installation.
The supply side continues to be driven by the availability of semiconductors, displays, memory prices, and rugged enclosure manufacturing. Industrial customers tend to have a higher product availability requirement than the consumer electronics customers, prompting the suppliers to ensure control over the components evolution and proper validation process. Nearshoring and multiple sourcing become increasingly important as the manufacturers try to reduce the risks of shortages and logistic difficulties.
Analysis of Industrial Rugged Embedded Computers Market reveals a competitive landscape that focuses on differentiation by means of ruggedness, computing capability, connectivity, life-cycle commitment and application-specific integration. Advantech Co., Ltd., ARBOR Technology Corp., and Crystal Group Inc. focus on industrial and embedded computers, Dell Inc. on enterprise computer computing capability in rugged conditions, Honeywell International Inc. and Zebra Technologies Corporation on rugged hardware and software ecosystem solutions.
Growing investments include AI computing, machine vision, fast wireless connection, and device management software. Leading companies in mobile computing market are Datalogic S.p.A. and JLT Mobile Computers AB. Acura Embedded Systems Inc. and SINTRONES TECHNOLOGY CORP. provide special embedded computer solutions. All these strategies point out the trend towards moving away from separate devices towards computing platform solutions.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Industrial Rugged Embedded Computers Market: Strategic Insights
Regional Insights
North America Industrial Rugged Embedded Computers Market
North America is estimated to account for 31–35% of the global market in 2025 and register a 6.5–7.5% CAGR through 2034. The United States is still the key demand driver, backed up by advanced production technology, automation of logistics, energy facilities, and industrial software infrastructure. Canada provides the supply from mining, transportation, utilities, and remote operations, which require reliable computing capabilities.
There is a growing trend towards regional demand for systems that can operate non-stop in changing temperatures, vibrations, dusty conditions, and while on the move. This is why forklift computer solutions, computer systems on board of vehicles, factory controllers, and ruggedized tablets are more often used by organizations due to digitization of their operations.
U.S. Industrial Rugged Embedded Computers Market
The US represents approximately 75–80% of North American demand in 2025 and is projected to grow at a 6.6–7.6% CAGR through 2034. Demand occurs within manufacturing plants, distribution centers, warehouses, transport fleets, utility, and field operations. Relevant technology portfolios are held by Advantech Co., Ltd., Dell Inc., Honeywell International Inc., and Zebra Technologies Corporation.
Current application emphasis is increasingly focused on real-time inventory tracking, machine control, mobile workers, and connected material handling applications. In the United States, Industrial Rugged Embedded Computers market share leverages industrial Ethernet networks and wide deployment of enterprise software. Increasingly, procurement decisions include considerations of cybersecurity issues, device management life cycles, availability of processors, and system integration with warehouse management and manufacturing execution systems.
Europe Industrial Rugged Embedded Computers Market
The Industrial Rugged Embedded Computers Market report shows that Europe is estimated to represent 24–28% of the global market in 2025 and grow at a 5.8–6.8% CAGR through 2034. Germany leads regional demand, followed by the UK, France, Italy, and Spain. Industrial automation, automotive production, warehouse modernization, and machine connectivity provide a broad installed base for rugged embedded computing.
The UK concentrates on logistics, transport, utilities, and field services. Mobile computing is used there for distribution and monitoring. Germany has advantages thanks to its numerous industrial clusters and development of Industry 4.0, which needs robust manufacturing computing. The French mix of aerospace, transport, energy and processing industries; the Italian and Spanish industries are also helped by their manufacturing, automotive, logistics and food processing. Energy efficiency and lifecycle management are gaining importance.
APAC Industrial Rugged Embedded Computers Market
APAC is estimated to hold 25–29% of the global market in 2025 and expand at a 7.2–8.2% CAGR through 2034. China drives demand in the region thanks to automated factory production and electronics production, whereas Japan and Korea focus on precise production and robotics. India and Australia offer additional prospects in manufacturing, logistics, mining, and infrastructure.
Government backing of digital manufacturing and industrial automation continues to strengthen investments. Chinese, Japanese, and Korean companies are increasingly implementing edge computing technology into their production processes, while India’s industrialization is leading to increased uptake by manufacturing and logistics companies. The mining and remote asset management sectors in Australia are adding to demand due to tough operating conditions that affect traditional computing systems.
Middle East & Africa Industrial Rugged Embedded Computers Market
Middle East and Africa demand is estimated to expand at a 5.5–6.5% CAGR through 2034, with Saudi Arabia representing a leading market. The investment by UAE in logistics, intelligent infrastructure, and industrial diversification meets the demand while South Africa plays its role in mining, manufacturing, transport, and utilities.
Processes which are energy intensive will demand durable computers in remote/mobile conditions. Digital infrastructure is being installed in Saudi Arabia and UAE for industrial diversification and logistics purposes. In South African mines, there will be a need to have durable computers that will be able to monitor machinery and movement of materials. The Rest of MEA segment is relatively small but has potential.
Segmentation Analysis
Type
The Type segment is projected to expand at a 6.4–7.4% CAGR during 2026–2034. Procurement decisions depend on mobility, installation constraints, processing requirements, and environmental exposure. The Industrial Rugged Embedded Computers Market scope increasingly includes platforms capable of supporting edge analytics while maintaining compact dimensions, low thermal output, and extended operational life.
- Handheld Computers: These devices support highly mobile workflows involving scanning, inspection, maintenance, and inventory handling. Their strategic importance increases where workers need immediate access to enterprise applications without returning to fixed workstations.
- Tablets: Rugged tablets combine larger displays with mobility, supporting production supervision, field service, vehicle workflows, and inspection. Their flexibility makes them increasingly useful where operators alternate between stationary and mobile tasks.
- Fixed Mounted Devices: Fixed mounted platforms remain central to forklifts, machinery, production stations, and vehicle dashboards. Their stable installation enables continuous access to operational applications and dependable integration with industrial peripherals.
Vertical
The Vertical segment is expected to grow at a 6.7–7.7% CAGR during 2026–2034. Demand is shaped by workflow digitization, mobile asset management, and the need for computing platforms that withstand vibration, dust, temperature changes, and continuous industrial use.
- Forklift: Forklift computing supports warehouse execution, inventory movement, picking, replenishment, and real-time task allocation. Vehicle-mounted rugged systems reduce manual data entry and help operators maintain workflow continuity during material handling.
- Manufacturing Facility: Factory applications include production monitoring, quality inspection, maintenance, traceability, and machine interaction. Rugged computers provide dependable interfaces near equipment where conventional office hardware may experience excessive vibration, contamination, or temperature exposure.
- Vehicle: Vehicle-mounted systems support transportation, field service, fleet management, and specialized industrial machinery. Their value increases where continuous connectivity, navigation, diagnostics, and real-time data access are required during movement.
Opportunity Snapshot
| Vertical | Revenue Contribution | Trend Tag | Adoption Stage |
|---|---|---|---|
| Forklift | High | Fleet Mobility | Mature |
| Manufacturing Facility | High | Edge Automation | Scaling |
| Vehicle | Medium | Mobile Edge | Scaling |
Industrial Rugged Embedded Computers Market Growth Drivers and Impact Analysis
Expansion of Industrial Automation and Edge Processing
Data processing for efficiency and decreased latency is being brought closer to the machines. The advantage is immediately apparent for rugged embedded computers since manufacturing facilities need computing machines that have the capacity to withstand vibrations, dust, temperature changes, and uninterrupted use. Edge computing enables data from machines to be processed locally before passing relevant information to central computing facilities. The effect will be most pronounced at facilities with machine vision, predictive maintenance, automated inspection, and connected controllers. Another benefit of rugged computing is the ease with which legacy and digital machines can be connected since computing processors, communication capabilities, and industrial protocols can all be installed on one system.
Growth of Digitized Warehousing and Material Handling
Increased funding is being made available for connecting forklifts, hand-held devices, vehicle-mounted computers, and real-time inventory solutions in warehouses. The business need for investing in these technologies is dictated by the necessity to increase accuracy of picking, reduce movement cycles, and gain immediate access to information about the location of inventory. The relevance of rugged computing is evident as warehouse equipment operates in an environment characterized by numerous shocks, vibrations, dust, temperature variations, and high level of work load. In this context, the choice of the devices takes into account factors such as flexible mounting options, battery life, wireless capabilities, scanning possibilities, and software support. Consequently, the requirement goes far beyond the purchase of new hardware devices as companies tend to standardize their device fleets across several sites.
Industrial Cybersecurity and Lifecycle Requirements
Connected industrial computers increasingly form part of operational technology environments, making cybersecurity and lifecycle support important procurement criteria. Organizations are seeking platforms that can receive security updates, restrict unauthorized access, manage application permissions, and maintain predictable software configurations over extended periods. These requirements favor vendors capable of combining rugged hardware with device management and security capabilities. Lifecycle planning also affects component selection because industrial customers cannot easily replace equipment whenever processors or operating systems change. Vendors therefore differentiate through controlled product revisions, long-term availability commitments, and compatibility testing. The market impact is a gradual shift toward total cost of ownership assessments rather than purchase-price comparisons. For system integrators, standardized secure platforms can also simplify fleet management across geographically distributed factories, warehouses, vehicles, and field operations.
Industrial Rugged Embedded Computers Market Future Trends
AI-Ready Rugged Edge Platforms
The next phase of Industrial Rugged Embedded Computers Market trends will increasingly involve processors with dedicated AI acceleration for machine vision, anomaly detection, worker assistance, and local decision-making. Rather than sending every data stream to centralized infrastructure, industrial systems will increasingly perform selected inference tasks at the point of operation. This approach can reduce latency and improve resilience when network availability is inconsistent. Rugged platforms will therefore evolve beyond durability toward higher compute density, integrated accelerators, and optimized thermal designs. Vendors are likely to offer modular configurations that allow customers to select processor and graphics capabilities according to workload. The strongest opportunities will emerge in manufacturing inspection, autonomous material handling, industrial vehicles, and remote assets where rapid local decisions have direct operational value.
Convergence of Mobile and Fixed Industrial Computing
A second trend will be the convergence of handheld, tablet, vehicle-mounted, and fixed computing experiences through common operating environments and centralized device management. Industrial organizations increasingly expect workers to move between warehouses, production areas, vehicles, and field locations without changing application workflows. Future platforms will consequently emphasize common authentication, shared data models, synchronized applications, and accessory ecosystems. Hardware will remain differentiated by ruggedization level and installation format, while software increasingly creates continuity across device classes. This convergence can reduce training requirements and simplify fleet administration. It also creates opportunities for suppliers that can provide consistent security policies, application deployment, diagnostics, and lifecycle support across diverse hardware configurations, particularly in large multi-site industrial enterprises.
Industrial Rugged Embedded Computers Market Opportunities
Localized Manufacturing and Supply Chain Resilience
Manufacturers can capture new opportunities by establishing regional assembly, validation, and service capabilities for rugged computing platforms. Supply chain disruptions have demonstrated the importance of component flexibility, alternative sourcing, and predictable product availability for industrial buyers. Regional production can shorten replenishment cycles while supporting localized certification and after-sales service. Suppliers that design modular systems around commonly available processors, memory, storage, and communication modules can reduce exposure to component changes without sacrificing product continuity. The Industrial Rugged Embedded Computers Market Forecasts also favors vendors that build partnerships with industrial system integrators, automation providers, and logistics technology companies. Such relationships can create recurring revenue through configuration, maintenance, software support, accessories, and lifecycle services rather than relying solely on initial hardware sales.
Vertical-Specific Platforms for Industrial Workflows
A further opportunity lies in developing application-specific platforms for forklifts, manufacturing lines, and industrial vehicles rather than selling generic rugged computers. Buyers increasingly value integrated scanners, vehicle docks, specialized interfaces, wireless connectivity, display configurations, and software compatibility because these features reduce integration effort. Vendors can differentiate by combining validated hardware with industry-specific mounting systems and application support. Manufacturing customers may prioritize machine interfaces and inspection workloads, whereas forklift operators require visibility, scanning, and vehicle integration. Vehicle applications may emphasize navigation, telemetry, and continuous connectivity. Tailored solutions can therefore support higher customer retention while creating clearer value propositions. Partnerships with warehouse management, manufacturing execution, fleet management, and industrial software providers can further strengthen deployment opportunities.
Recent Developments
- June 2026: Datalogic, a global leader in automatic data capture and industrial automation, announced the launch of Falcon X60/65, its new ultra‑rugged mobile computer engineered to reduce frontline downtime and protect throughput in the most demanding warehouse environments across retail, manufacturing, and transport & logistics (T&L).
- May 2026: WINSYSTEMS, a leader in rugged embedded computing solutions, announced the SYS‑480, a fanless industrial PC engineered for mobile, remote, and unattended edge applications. Built on the Intel Atom Amston Lake x7433RE processor, the SYS‑480 delivers reliable, low‑power performance combined with extensive edge connectivity, long lifecycle support, and rugged environmental compliance.
- August 2025: Axiomtek, a world-renowned leader relentlessly devoted to the research, development, and manufacture of innovative, highly efficient, and reliable industrial computer products, is proud to unveil the eBOX630B — a high-performance fanless embedded AI system designed for the future of edge intelligence. Featuring onboard Intel Core Ultra 7 155H and Intel Core Ultra 5 125H processors, the system delivers next-generation hybrid computing through a tri-compute architecture integrating CPU, Intel Arc GPU (H series), and NPU (Intel AI Boost). Its wide 9–60V DC input ensures flexible deployment across diverse industrial and AI-driven environments.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners provided valuable market intelligence that supported our global go-to-market strategy. Their team was professional, responsive, and attentive to our feedback, providing thoughtful analysis and helpful methodological clarifications throughout the project.
Junmo Kim Chief Financial Officer (CFO), Enertech Co., Ltd.
The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for