
Paint Thinner Market Growth, Demand & Size by 2034
Coverage: By Type (Methyl Ethyl Ketone, Acetone, Turpentine, Toluene, Others); End Use Industry (Building and Construction, Automotive and Transportation, Industrial Equipment, Others) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00027406
- Category : Chemicals and Materials
- No. of Pages : 150
- Available Report Formats :


- Last update date : September 15, 2026


2025 Market Size
US$ 12.16 Bn
Base year value
2034 Forecast
US$ 19.24 Bn
Projected by 2034
CAGR 2026-2034
5.23 %
Growth rate
Addressable Market
US$ 142.44 Bn
(2026-2034)
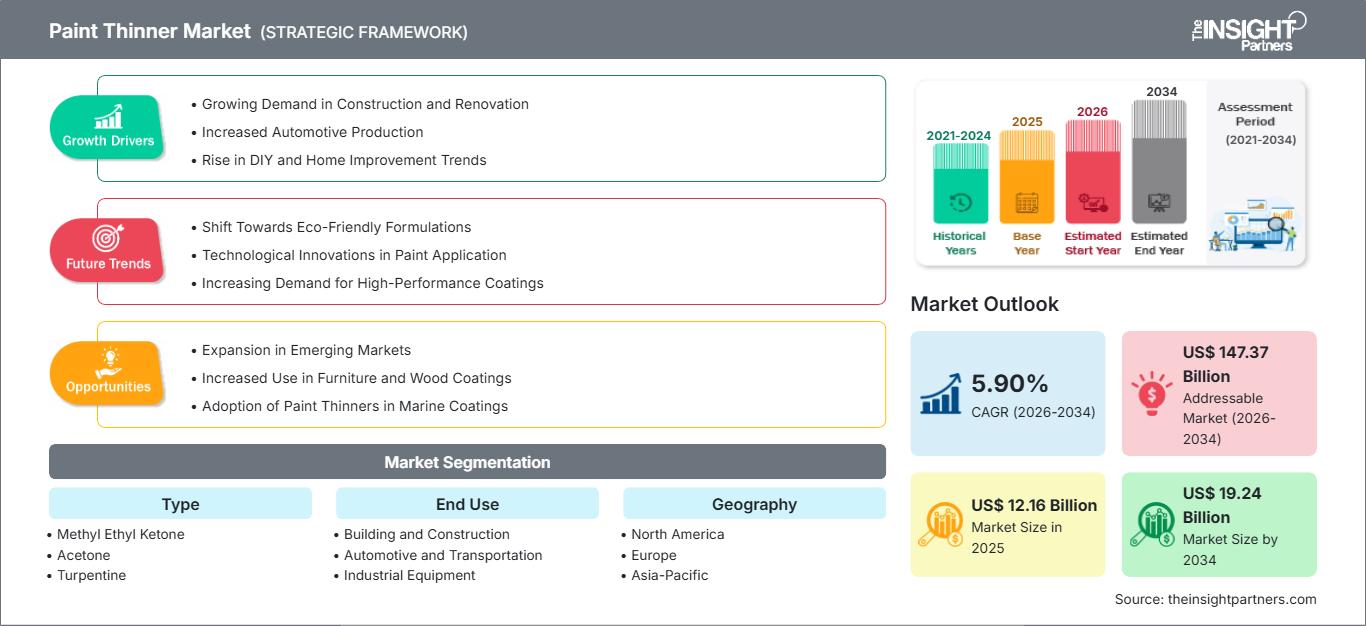
The Paint Thinner market was valued at US$ 12.16 billion in 2025 and is expected to reach US$ 19.24 billion by 2034; it is estimated to record a CAGR of 5.23% during 2026-2034.
Paint Thinner Market Assessment and Insights
- North America: North America is expected to account for approximately 27–31% Paint Thinner Market share in 2025 and grow at a CAGR of 5.1–5.8% between 2026–2034, supported by automotive refinishing, infrastructure maintenance, industrial coatings, and renovation demand.
- US: The US is estimated to represent approximately 78–82% of North America's 2025 demand and is projected to grow at a CAGR of 5.0–5.7% through 2034, led by automotive and industrial applications.
- Europe: Europe is estimated to hold approximately 22–26% share in 2025 and expand at a CAGR of 4.6–5.3% between 2026–2034. Germany, Italy, France, the UK, and Spain remain important markets because of established automotive, industrial, and construction coatings ecosystems.
- Asia Pacific: Asia Pacific is estimated to command approximately 32–36% share in 2025 and register a CAGR of 6.2–7.0% during 2026–2034. China, Japan, India, South Korea, and Australia benefit from expanding manufacturing, construction, transportation, and industrial coating requirements.
- Largest Segment: Solvent Type is estimated to represent approximately 58–63% share in 2025 and grow at a CAGR of 5.5–6.1% during 2026–2034, reflecting broad formulation compatibility.
- High Growth Segment: Automotive and Transportation is estimated to account for approximately 27–31% share in 2025 and grow at a CAGR of 6.1–6.8%, supported by refinishing and component coating activity.
- Key companies analyzed in detail: Akzo Nobel N.V., 3M Company, PPG Industries, Inc., The Sherwin-Williams Company, BASF SE, Chugoku Marine Paints, Ltd., Axalta Coating Systems, LLC, Nippon Paint Holdings Co., Ltd., Jotun A/S, Kansai Paint Co., Ltd.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
Paint Thinner compositions have become more application-oriented in recent years, with their design based on evaporation characteristics, solvency considerations, substrate compatibility, and coating system requirements. The mixtures used in the market are optimized for use in automotive refinish, industrial equipment, and building finishes, while minimizing the emission of undesirable materials. Market supply is still linked to the availability of petrochemical raw materials, economic conditions at refineries, regional chemical capacity, cost of logistics, and regulation impacting solvent selection and formulation.
Growth in the future will depend upon industrialization in Asia Pacific, refurbishment in North America and Europe, and investments in developing countries. Regulatory compliance is prompting manufacturers to create low-emission Paint Thinners and better handling systems without sacrificing cleaning power and dilution capabilities. Industrial consumers are also focusing more on consistency of batches, documentation, safe storage, and compatibility with waterborne and high-solids coatings.
Paint Thinner Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 12.16 Billion |
| Market Size by 2034 | US$ 19.24 Billion |
| Global CAGR (2026 - 2034) | 5.23% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Paint Thinner Market Analysis
The growth trends of the Paint Thinner Market depend on the interplay between coatings production, availability of solvents, refinishing, and maintenance needs. The supply chain includes petrochemical and chemical companies providing acetone, methyl ethyl ketone, toluene, turpentine, and other solvents, and then formulators, distributors, paint makers, automotive refinishing products, and industrial buyers. Depending on the technology used for coating and application, solvent choice involves technical aspects as well.
Market supply factors are determined by the economics of crude oil and natural gas, refinery capacity usage, chemical company operating capacity, transportation options, and reliance on imports. Solvent supply chains have been developed for acetone, toluene, and methyl ethyl ketone. Turpentine gives an additional option in the form of biologically-based solvent. Consequently, producers have to consider feedstock prices, purity, evaporation characteristics, and safety regulations when developing application-oriented product formulations.
Competitive positioning includes product breadth, distribution network, technical service, formulation capability, and access to downstream coatings customers. In the Paint Thinner Market, it is stated that big coating manufacturers benefit from formulation integration, whereas specialty players are differentiated by custom-blend capability, regional availability, packaging versatility, and application assistance. Akzo Nobel N.V., PPG Industries, Inc., The Sherwin-Williams Company, and Nippon Paint Holdings Co., Ltd. enjoy broad connections in architectural, industrial, and transportation coatings.
Investments in the Paint Thinner Market become more focused on portfolio management, regional production, sustainable chemistry, and higher added-value coatings. BASF SE, Axalta Coating Systems, LLC, Chugoku Marine Paints, Ltd., Jotun A/S, and Kansai Paint Co., Ltd. are involved in specialized coating applications where solvents remain relevant. Industrial and maintenance applications are added by 3M Company. The competitive advantage thus becomes more related to formulations, regulations, technical services, and product performance than to solvents.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Paint Thinner Market: Strategic Insights
Regional Insights
North America Paint Thinner Market
North America is estimated to hold 27–31% share in 2025 and is projected to grow at a CAGR of 5.1–5.8% through 2034. There are well-developed networks of refinishes for automobiles, industrial equipment maintenance, construction renovations, and coatings suppliers. Demand is mostly present in the US, but Canada supplies the region through its infrastructure, manufacturing, and building renovation processes. The choice of solvents depends on the occupational requirements, VOC management needs, and performance of application of the solvent by clients.
The local supply chain involves production of some chemicals in the region, as well as importing of specific solvents and chemical formulations. Industrial consumers value predictable drying time, efficiency, good compatibility with coatings and good availability of solvents. Automotive body shops are constant sources of demand, whereas building renovations create periodic ones. The attention of regulators to solvents creates an opportunity for replacement and better handling, thus favoring low-emission solvents and solvent formulations. Distribution channels are still necessary, as users tend to purchase solvents from coatings suppliers, rather than from chemical manufacturers.
U.S. Paint Thinner Market
The US represents approximately 78–82% of North American 2025 Paint Thinner Market and is expected to grow at a CAGR of 5.0–5.7% during 2026–2034. Refinishing, maintenance, repair, and restoration are key sources of ongoing consumption. It possesses the necessary logistics capabilities to deliver both generic and specialized solutions and has a strong network of professionals as customers, making it easier for the producers to distribute their products. 3M Company, PPG Industries, Inc., and The Sherwin-Williams Company along with other coatings manufacturers have long-term business relationships with their industrial and automotive clients.
The application of coatings requires increasing control over evaporation, proper surface treatment, compatibility with primers and topcoats, and enhanced safety. Moreover, there is a legislative pressure related to selection of proper solvents. The US Environmental Protection Agency has been regulating the use of methylene chloride in consumer paint and coating removal and added regulations for its industrial and commercial use, which encourages the substitution with other chemicals. In such a situation, suppliers with a proven documentation and safe alternatives will gain an advantage.
Europe Paint Thinner Market
Europe is estimated to account for 22–26% share in 2025 and is projected to expand at a CAGR of 4.6–5.3% through 2034. Germany is the dominant country due to automotive manufacturing, industrial equipment production, machinery, and coatings applications. The UK continues to provide demand for maintenance and renovations, whereas France, Italy, and Spain are involved through automotive, furniture, construction, marine, and industrial applications. European consumers have become more interested in VOC control, worker safety, and efficient formulations.
The German industrial sector ensures stable demand for solvents linked to machinery, automotive refinishing, and coatings. Italy's furniture and industrial manufacturing sectors help create specific demand for solvents, whereas France includes automotive, construction, and industrial demand. Spain gets benefits from construction renovations, automotive services, and manufacturing. European regulations motivate suppliers to develop formulations to lower hazardous exposure without affecting the coating. As a result, companies have to compete with lower emission options, formulation documentation, solvent blending, and compatibility with waterborne and high solids coatings.
APAC Paint Thinner Market
APAC is estimated to represent 32–36% share in 2025 and is projected to register a CAGR of 6.2–7.0% through 2034. China is still the largest market, followed by Japan, South Korea, India, and Australia. Solvents have wide application in industries for manufacturing, in vehicles, construction activities, ship building, machinery, and infrastructure development. India too is seeing advantages from expansion of manufacturing facilities and coatings. More and more producers in this region are focusing on dependability, formula uniformity, and economy of their solvents.
China and South Korea are helped by their large petrochemicals industry, Japan is helping with advanced coatings technology. India’s industrialization and investments in infrastructure add more to the demand potential. Manufacturing promotion policies and urban development along with transport infrastructure development support downstream use. The contribution of Australia lies in mining equipment, construction, and maintenance applications.
Middle East & Africa Paint Thinner Market
Middle East & Africa is projected to expand at approximately 4.8–5.6% CAGR through 2034. Saudi Arabia represents a leading market because of industrial diversification, infrastructure investment, energy projects, and coatings requirements associated with construction and equipment maintenance. The UAE contributes through commercial construction, transportation, marine applications, and refurbishment activity.
The South African market is crucial for automotive, mining, industrial equipment, and construction end-users, while RoMEA will have a demand for products that will be dependent on infrastructure development and industrialization. Availability of energy and petrochemical linkages provides an advantage for feedstock, but logistics are still a factor in many of the African countries. Manufacturers with regional warehousing capabilities and support services along with flexible packaging will cater to the fragmented customer base. The investment in construction and infrastructure provides recurring opportunities in the region.
Segmentation Analysis
Type
Type segmentation is shaped by solvent polarity, evaporation behavior, solvency strength, coating compatibility, and end-use requirements. The segment is expected to grow at a CAGR of 5.5–6.1% during 2026–2034. Formulators increasingly select individual solvents or blends according to coating chemistry, application speed, surface condition, worker requirements, and environmental constraints.
- Methyl Ethyl Ketone: Methyl ethyl ketone provides strong solvency and relatively rapid evaporation, supporting industrial formulations, cleaning applications, and coating systems requiring efficient solvent release and effective resin dissolution.
- Acetone: Acetone is valued for high volatility, broad availability, and strong solvency. Its rapid evaporation makes it useful for cleaning, surface preparation, and formulations where quick solvent release is advantageous.
- Turpentine: Turpentine remains relevant in selected solvent-based coatings and specialty applications because of its traditional compatibility with certain resins and its differentiated renewable-origin positioning compared with petrochemical solvents.
- Toluene: Toluene provides strong solvency for numerous resin systems and remains important in industrial coating applications. Its established supply infrastructure supports formulation consistency and broad commercial availability.
End Use
End Use demand is expected to expand at a CAGR of 5.8–6.4% through 2034. Consumption depends on coating application volumes, maintenance cycles, vehicle refinishing, construction activity, and industrial production. Automotive and transportation represents a particularly important growth area because refinishing requires controlled solvent performance across multiple coating stages.
- Building and Construction: Building and construction applications use thinner formulations for coating preparation, equipment cleaning, renovation, and maintenance. Demand follows residential, commercial, infrastructure, and refurbishment activity across developed and emerging economies.
- Automotive and Transportation: Automotive and transportation applications require reliable solvent performance for refinishing, cleaning, surface preparation, and coating adjustment. Professional body shops and manufacturing facilities value consistent drying behavior and compatibility with coating systems.
- Industrial Equipment: Industrial equipment applications include machinery maintenance, coating preparation, cleaning, and refurbishment. Demand is supported by manufacturing activity, asset maintenance programs, protective coatings, and the need to minimize equipment downtime.
Opportunity Snapshot
| End Use | Revenue Contribution | Trend Tag | Adoption Stage |
|---|---|---|---|
| Building and Construction | High | Renovation Cycles | Mature |
| Automotive and Transportation | High | Refinish Demand | Scaling |
| Industrial Equipment | Medium | Asset Maintenance | Scaling |
Paint Thinner Market Growth Drivers and Impact Analysis
Expansion of Automotive Refinishing and Vehicle Maintenance
Auto refinishing still is an important source of consumption as automotive repairers need solvents for cleaning purposes, surface preparation, viscosity adjustment, and tool maintenance. An increase in the number of vehicles, repairs, fleet maintenance, and restoration of second-hand vehicles increases the frequency of solvent consumption. The commercial auto body shops will also benefit from predictable evaporation properties as inconsistent solvent properties may lead to adverse impacts on the quality of the coating finish, curing process, adherence, and reworking ratio. In the developing countries, the development of the vehicle fleet also leads to maintenance needs as old vehicles will be used for a longer time period. The effect will affect all the participants – distributors, coating suppliers, and solvent producers as the refinishing system uses a number of compatible products.
Industrial Maintenance and Protective Coating Consumption
There is constant need for re-coating of equipment, cleaning, degreasing and preparation of surfaces; hence, there will be continual demand for solvents. Equipment maintenance is conducted by manufacturing companies, machinery manufacturers, warehouses, power stations, marine assets, and infrastructure managers among others using planned and corrective maintenance methods. With the value of industrial assets increasing and costs of downtime rising, there will be growing emphasis on the importance of coating preparation and cleaning. Paint thinners will help in such operations through their ability to enhance coating properties and clean tools and surfaces. Solvent products will have greatest effects in places where protective coatings are applied in order to control corrosion and increase life span of assets. This will present opportunities for suppliers of standardized products and customized products tailored to specific industrial environments.
Construction Renovation and Infrastructure Investment
Renovation and infrastructure projects generate demand for coatings used on buildings, bridges, industrial structures, transportation facilities, and commercial properties. Solvent products are required for selected coating preparation, cleaning, equipment maintenance, and refurbishment processes. Infrastructure expansion in developing economies increases the installed base requiring protective maintenance, while mature markets generate recurring renovation demand as buildings and industrial assets age. Government investment can therefore influence downstream consumption through construction activity, transport infrastructure, and public-facility upgrades. The effect is particularly relevant for regional distributors because projects frequently require localized availability, dependable packaging, and technical assistance. Manufacturers that align solvent formulations with modern coating systems and application practices can improve customer retention while supporting contractors seeking predictable application results across large renovation and maintenance projects.
Paint Thinner Market Future Trends
Shift Toward Lower-Emission Solvent Formulations
Future Paint Thinner Market trends will increasingly reflect regulatory pressure, occupational safety, and customer preference for lower-emission formulations. Manufacturers are expected to optimize solvent blends around evaporation efficiency, reduced hazardous exposure, and compatibility with waterborne or high-solids coating systems. Substitution will not occur uniformly because industrial users still require strong solvency for demanding applications. Instead, product portfolios are likely to become more segmented, with conventional solvents retained for specialized uses and alternative blends introduced where performance can be maintained. Digital safety documentation, clearer labeling, and application-specific technical guidance will also become more important. Suppliers that combine formulation performance with compliance support should be better positioned to retain professional customers as environmental and workplace requirements become more stringent across major industrial markets.
Application-Specific Blending and Technical Differentiation
Solvent suppliers are likely to increase application-specific formulation capabilities as customers seek predictable performance across diverse coating chemistries. Instead of relying on a single universal thinner, professional users increasingly require products matched to resin type, temperature, humidity, application equipment, and drying requirements. This creates opportunities for customized blends supported by technical service and formulation guidance. Manufacturers may also use digital tools to improve product selection, safety communication, inventory planning, and troubleshooting. Regional production and localized blending can shorten lead times while allowing suppliers to respond to changing customer specifications. Over the forecast period, competitive differentiation should therefore shift toward technical performance, formulation flexibility, quality consistency, and application support, particularly in automotive refinishing and industrial coating environments where rework costs are significant.
Paint Thinner Market Opportunities
Regional Blending Hubs for Emerging Manufacturing Economies
Emerging manufacturing economies provide an attractive investment opportunity for regional blending and distribution facilities. India, Southeast Asia, selected Middle Eastern markets, and Latin American industrial centers are expanding manufacturing, automotive, construction, and equipment-maintenance activity. Localized blending can reduce transportation costs, improve supply responsiveness, and allow manufacturers to adapt formulations to customer specifications and regulatory requirements. Investors can prioritize facilities near petrochemical feedstock sources, major industrial clusters, and logistics infrastructure. Partnerships with coatings distributors and automotive refinishing networks can accelerate market access without requiring extensive retail infrastructure. The Paint Thinner Market Forecasts opportunity is strongest where solvent demand is growing alongside domestic coatings production, vehicle fleets, and industrial asset bases. Regional hubs can also provide greater resilience against international shipping disruptions and sudden changes in imported solvent availability.
Premium Low-VOC and Specialty Solvent Portfolio Development
Investment in premium solvent blends provides an opportunity to move beyond commodity price competition. Customers increasingly require formulations that balance solvency, evaporation, application performance, worker considerations, and environmental compliance. Producers can develop differentiated products for automotive refinishing, industrial maintenance, machinery coating, marine applications, and renovation projects. Specialty formulations may command stronger margins where users value reduced rework, predictable drying, and compatibility with advanced coating systems. Research programs should focus on solvent combinations that reduce undesirable emissions while retaining the performance demanded by professional applicators. Commercial teams can reinforce differentiation through technical service, application testing, digital formulation guidance, and documented safety information. This strategy can strengthen customer relationships and create recurring demand in markets where regulatory changes progressively favor technically optimized alternatives.
Recent Developments
- March 2025: Sirca Paints India Limited — Sirca Paints acquired the entire business under the Wembley brand from Wembley Paints & Chemicals and Indo Wembley Paints Private Limited. The acquired portfolio includes thinners, wall paints, enamels, nitrocellulose, melamine, and other coatings, strengthening Sirca’s presence across wood coatings and related solvent-based products.
- September 2025: JSW Paints Limited — The Competition Commission of India approved JSW Paints’ acquisition of up to 75% of Akzo Nobel India Limited. The transaction expands JSW Paints’ decorative and industrial coatings platform and provides greater access to established product portfolios and distribution capabilities in India.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for