
Social Media Management Tools Market Size, Trends & Growth by 2034
Coverage: By Component (Solution, Service); Deployment (Cloud-based, On-premises); Organization Size (Large Enterprise, SMEs); Verticals (BFSI, Retail and eCommerce, Healthcare and Life Sciences, Government and Public Sector, Telecom and IT, Media and Entertainment, Others) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00021423
- Category : Technology, Media and Telecommunications
- No. of Pages : 150
- Available Report Formats :


- Last update date : August 06, 2026


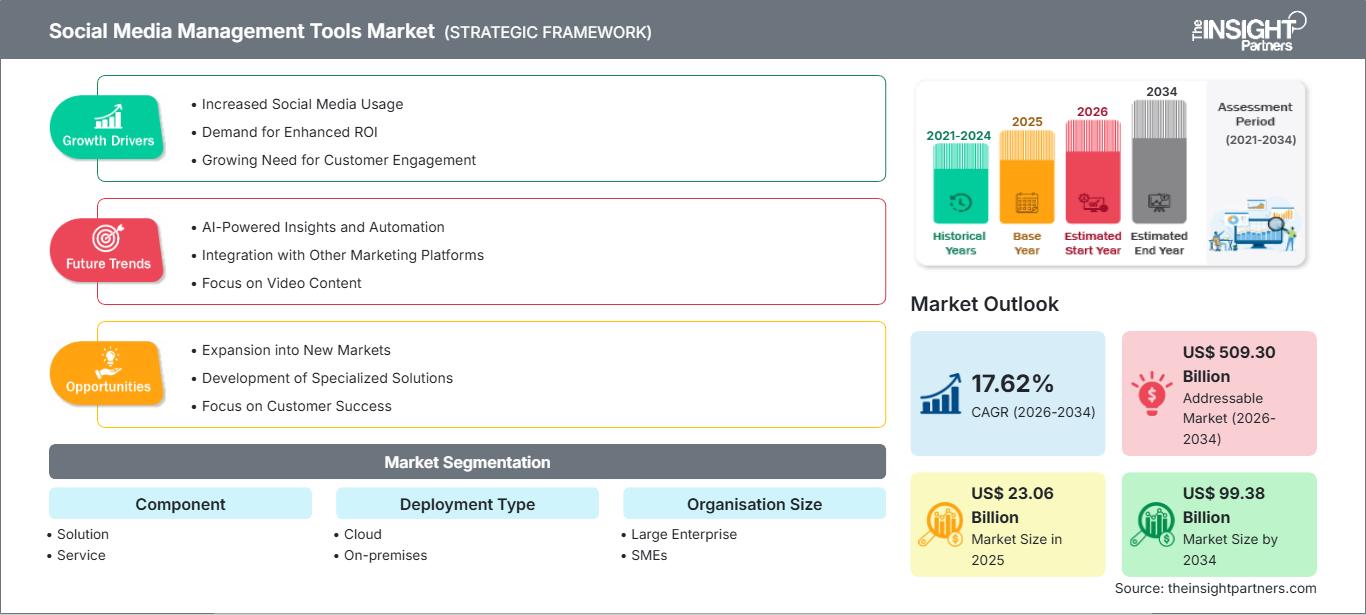
2025 Market Size
US$ 23.06 Bn
Base year value
2034 Forecast
US$ 99.38 Bn
Projected by 2034
CAGR 2026-2034
17.62 %
Growth rate
Addressable Market
US$ 509.30 Bn
(2026-2034)
The social media management tools market was valued at US$ 23.06 Billion in 2025 is projected to reach US$ 99.38 Billion by 2034, expanding at a CAGR of 17.62% between 2026 and 2034 as enterprises consolidate publishing, listening, and customer engagement into unified platforms.
North America is estimated to grow at a CAGR in the range of 16-18% through 2034, propelled by a dense concentration of enterprise marketing technology budgets and early adoption of AI-native social intelligence tools. Large retail, media, and financial services brands headquartered across the region continue to expand social investment as customer engagement increasingly shifts toward always-on, multi-channel conversation management.
Social Media Management Tools Market Assessment and Insights
- North America: Captured an estimated 36-40% share of the market in 2025 and is projected to expand at a CAGR between 16-18% from 2026 to 2034, supported by dense enterprise martech spending, deep agency ecosystem presence, and early AI adoption across major consumer brands.
- US: Accounted for roughly 82-86% of the North America market in 2025 and is expected to grow at a CAGR between 16-18% through 2034, driven by concentrated retail, media, and financial services demand.
- Europe: Held an estimated 24-28% share in 2025 and is projected to grow at a CAGR of 17-19% between 2026 and 2034, with the United Kingdom and Germany leading regional demand as brands modernize customer engagement under stricter data privacy frameworks.
- Asia Pacific: Captured an estimated 22-26% share in 2025 and is expected to expand at the fastest regional CAGR of 20-22% between 2026 and 2034, led by China and India as e-commerce and digital-first brands scale social commerce investment.
- Largest Segment: Cloud deployment held an estimated 74-78% share of the market in 2025 and is projected to grow at a CAGR of 18-20% through 2034, reflecting enterprise preference for elastic, subscription-based platforms.
- High Growth Segment: SMEs held an estimated 38-42% share in 2025 and are projected to expand at the fastest CAGR of 20-22% through 2034, as small businesses adopt affordable, AI-assisted publishing and listening tools.
- Key companies analyzed in detail: IBM Corporation, Oracle Corporation, Salesforce, Inc., Adobe Inc., Hootsuite Inc., Sprout Social, Inc., Google LLC, Sysomos, Sprinklr, Inc., and Digimind.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The social media management tools market has evolved from simple scheduling and publishing dashboards into comprehensive platforms spanning listening, customer care, analytics, and increasingly, agentic AI automation. Early solutions focused narrowly on cross-network post scheduling for marketing teams, while growing channel fragmentation and rising customer expectations for real-time response pushed vendors to integrate inbox management, sentiment analysis, and workflow automation. Production dynamics have shifted toward continuous, cloud-delivered feature releases as vendors compete on the pace of AI capability rollout rather than static annual upgrade cycles alone.
Looking ahead, social media management tools market growth will increasingly draw from emerging retail and financial hubs in Southeast Asia, Latin America, and the Gulf region, where digital-native consumer bases are expanding rapidly. Private equity and strategic investment activity continue to consolidate listening, digital asset management, and customer experience point solutions into unified platforms, while data privacy regulation across Europe and the Asia Pacific is prompting vendors to expand regional hosting and governance capabilities.
Social Media Management Tools Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 23.06 Billion |
| Market Size by 2034 | US$ 99.38 Billion |
| Global CAGR (2026 - 2034) | 17.62% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Social Media Management Tools Market Analysis
Enterprise demand for market solutions is intensifying as brands treat social channels as primary customer service and revenue touchpoints rather than purely promotional outlets, contributing to the growth of the Social Media Management Tools Market size. Unified visibility into publishing effectiveness, audience sentiment analysis, and response times is becoming more and more necessary for marketing, CX, and commerce teams, a requirement that is not met by disparate point products. Increasing channel proliferation, short video formats, and new community platforms are further driving the need for centralized management infrastructure within larger organizations.
The ecosystem of this market includes platform vendors, digital asset management vendors, and increasingly an AI model layer integrating generative capabilities into the content production, moderation, and reporting processes. On the supply side, the winners are platform vendors that provide open integration frameworks, as corporations are building toolchains that link social platforms to their CRM, commerce, and digital asset management solutions and not just using scheduling products.
Competitive intensity within the social media management tools market analysis reflects a split between customer-experience platform giants and specialist social vendors. Salesforce, Inc., Oracle Corporation, and Adobe Inc. leverage existing marketing cloud relationships to cross-sell social capabilities into large enterprise accounts, while Sprinklr, Inc., Hootsuite Inc., and Sprout Social, Inc. compete on purpose-built social intelligence depth and agentic AI innovation. Relevance at IBM Corporation, Google LLC, Sysomos, and Digimind is maintained via data, listening, and analytics focus for buyers with regulatory and research intensity requirements.
Investment has been particularly intense within the competitive set in terms of agent-based AI, where creator, organic, and paid social data are brought together along with voice-of-customer intelligence. Positioning will become more reliant on platform scope going forward, with vendors like Sprinklr, Inc. and Sprout Social, Inc. rushing to incorporate autonomous conversational AI agents to their publishing, listening, and service capabilities.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Social Media Management Tools Market: Strategic Insights
Regional Insights
North America Social Media Management Tools Market
North America remains the largest contributor to the global social media management tools market, supported by a dense concentration of enterprise marketing technology spending, deep agency ecosystem presence, and headquarters proximity to leading platform vendors. The region benefits from early institutional adoption of AI-native social intelligence capabilities, with large retail, financial services, and media brands treating unified social platforms as core infrastructure for customer engagement rather than a discretionary marketing tool.
Structural growth drivers include accelerating enterprise AI adoption within publishing and listening workflows, continued consolidation of point tools into unified customer experience platforms, and rising demand from regulated industries for auditable, governance-ready social management. The social media management tools market share held by North America is expected to remain substantial through the forecast period, with the region projected to expand at a CAGR between 16-18% from 2026 to 2034, driven by sustained mid-market expansion.
U.S. Social Media Management Tools Market
The United States dominates the North America social media management tools market, accounting for an estimated 82-86% regional share in 2025, reflecting concentrated enterprise marketing spend and the domestic headquarters presence of leading vendors, including Salesforce, Inc., Sprinklr, Inc., and Sprout Social, Inc. These areas of retail, media and entertainment, and financial services companies constitute the most developed adoption pool, where large firms are moving towards unified solutions for all publishing, listening, and customer care capabilities.
Trends of applications within the US market include large-scale enterprise implementation of social analytics integrated with customer experience and commerce platforms, but with cloud solutions becoming increasingly popular among small and medium businesses. The country is expected to grow at a CAGR between 16–18% through 2034, supported by continued vendor R&D investment, deep systems-integrator presence, and early access to AI-enabled social intelligence capabilities, according to the Social Media Management Tools Market report.
Europe Social Media Management Tools Market
Europe held an estimated 24-28% share of the social media management tools market in 2025, with adoption concentrated among retail, financial services, and media enterprises pursuing coordinated digital customer engagement strategies. The regional demand is driven by data residency regulations of GDPR, leading to an increasing number of vendors offering European hosting capabilities as well as initiatives for public sector digital communication within the region that provide for social listening and citizen engagement capabilities development. The region is estimated to experience a CAGR of 17-19% from 2026 through 2034.
The United Kingdom represents the largest regional market demand due to the concentration of media, retail, and financial services verticals, as well as agencies that provide for enterprise-scale adoption. Germany ranks second in terms of the demand being driven by manufacturing and retail verticals' adoption of social customer service practices. France, Italy, and Spain offer a steadily growing set of mid-sized market adopters, including public sector digital communication initiatives in France and growing retail and tourism in Italy and Spain.
APAC Social Media Management Tools Market
Asia Pacific held an estimated 22-26% share of the social media management tools market in 2025 and is projected to expand at the fastest regional CAGR of 20-22% between 2026 and 2034. China dominates in terms of regional demand on account of the presence of large numbers of domestic e-commerce players and social commerce players. Demand from Japan and South Korea derives from the consistent efforts of retailers and electronic firms to engage in uniform customer interaction.
Amongst the countries in this region, India is the country that has the highest rate of growth in terms of demand due to the growing number of digital brands and agencies in this country, and Australia sustains the demand due to digitization in retail and financial services.
Middle East & Africa Social Media Management Tools Market
The Middle East & Africa region represented a smaller but steadily expanding share of the social media management tools market in 2025, projected to grow at a CAGR between 18-20% through 2034. Saudi Arabia is at the forefront of regional demand for the product, aided by domestic digital transformation strategies, as well as initiatives geared towards modernizing the retail and tourism sectors, which now include integrated social management techniques within their marketing strategies.
Close behind is the United Arab Emirates, where there is a high concentration of media, retail, and financial services industries, along with digital government and smart city communications initiatives. South Africa and the rest of MEA add incremental demand for the region, with enterprises in the banking and telecommunications industries slowly adopting social management practices.
Segmentation Analysis
Component
The Component segment is projected to grow at a CAGR between 17–19% from 2026 to 2034, reflecting key Social Media Management Tools Market trends. Solution offerings dominate enterprise spending as organizations prioritize core publishing, listening, and analytics platforms, while Service revenue is expanding steadily as enterprises seek implementation, training, and managed support to operationalize increasingly complex AI-native platform capabilities across large, distributed marketing and customer experience teams.
- Solution: Represents the core platform investment for enterprises, spanning publishing, listening, analytics, and customer engagement functionality deployed across marketing and service teams.
- Service: Encompasses implementation, integration, training, and managed support offerings that help enterprises operationalize platform capabilities and sustain adoption across distributed teams.
Deployment Type
The Deployment Type segment is projected to grow at a CAGR between 18-20% from 2026 to 2034. Cloud deployment dominates enterprise purchasing as organizations favor subscription-based infrastructure offering continuous feature delivery, while On-premises deployment persists among a narrower base of regulated enterprises with strict data control requirements, reflecting the broader scope of the social media management tools market shifting decisively toward cloud infrastructure.
- Cloud: Preferred by fast-scaling enterprises seeking rapid deployment, continuous AI feature updates, and reduced internal infrastructure ownership across distributed marketing teams.
- On-premises: Retained primarily by regulated financial institutions and government agencies requiring strict data sovereignty and internal infrastructure control.
Organisation Size
The Organization Size segment is projected to grow at a CAGR of 20-22% from 2026 to 2034. SMEs represent the fastest-growing buyer group as affordable, AI-assisted platforms lower the barrier to entry for smaller marketing teams, while Large Enterprise organizations continue to anchor overall market revenue through complex, multi-brand deployments requiring deeper governance and integration capabilities.
- Large Enterprise: Deploys platforms across multi-brand portfolios requiring centralized governance, advanced analytics, and integration with broader customer experience and commerce systems.
- SMEs: Adopts streamlined, cost-effective platforms prioritizing ease of setup, core publishing and listening functionality, and rapid onboarding without dedicated administrative resources.
Verticals
The Verticals segment is projected to grow at a CAGR between 19-21% from 2026 to 2034. Retail and eCommerce brands lead vertical adoption as social channels increasingly double as commerce and customer service touchpoints, while BFSI and Media and Entertainment organizations sustain steady demand as regulated engagement and audience intelligence needs continue to expand across enterprise marketing and communications functions.
- BFSI: Uses social platforms for regulated customer communication, brand monitoring, and compliance-auditable engagement across banking, insurance, and financial advisory functions.
- Retail and eCommerce: Relies on social platforms for social commerce, customer service, and influencer-driven campaign management across high-volume consumer engagement channels.
- Healthcare and Life Sciences: Applies social platforms for patient education, brand reputation monitoring, and compliant public health communication across regulated healthcare organizations.
- Government and Public Sector: Uses social platforms for citizen engagement, public communication, and crisis response coordination across municipal and national government agencies.
- Telecom and IT: Deploys social platforms for customer support, service outage communication, and technical community engagement across telecom and technology enterprises.
- Media and Entertainment: Relies on social platforms for content distribution, audience engagement, and real-time fan interaction across broadcast, streaming, and publishing organizations.
Opportunity Snapshot
| Industry Vertical | Revenue Contribution | Trend Tag | Adoption Stage |
| BFSI | Medium | Compliance Monitoring | Scaling |
| Retail and eCommerce | High | Social Commerce | Mature |
| Healthcare and Life Sciences | Low | Patient Engagement | Emerging |
| Government and Public Sector | Medium | Citizen Engagement | Scaling |
| Telecom and IT | Medium | Service Outage Alerts | Scaling |
| Media and Entertainment | High | Fan Interaction | Mature |
Social Media Management Tools Market Growth Drivers and Impact Analysis
Consolidation of Marketing and Customer Service Functions on Social
Social channels have changed their role from being merely promotional channels to becoming the major source of customer support interactions. This has resulted in the necessity of combining marketing and support services onto the same platform, leading to an extension of the buyer pool for social media management software from marketing heads to chief customer officers and service operations looking to unify responses on various channels. Software vendors have incorporated case management, sentiment routing, and service level tracking capabilities within publishing and listening dashboards, which were solely developed for marketers until recently. This development has significantly increased the size of the average deal size, moving from a single department license for marketing to a company-wide license of platforms across service, commerce, and communication functions.
Agentic AI Reducing Manual Content and Response Workloads
AI-based generative and agentic functions incorporated into the core structure of social media platforms are decreasing the effort required to be invested in drafting of content, moderating comments and generating reports on the performance. As enterprises seek vendors who provide deep AI agents with the ability to autonomously resolve responses and generate insights across channels, not simply schedule activities, the manual labor associated with those processes is being reduced. In this way, enterprises are willing to spend more to get premium tiers that will provide AI capabilities, increasing the average revenue per user through the forecast period. The key vendors, such as Sprinklr, Inc. and Sprout Social, Inc. have been working hard on the integration of agentic AI into their workflow.
Regulatory Pressure Driving Governance-Grade Platform Adoption
Enterprises operating in regulated industries such as banking, healthcare, and government increasingly require social platforms capable of supporting audit trails, approval workflows, and compliance reporting alongside core publishing and listening functionality. This requirement has elevated governance capability from a secondary consideration to a primary vendor selection criterion among large regulated enterprises, favoring established platform vendors with mature security certifications over newer entrants. Data residency requirements, particularly across Europe under GDPR and increasingly across Asia Pacific under national data protection frameworks, are prompting vendors to expand regional hosting infrastructure to remain viable for regulated enterprise procurement. This dynamic is reinforcing platform consolidation, as regulated enterprises favor vendors capable of demonstrating a consistent compliance posture across global deployments, directly benefiting scaled incumbents with established compliance engineering investment and dedicated regional data infrastructure.
Social Media Management Tools Market Future Trends
Convergence of Social Data With Enterprise Customer Intelligence
Social media management tools trends point toward growing convergence between social engagement data and broader enterprise customer intelligence systems, including commerce, service, and loyalty platforms. Vendors are increasingly building unified data models connecting social sentiment and engagement signals directly to customer profiles, enabling real-time visibility into how social interactions influence purchasing and retention behavior. This convergence is reducing the historical divide between marketing-owned social data and enterprise-owned customer relationship data, allowing organizations to personalize engagement based on unified signals rather than siloed channel-specific insights alone. Over the coming years, this trend is expected to reshape enterprise procurement patterns, favoring vendors capable of spanning both social engagement and broader customer intelligence layers within a single connected platform.
Rise of Autonomous Social Agents Managing Full Engagement Cycles
As enterprises scale AI adoption, social platforms are beginning to deploy autonomous agents capable of managing entire engagement cycles, from content drafting through response resolution, with human oversight reserved for exception handling. This emerging capability allows enterprise leaders to reallocate marketing and service headcount toward strategic planning while autonomous agents handle high-volume, routine interactions across channels. Over the next several years, this trend is expected to become a standard platform capability rather than a differentiated feature, as enterprises scale agentic automation across social operations, requiring platforms to evolve governance frameworks that keep every autonomous action traceable to accountable human decision-makers within enterprise compliance structures.
Social Media Management Tools Market Opportunities
Mid-Market Expansion Through Simplified, AI-Guided Onboarding
A substantial social media management tools market forecast opportunity exists among small and mid-sized organizations that have historically avoided enterprise-grade platforms due to configuration complexity and cost. Vendors that invest in AI-guided onboarding, pre-built content templates, and simplified administrative interfaces stand to capture this underpenetrated segment, which represents a meaningfully larger population of organizations than the large-enterprise accounts most vendors have historically targeted. Reduced implementation timelines lower the total cost of adoption for smaller buyers, directly expanding the addressable customer base. Vendors pursuing this opportunity should prioritize usage-based pricing models and self-service trial experiences over traditional enterprise sales-led motions, enabling faster customer acquisition velocity. Early movers capturing this segment now stand to benefit from long-term account expansion as these organizations scale headcount and marketing sophistication, reinforcing durable recurring revenue growth over time.
Vertical-Specific Compliance Modules for Regulated Industries
A significant investment opportunity exists in developing vertical-specific compliance modules tailored to the approval workflows, terminology, and regulatory requirements of industries including banking, healthcare, and government. Rather than offering generalized publishing and listening functionality requiring extensive customization, vendors that pre-build industry-specific templates, compliance reporting modules, and integration connectors for sector-specific systems can meaningfully reduce enterprise sales cycles and implementation risk. This approach allows vendors to command premium pricing relative to horizontal offerings while building defensible competitive moats through deep vertical domain expertise that generalist competitors cannot easily replicate. Enterprises within regulated sectors have consistently demonstrated a willingness to pay higher licensing rates for platforms that reduce internal compliance engineering burden, making this an economically attractive avenue for vendors seeking higher-margin regulated industry accounts.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for