
Structured Cabling Market Size, Share & Trends by 2034
Coverage: By Component (Hardware and Software & Service), Network Type (Local Area Network and Wide Area Network), Cable Type (5E, 6, 6A, and Others), and End Use (Government & Defense, Healthcare, IT & Telecom, Manufacturing, Residential & Commercial Buildings, Transportation, and Others)
- Status : Data Released
- Report Code : TIPRE00002789
- Category : Electronics and Semiconductor
- No. of Pages : 150
- Available Report Formats :


- Last update date : October 16, 2026


2025 Market Size
US$ 14.53 Bn
Base year value
2034 Forecast
US$ 26.84 Bn
Projected by 2034
CAGR 2026-2034
7.06 %
Growth rate
Addressable Market
US$ 186.79 Bn
(2026-2034)
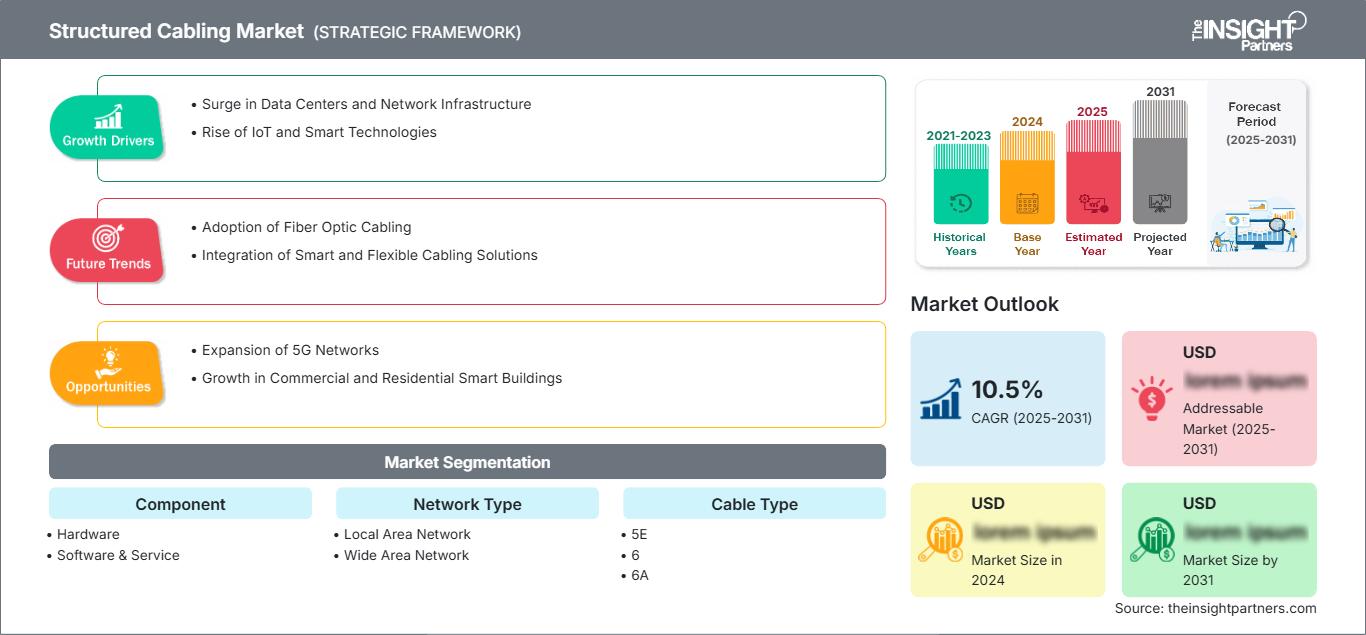
The Structured Cabling Market is valued at US$ 14.53 Billion in 2025 and is projected to reach US$ 26.84 Billion by 2034, registering a CAGR of 7.06% from 2026 to 2034. The market covers hardware, software, and services supporting organized network infrastructure across local and wide area networks. Demand is shaped by data center expansion, enterprise digitization, higher bandwidth requirements, smart-building deployments, and modernization of legacy communication infrastructure across diverse end-use environments.
North America remains a strategically important market because of established enterprise networks, hyperscale data center construction, cloud infrastructure expansion, and continued investment in high-speed connectivity. The region is expected to register a ~6% CAGR through 2034. Demand is also supported by network upgrades in government facilities, healthcare institutions, manufacturing sites, and commercial buildings, where higher-density connectivity and scalable cable management are increasingly important.
Structured Cabling Market Assessment and Insights
Regional Outlook
- North America: ~31% of the global Structured Cabling Market share in 2025 | ~6% CAGR through 2034. Market position: North America maintains the largest regional position, supported by mature enterprise infrastructure, hyperscale and colocation data centers, cloud adoption, and replacement of legacy cabling with higher-performance architectures across commercial and institutional facilities.
- US: ~80% of North American market revenue in 2025 | ~6% CAGR through 2034. Market position: The US is the leading country in North America, supported by concentrated data center investment, large technology ecosystems, federal connectivity programs, enterprise modernization, and demand for high-density cabling across cloud, healthcare, defense, and commercial applications.
- Europe: ~25% of the global market in 2025 | ~6% CAGR through 2034. Market position: Europe represents a mature infrastructure market, with Germany as the leading country in Europe. The UK, France, Italy, and Spain contribute through data center construction, industrial digitization, smart buildings, and network modernization.
- Asia Pacific: ~34% of the global market in 2025 | ~8% CAGR through 2034. Market position: Asia Pacific is the fastest-growing region, supported by large-scale digital infrastructure investment, manufacturing expansion, cloud and data center development, and accelerating enterprise connectivity across China, Japan, South Korea, India, and Australia.
Segment Outlook
- Network Type: ~75% Share in 2025 | ~7% CAGR through 2034. Market position: Local Area Network represents the dominant network architecture because structured cabling is extensively deployed within offices, campuses, industrial facilities, institutions, and data centers, where predictable performance, centralized management, and scalable connectivity are essential.
- Cable Type: ~27% Share in 2025 | ~8% CAGR through 2034. Market position: Category 6A is the high-growth cable category as organizations seek higher bandwidth, improved support for 10GBASE-T, greater PoE capability, and infrastructure that can accommodate future network upgrades without extensive pathway replacement.
Competitive Coverage
ABB Ltd, Belden Inc., CommScope Holding Company, Inc., Corning Incorporated, Furukawa Electric Co., Ltd., Legrand SA, Nexans, Schneider Electric SE, The Siemon Company, Panduit Corporation, Siemens AG, TE Connectivity plc
Methodology
The Insight Partners follows Data Collection & Secondary Research, Primary Research, Data Analysis, and Data Triangulation & Final Review to validate market estimates and insights.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The Structured Cabling Market has transitioned from standard copper enterprise installations to advanced dense standards-compliant architecture incorporating copper, fiber, connectivity components, management tools, and deployment services. Growing demand for faster Ethernet, Power over Ethernet, virtualization, cloud computing, industrial networking, and dense wireless access point deployments has impacted cable types and pathway needs. Category 6A has become a strategically important type of cable for high-bandwidth enterprise applications, while fiber is becoming common in backbone and data center applications. Suppliers are incorporating pre-terminated solutions, higher-density connectivity, better cable management, and efficient installation designs into their products.
The future of the Structured Cabling Market is shaped by infrastructure for AI, edge computing, smart buildings, and digital industrial plants. New markets in the Asia Pacific are growing capacity along with their data centers and manufacturing investments, while developed markets are concentrating on replacing, densifying, energy saving, and retrofit projects. Regulatory requirements on fire safety, materials performance, building efficiency, and network standards are driving specification-driven procurements. The capital spending will move towards infrastructure that enables denser ports, easy installation, operational visibility, and longer service life.
Structured Cabling Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 14.53 Billion |
| Market Size by 2034 | US$ 26.84 Billion |
| Global CAGR (2026 - 2034) | 7.06% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Structured Cabling Market Analysis
Growth of the Structured Cabling Market is directly associated with the growth of the number of connected devices, enterprise networks, data centers, industrial Ethernet, and digitally-enabled buildings. Customer demand comes from enterprises, data centers, telecommunication companies, governments, manufacturers, healthcare providers, and building developers. Requirements turn into structured cabling solutions involving cable pathways, racks, patch panels, connectors, terminations, testing, and documentation. In this way, a whole ecosystem is created involving cooperation between cable manufacturers and connectivity providers, distributors, contractors, engineering companies, and network equipment providers.
Supply factors in the Structured Cabling Market increasingly favor the suppliers that can offer integrated infrastructure solutions, not separate cables. Such factors as copper/fiber availability, compatibility of the connectors, production capacity, certifications, installer networks, and lead time for large projects become important in purchasing decision-making. Larger projects will need standardization on multiple facilities, which makes supply chains and technical support an increasingly important factor. Higher density architecture implies closer collaboration between suppliers regarding cabling, connectivity, routing, and management.
According to the analysis of the Structured Cabling Market, it is evident that there exists an intense competitive landscape of diversified electrical and networking firms and also the connectivity providers. The firms such as Belden, CommScope, Corning, Panduit and Siemon have high exposure to networking infrastructures, whereas ABB, Legrand, Schneider Electric and Siemens possess diversified range of electrical, building and automation infrastructures. Furukawa Electric and Nexans manufacture cable and connectivity in multiple infrastructures market, while TE Connectivity has got huge expertise in interconnections.
There is increasing trend in the Structured Cabling Market in terms of bandwidth readiness, installation efficiencies, density, interoperability, sustainability and lifecycle performance. Capital investment in manufacturing capacities, high density fiber connectivity, data center products and integrated infrastructures are on the rise. Strategic positioning would depend upon distribution channels and ability to service system designers, contractors and end-users. Diversified firms would be able to serve more phases of projects than specialized firms.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Structured Cabling Market: Strategic Insights
Regional Insights
North America Structured Cabling Market
North America accounted for ~31% of the global market in 2025 and is projected to expand at a ~6% CAGR through 2034. This region has a strong base of installed network infrastructure along with continuous investments in data centers, cloud computing centers, enterprise campuses, health care centers, government buildings, and manufacturing centers. US is the main consumer region, while Canada is involved through investments in data centers, telecommunication infrastructure, and commercial building upgrades.
The established installed base of the region ensures that there are always replacement and upgrade opportunities along with the construction opportunities. Higher speed Ethernet, Category 6A cabling, fiber backbones, and wireless deployment increases the demand for upgraded paths and connection systems. AI-enabled data center constructions add to the demand due to the fact that higher server density increases the demand for better cable routings and fiber optic connections.
U.S. Structured Cabling Market
The US represented ~80% of North American market revenue in 2025 and is expected to register a ~6% CAGR through 2034. The country’s robust technology industry, broad enterprise installed base, density of data centers, and ongoing investments in digital infrastructure ensure consistent demand. Government, state, institution, and private-sector projects provide opportunities in communications rooms, campuses, public buildings, and commercial properties alike.
Network upgrades are now linked to increased bandwidths, PoE-powered devices, Wi-Fi infrastructures, cloud migration, and AI computing. Some of the suppliers serving these segments include CommScope, Belden, Corning, Panduit, and Siemon. The growth in demand is also happening in the healthcare and manufacturing industries, wherein reliable connectivity is needed for the operation of connected medical equipment, automation, industrial Ethernet, monitoring, and other operational systems.
Europe Structured Cabling Market
Europe represented ~25% of the global market in 2025 and is expected to grow at a ~6% CAGR through 2034. Germany is the leading country in Europe, supported by its industrial base, automation ecosystem, enterprise infrastructure, and data center investment. The UK remains an important connectivity market because of its concentration of technology companies, cloud facilities, financial institutions, and commercial properties. France is supported by digital infrastructure projects and enterprise modernization, while Italy and Spain are expanding network infrastructure through commercial, industrial, public-sector, and data center investments.
The market is made up of a combination of new construction and retrofit projects. The digitization of industries drives the need for strong Ethernet networks in manufacturing settings, while office renovations and the development of smart buildings drives connectivity. Factors such as fire safety regulations, low smoke cables, energy efficiency, and sustainable product considerations affect product choice.
The close location of European suppliers to large-scale construction and infrastructure projects is an added advantage. Legrand, Nexans, Schneider Electric, and Siemens offer expertise in electrical and building infrastructure solutions, while dedicated network equipment suppliers drive high-speed connectivity needs. The established network systems in the region create replacement opportunities, while data centers and automation drive additional growth.
APAC Structured Cabling Market
APAC represented ~34% of the global market in 2025 and is expected to expand at a ~8% CAGR through 2034, making it the fastest-growing region. China stands out as the leading nation in Asia Pacific owing to large-scale manufacturing capabilities, investments in data centers, telecommunication sector, and enterprise infrastructure needs. Japan and South Korea make their contributions in terms of electronics, industrial automation, and technology-intensive infrastructures.
India is growing with investments in data centers, enterprise digitization, smart infrastructures, and construction sectors, while Australia is growing with cloud computing initiatives, governmental projects, educational sector, and data centers. Growth in the region occurs due to new infrastructure build-out coupled with rising demands for connectivity in existing infrastructures.
Middle East & Africa Structured Cabling Market
Middle East and Africa is expected to register a ~7% CAGR through 2034. Saudi Arabia is the leading country in the Middle East and Africa region where large-scale infrastructure development, digital transformation programs, data center projects, commercial construction, and smart-city initiatives are creating demand for organized connectivity. The UAE is another important market because of its concentration of data centers, technology infrastructure, commercial developments, and international enterprises.
South Africa remains an important African market for enterprise networking, telecommunications, financial services, healthcare, and public infrastructure. Across the Rest of MEA, structured cabling adoption is associated with new construction and phased modernization rather than large-scale replacement cycles. Energy infrastructure, government digitization, tourism developments, and connected commercial facilities provide additional demand. Project specifications increasingly emphasize reliability, scalability, fire performance, and installation quality.
Segmentation Analysis
Component
The Component segment is projected to grow at a ~7% CAGR from 2026 to 2034. Hardware remains central because physical infrastructure includes cables, connectors, patch panels, racks, cabinets, and cable-management elements required for complete installations. Software and services complement the physical layer through network documentation, management, testing, design, and installation support. Increasing project complexity is encouraging buyers to evaluate complete infrastructure packages rather than individual components.
- Hardware: Hardware represents the physical foundation of structured installations and includes connectivity, cabling, patching, racks, and management products. Demand is closely linked to new network deployments, replacement cycles, data center densification, and enterprise infrastructure upgrades.
- Software & Service: Software and service offerings support design, documentation, testing, installation, maintenance, and infrastructure management. Their strategic importance increases as large deployments require consistent configuration, traceability, and lifecycle oversight.
Network Type
The Network Type segment is expected to register a ~7% CAGR through 2034. Local Area Network deployments account for the largest demand because structured cabling is fundamental to office, campus, industrial, healthcare, educational, and data center environments. Wide Area Network requirements extend connectivity between geographically separated sites and complement local infrastructure, particularly where enterprises operate distributed facilities.
- Local Area Network: LAN infrastructure remains the principal structured deployment environment, connecting users, access points, servers, switches, devices, and building systems. Its importance rises with higher port density, PoE adoption, cloud access, and increasing wireless infrastructure.
- Wide Area Network: WAN applications connect geographically distributed facilities and require reliable backbone connectivity. Structured components support aggregation and site-level infrastructure, particularly for enterprises, government organizations, telecommunications operators, and distributed industrial operations.
Cable Type
The Cable Type segment is projected to expand at a ~8% CAGR through 2034. Category 6A is gaining importance as organizations require higher bandwidth and greater readiness for 10-gigabit Ethernet and PoE-intensive deployments. Category 6 continues to serve a broad installed base, while Category 5E remains relevant in cost-sensitive and legacy environments where network requirements are less demanding.
- 5E: Category 5E remains relevant for legacy networks, basic enterprise connectivity, residential applications, and cost-sensitive deployments. Its installed base supports replacement demand, although higher-performance requirements increasingly encourage upgrades to newer categories.
- 6: Category 6 provides a widely deployed balance between performance, cost, and installation practicality. It remains important for enterprise networks, commercial buildings, education facilities, and applications that require more capacity than legacy Category 5E infrastructure.
- 6A: Category 6A is strategically important for higher-bandwidth networks, 10GBASE-T, dense wireless environments, and PoE applications. Its ability to support higher performance over standard structured-cabling distances strengthens its role in new-build and upgrade projects.
End Use
The End Use segment is expected to expand at a ~8% CAGR through 2034. IT and Telecom demand is supported by data center, cloud, and network modernization, while manufacturing requires reliable industrial connectivity. Healthcare, government and defense, transportation, and residential and commercial buildings create diversified demand through specialized infrastructure requirements and new digital applications.
- Government & Defense: Government and defense facilities require secure, reliable, and highly organized communication infrastructure. Structured cabling supports resilient network rooms, command facilities, surveillance, access control, and connected administrative environments.
- Healthcare: Healthcare organizations increasingly require dependable connectivity for digital records, medical equipment, imaging, communications, and connected building systems. Cabling upgrades support network reliability while accommodating expanding device density.
- IT & Telecom: IT and telecom represents a major demand center because data centers, enterprise networks, cloud facilities, and communications infrastructure require scalable physical connectivity. Higher-speed networking and AI workloads strengthen demand for dense fiber and copper architectures.
- Manufacturing: Manufacturing facilities deploy structured cabling for industrial Ethernet, automation, machine connectivity, monitoring, and enterprise-to-plant integration. Reliable infrastructure is important for minimizing disruption and supporting increasingly connected production environments.
- Residential & Commercial Buildings: Residential and commercial properties use structured infrastructure for broadband, Wi-Fi access points, surveillance, building automation, and connected devices. Smart-building adoption increases the value of centralized and upgradeable cabling.
- Transportation: Transportation facilities require connectivity across airports, rail systems, ports, stations, and logistics facilities. Cabling supports surveillance, passenger information, access control, communications, and operational technology networks.
Opportunity Snapshot
| End Use | Revenue Contribution | Trend Tag | Adoption Stage |
| Government & Defense | Medium | Secure Networks | Scaling |
| Healthcare | Medium | Digital Care | Scaling |
| IT & Telecom | High | AI Infrastructure | Mature |
| Manufacturing | High | Industrial Ethernet | Scaling |
| Residential & Commercial Buildings | High | Smart Buildings | Mature |
| Transportation | Medium | Connected Mobility | Scaling |
Structured Cabling Market Growth Drivers and Impact Analysis
Expansion of Data Centers and High-Density Digital Infrastructure
Data center expansion is increasing the amount and complexity of physical connectivity required inside facilities and between network zones. AI computing, cloud services, storage systems, and high-speed switching create greater port density and place stronger requirements on cable routing, fiber connectivity, patching, and thermal management. This changes procurement from basic cable replacement toward engineered infrastructure capable of accommodating frequent equipment changes. Data center operators increasingly value high-density connectors, pre-terminated assemblies, organized pathways, and scalable rack architectures because installation errors and congestion can affect deployment schedules. For suppliers, the shift expands the addressable opportunity for fiber systems, connectivity hardware, cable management, and professional services. It also raises the importance of interoperability and installation speed as operators seek to scale capacity while controlling construction complexity.
Rising Adoption of Power over Ethernet and Connected Building Systems
Power over Ethernet is expanding the role of structured cabling beyond conventional data transmission by allowing compatible devices to receive both connectivity and electrical power through network infrastructure. Wireless access points, surveillance cameras, access-control systems, sensors, lighting controls, and building automation devices can therefore increase cable density across commercial and institutional facilities. Higher-power PoE applications place greater emphasis on cable category, thermal performance, bundle design, and installation practices. This is creating demand for higher-performance copper systems, particularly where organizations want to deploy connected devices without extensive electrical rewiring. The resulting infrastructure model also supports smart-building strategies because network cabling becomes a common physical layer for multiple building functions. Vendors able to combine cabling, connectivity, management, and design guidance can address a broader portion of these deployments.
Enterprise Network Modernization and Industrial Digitization
Enterprises are upgrading physical networks as cloud migration, distributed computing, wireless access, industrial automation, and connected equipment increase data volumes and connectivity requirements. Older cabling can constrain network speeds or complicate support for newer applications, creating replacement opportunities even where building infrastructure remains operational. Manufacturing adds another dimension because industrial Ethernet connects machines, controllers, sensors, production systems, and enterprise networks. Structured architectures can simplify maintenance and facilitate standardized expansion across production areas. Healthcare and government organizations similarly require reliable infrastructure as connected devices and digital services expand. These applications favor suppliers with certified products, installation support, testing capabilities, and established distribution channels. Modernization therefore generates recurring demand through a combination of planned upgrades, capacity expansion, facility refurbishment, and application-driven replacement.
Structured Cabling Market Future Trends
AI-Optimized High-Density Fiber Architectures
AI computing is expected to accelerate the transition toward higher-density optical architectures within and around data centers. As computing clusters require faster links and more connections, physical infrastructure must accommodate greater fiber counts without creating excessive pathway congestion. Future deployments are likely to place greater emphasis on compact cable designs, higher-density connectors, pre-terminated systems, improved polarity management, and simplified routing. The Structured Cabling Market trends will increasingly reflect infrastructure designed around rapid deployment and future bandwidth expansion rather than static network requirements. This shift can also encourage closer integration between rack architecture, cable management, optical connectivity, and data center planning. Suppliers that reduce installation time and physical footprint while preserving upgrade flexibility will be positioned to address increasingly dense AI-oriented environments.
Convergence of Data Connectivity and Intelligent Infrastructure
The boundary between communication infrastructure and intelligent building infrastructure is becoming less distinct. Network-connected lighting, sensors, security devices, access controls, wireless systems, and automation platforms increasingly share physical connectivity requirements. Future structured architectures are therefore likely to emphasize common pathways, centralized management, standardized interfaces, and infrastructure that can support both present and emerging device categories. Sustainability considerations may further encourage solutions that reduce material use, installation waste, and future replacement requirements. Modular cabling, documentation platforms, and intelligent infrastructure management can help operators understand capacity and simplify moves, additions, and changes. This evolution increases the importance of lifecycle design, making physical network infrastructure a more strategic component of connected-building planning.
Structured Cabling Market Opportunities
Pre-Terminated and Modular Infrastructure for Faster Deployment
Growing project complexity and shortages of skilled installation labor create opportunities for pre-terminated and modular structured cabling systems. Factory-assembled trunks, connectors, patching modules, and standardized rack solutions can reduce field termination requirements and improve deployment consistency. This approach is particularly relevant to data centers, multi-site enterprises, and large commercial developments where installation schedules directly affect facility commissioning. Vendors can capture additional value by combining preconfigured hardware with design services, testing, documentation, and installation support. Modular architectures also support future changes because standardized components can simplify moves, additions, and upgrades. Investment opportunities therefore extend beyond cable manufacturing into configuration, logistics, quality assurance, and digital documentation. Suppliers that can shorten deployment cycles while maintaining standards compliance can address a clear operational requirement among large infrastructure buyers.
High-Performance Connectivity for Emerging Digital Infrastructure
AI data centers, edge facilities, industrial automation, and smart infrastructure create opportunities for higher-performance structured connectivity. Buyers increasingly need solutions that manage greater bandwidth, port density, fiber counts, and device concentration while preserving manageable installation footprints. Suppliers can target this opportunity through Category 6A systems, high-density fiber connectivity, advanced patching, compact cable designs, and application-specific management solutions. The Structured Cabling Market Forecasts will increasingly depend on how quickly emerging digital facilities move from pilot deployments toward standardized infrastructure programs. Companies can also expand through partnerships with data center designers, engineering firms, system integrators, and network equipment providers. Regional manufacturing and distribution capacity can further reduce lead times in fast-growing markets, particularly where data center and industrial investment is expanding rapidly.
Recent Developments
- September 2026: Corning Incorporated introduced and showcased new cable and connectivity innovations for AI network growth at ECOC 2026, including the Contour Form Micro Cable, multicore fiber solutions, and high-density optical connectivity designed to increase pathway density and simplify AI data center deployment.
- August 2025: Belden Inc. launched several connectivity and cybersecurity products for critical applications, including gel-free optical fiber cables and solutions supporting extended Ethernet reach. The portfolio targets automation and smart infrastructure requirements where reliable connectivity and simplified deployment are increasingly important.
- January 2026: Panduit Corporation launched its Gen 7 Connectivity Solution for Brocade Gen 7 SAN Directors, using VSFF SN connectors, Base-16 architecture, and a Jumbo Cassette to support high-density Fibre Channel deployments while simplifying installation and cable management.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners provided valuable market intelligence that supported our global go-to-market strategy. Their team was professional, responsive, and attentive to our feedback, providing thoughtful analysis and helpful methodological clarifications throughout the project.
Junmo Kim Chief Financial Officer (CFO), Enertech Co., Ltd.
The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for