
Antibody Production Service Market Size, Share & Forecast by 2034
Coverage: By Process (Upstream Processing, Downstream Processing, Filtration); End User (Pharmaceutical and Biotechnology Companies, Diagnostic Laboratories and Research Institutes) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00027319
- Category : Life Sciences
- No. of Pages : 150
- Available Report Formats :


- Last update date : August 21, 2026


2025 Market Size
US$ 6.57 Bn
Base year value
2034 Forecast
US$ 16.41 Bn
Projected by 2034
CAGR 2026-2034
12.12 %
Growth rate
Addressable Market
US$ 109.40 Bn
(2026-2034)
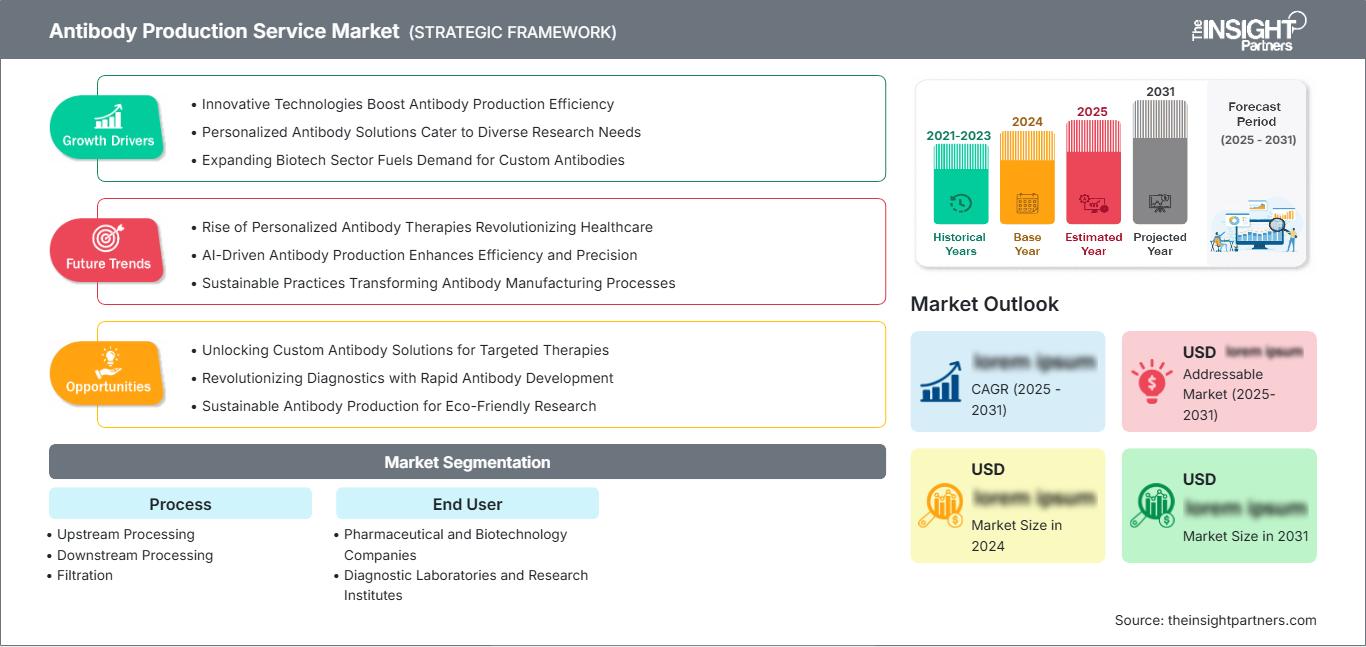
The antibody production service market size is growing since more biopharmaceutical developers opt for outsourcing manufacturing activities to gain access to scalable processes, validated facilities, and expertise. This market will be worth US$ 6.57 billion in 2025 and will rise to US$ 16.41 billion by 2034 at a CAGR of 12.12% for 2026-2034, thanks to growing pipelines of biologics, increasing need for flexible capacity, and adoption of outsourced upstream and downstream services.
North America is still an important outsourcing center as the size of the antibody production service market will be driven by well-developed biopharmaceutical manufacturing infrastructure, efficient CDMO industry, and numerous innovative drug developers operating in the region. The growth rate of this region's antibody production services market for 2026-2034 will be 11.5-12.5%.
Antibody Production Service Market Assessment and Insights
- North America: North America is estimated to represent a 39–43% antibody production service Market share in 2025 and grow at a 11.5–12.5% CAGR between 2026–2034, supported by mature biopharmaceutical infrastructure, outsourcing penetration, and expanding biologics manufacturing capacity.
- US: The US accounts for an estimated 31–35% share globally in 2025 and is projected to grow at a 11.7–12.7% CAGR during 2026–2034, led by established manufacturing networks.
- Europe: Europe holds approximately 27–31% share in 2025 and is expected to grow at a 10.8–11.8% CAGR during 2026–2034, with Germany, Switzerland, France, and the UK providing strong bioprocessing capabilities.
- Asia Pacific: Asia Pacific represents an estimated 20–24% share in 2025 and is forecast to expand at a 13.0–14.0% CAGR during 2026–2034, led by China, South Korea, Japan, India, and Singapore.
- Largest Segment: Downstream Processing holds an estimated 39–43% market share in 2025 and is expected to grow at a 11.5–12.5% CAGR, reflecting purification complexity and quality requirements.
- High Growth Segment: Filtration represents approximately 18–22% market share in 2025 and is projected to grow at a 12.5–13.5% CAGR as sterile processing and single-use workflows expand.
- Key companies analyzed in detail: GE HealthCare Technologies Inc., Thermo Fisher Scientific Inc., Sartorius AG, Merck KGaA, Pall Corporation, Sigma-Aldrich Corporation, Eppendorf AG, Cellab, INTEGRA Biosciences, Fiber Cell Systems.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The antibody production service market report indicates that the market has progressed from laboratory assistance into a business that involves bioprocessing partnerships in areas such as cell culture, process development, purification, filtration, analytical testing, and scale-up. Single-use bioreactors, intensified cultivation systems, automation, and advancements in chromatography workflows are impacting production economics. Today's production systems are becoming increasingly linked between upstream and downstream processes, thereby allowing service providers to assist in development from early stages into commercial manufacture.
In the future, the demand for services is likely to expand beyond biopharmaceutical industry hubs into new areas, namely in Asian Pacific countries and selected European locations. Providers who have regional plants, capability for technology transfer, and quality systems in place should find themselves well-placed to acquire outsourcing programs. Regulatory requirements for biologics manufacture include those from the WHO for monoclonal antibodies and associated products.
Antibody Production Service Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 6.57 Billion |
| Market Size by 2034 | US$ 16.41 Billion |
| Global CAGR (2026 - 2034) | 12.12% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Antibody Production Service Market Analysis
Factors influencing demand growth include the growing number of antibody pipelines, the rising complexity in manufacturing process, and the need to lower capital investments internally. In the antibody production service market, growth is thus tied with the trend of outsourcing within discovery, process development, clinical supply, and commercial manufacturing. The service companies integrate cell line development, upstream cultivation, harvest, clarification, purification, filtration, and analytical services, thereby forming an integrated value chain and not separate production processes.
Increasingly, the dynamics in the supply side work to favor those firms that have scalable equipment, process expertise, consumables, and technical services. Advancements in upstream productivity may lead to increased load of impurities in the downstream process, necessitating integration in the process. According to Sartorius, there is a need for integration between the upstream and downstream processes since high titer does not imply economical purification.
Competitive positioning is evolving in terms of workflow range, geographical footprint, process knowledge, and the ability to move the process into production without having to requalify. Thermo Fisher Scientific Inc. provides services for upstream, downstream, quality, and scale process operations, while Sartorius AG focuses on integrated monoclonal antibodies manufacturing processes. Similarly, Merck KGaA has broad capabilities in the areas of filtration, process solutions, and manufacturing technologies.
The competitive landscape is thus evolving in favor of platform solutions, regional manufacturing capabilities, and process intensification. Competitors such as GE HealthCare Technologies Inc., Eppendorf AG, Pall Corporation, Sigma-Aldrich Corporation, INTEGRA Biosciences, Cellab, and Fiber Cell Systems compete with various combinations of equipment, disposables, process technologies, and other specific services. More and more investments are being made in flexibility, single use technologies, digital process control, and purification processes.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Antibody Production Service Market: Strategic Insights
Regional Insights
North America antibody production service market
North America accounts for an estimated 39–43% share of the global market in 2025 and is expected to expand at an 11.5–12.5% CAGR through 2034. The US represents the dominant regional contributor because of its concentration of biotechnology companies, clinical-stage pipelines, specialized manufacturing facilities, and established outsourcing relationships. Canada complements the region through research institutions and growing biologics capabilities.
The area is aided by advanced cGMP facilities, good supplier networks, and ongoing investment into local pharmaceutical manufacturing operations. The recent US investments worth more than US$500 billion in key players in the industry clearly indicate the global trend towards manufacturing and supply chain security. This situation will create demand for expertise in antibody manufacturing, process development, purification, and filtration, especially where flexibility in capacity utilization is needed.
U.S. antibody production service Market
The US constitutes about 80-84% of North American markets for 2025 and is expected to witness growth at 11.7-12.7% CAGR during the period 2026-2034. The main strength of the country lies in its biopharmaceutical focus, regulatory structure, and presence of commercial manufacturing services. Leading players have their strong US presence in R&D, process development, bioprocessing, and manufacturing.
Application range is moving from traditional production of antibodies in laboratories to the clinical and commercial production where processes such as upstream processing, purification, filtration, analytics, and technology transfer become important. Thermo Fisher Scientific Inc. helps in the development and bioprocessing of antibodies using single use bioreactors and downstream solutions. Demand from the US is thus becoming more driven by outsourcing of process-related tasks rather than mere capacity constraints.
Europe antibody production service Market
Europe is estimated to hold a 27–31% share in 2025 and grow at a 10.8–11.8% CAGR through 2034. Germany is the leading market, supported by strong life-science manufacturing infrastructure, while Switzerland, France, the UK, Italy, and Spain contribute through research, pharmaceutical production, and specialized bioprocessing capabilities.
Outsourcing continues to be a critical part of the value chain for both the UK and Germany due to the presence of well-developed pharma ecosystems, experienced technical labor, and availability of research facilities. The key strength of Germany lies in the presence of an integrated manufacturing and development ecosystem. France adds value in the form of biopharmaceutical manufacturing facilities and suppliers, while Italy and Spain add strength to research and manufacturing ecosystem.
APAC antibody production service Market
The region is expected to hold 20%-24% market share in 2025 and register growth rate at 13.0-14.0% CAGR. China dominates the regional market in terms of demand, followed by Japan, South Korea, India, and Australia. In-country manufacturing, investments in biotech, and life science initiatives supported by governments have increased the capability of the region.
The bioprocessing capabilities of China and South Korea are becoming more advanced, and India has been increasing its research and manufacturing capabilities. Thermo Fisher Scientific Inc. runs Bioprocess Design Centers in India, China, Korea, and Singapore to provide upstream and downstream development services.
Middle East & Africa antibody production service Market
Middle East and Africa represent a smaller but developing opportunity, with demand concentrated in Saudi Arabia, the UAE, and South Africa. The region is expected to expand at a 10.0–11.0% CAGR through 2034, supported by healthcare localization, pharmaceutical investment, and laboratory infrastructure development.
Saudi Arabia leads regional momentum through healthcare and industrial diversification initiatives, while the UAE emphasizes advanced healthcare and life-science infrastructure. South Africa remains the principal research and diagnostics hub in Africa. Increasing investments in cold-chain systems, laboratory capacity, and pharmaceutical manufacturing should gradually improve the addressable outsourcing base.
Segmentation Analysis
Process
Process is expected to remain the central value driver, with a 12.0–13.0% CAGR during 2026–2034. Outsourcing increasingly spans multiple connected manufacturing stages because sponsors seek consistent process transfer, lower operational complexity, and access to specialized equipment. Integrated service models can reduce handoff risks between upstream culture, downstream purification, and filtration.
- Upstream Processing: Upstream services support cell expansion, media optimization, feeding strategies, and bioreactor operation. Demand is strengthened by the need for reproducible titers, scalable cell culture, and process intensification.
- Downstream Processing: Downstream processing represents the largest process component because antibody purification directly affects yield, purity, and manufacturing economics. Chromatography and impurity removal remain technically intensive activities.
- Filtration: Filtration supports clarification, virus removal, concentration, and sterile processing. Growing adoption of single-use systems and tighter contamination-control requirements increases demand for specialized filtration capabilities.
End User
End User demand is projected to increase at an 11.5–12.5% CAGR during 2026–2034. Outsourcing decisions differ by organization size, development stage, internal capacity, and regulatory requirements. Smaller biotechnology companies generally prioritize access to capabilities, while large pharmaceutical organizations use external providers to supplement internal networks.
- Pharmaceutical and Biotechnology Companies: These organizations constitute the primary customer base because they require scalable production, process development, and manufacturing flexibility across clinical and commercial programs.
- Diagnostic Laboratories and Research Institutes: Research organizations use specialized production and processing capabilities when internal infrastructure is insufficient for reproducible antibody generation, purification, or experimental scale-up.
Opportunity Snapshot
| Segment Name | Revenue Contribution (High/Medium/Low) | Trend Tag | Adoption Stage |
|---|---|---|---|
| Pharmaceutical and Biotechnology Companies | High | Pipeline Outsourcing | Mature |
| Diagnostic Laboratories and Research Institutes | Medium | Custom Processing | Scaling |
Antibody Production Service Market Growth Drivers and Impact Analysis
Expanding Biologics Pipelines Increase Outsourced Manufacturing Requirements
The expanding number of antibody-based development programs is increasing demand for specialized production capacity across discovery, preclinical, clinical, and commercial stages. Sponsors frequently require flexible access to bioreactors, purification systems, filtration platforms, analytical capabilities, and process-development expertise without committing equivalent capital to internal infrastructure. This creates a recurring outsourcing opportunity for providers that can support technology transfer and scale-up. Thermo Fisher Scientific's current bioprocessing portfolio illustrates the shift toward connected upstream, downstream, quality, and scale operations rather than isolated services. For suppliers, the commercial impact is a larger addressable customer base and greater opportunity to secure multi-stage engagements. For sponsors, outsourcing can improve capacity flexibility while allowing internal teams to concentrate on discovery, clinical strategy, and product development.
Process Intensification Improves Manufacturing Economics
Process intensification is changing the economic rationale for antibody production by improving productivity without requiring proportional expansion of facility footprint. Higher cell densities, intensified perfusion, optimized feeds, advanced controls, and improved purification strategies can increase output from available manufacturing assets. Sartorius reported in 2026 that some manufacturers were demonstrating mAb manufacturing costs below US$50 per gram, with highly intensified approaches reaching substantially lower levels in selected settings. The market impact is significant because service providers can differentiate through process economics rather than capacity alone. Customers increasingly evaluate providers according to productivity, yield, cycle time, consumable utilization, and scalability. Consequently, process-development expertise becomes a strategic component of service contracts and strengthens opportunities for providers with integrated technology platforms.
Single-Use Manufacturing Reduces Capacity and Contamination Constraints
Single-use systems are strengthening the flexibility of antibody production services by reducing dependence on fixed stainless-steel infrastructure and enabling faster changeovers between products. Their value is particularly relevant for early clinical programs where batch volumes remain uncertain and demand can change rapidly. Thermo Fisher Scientific supports single-use bioreactors across development and commercial scale, while Sartorius integrates single-use technologies into broader monoclonal antibody workflows. This technology can reduce cleaning requirements and facilitate multiproduct manufacturing, improving asset utilization for service providers. The resulting commercial effect is greater willingness among emerging biotechnology companies to outsource production, because flexible infrastructure lowers the need for substantial internal capital expenditure. Providers with validated single-use workflows can therefore compete effectively for programs transitioning from laboratory development to clinical manufacturing.
Antibody Production Service Market Future Trends
Digital Process Control Will Become Embedded in Service Delivery
Digitalization is expected to become a more important differentiator as service providers move from equipment-centered offerings toward data-enabled manufacturing partnerships. Future workflows will increasingly connect bioreactor sensors, process analytical technologies, automated controls, electronic batch records, and predictive analytics. These capabilities can support earlier identification of process deviations and improve technology transfer between development and manufacturing sites. The antibody production service market trends will therefore increasingly emphasize data continuity across scales rather than isolated optimization at individual stages. Service contracts may also incorporate digital process monitoring, remote technical support, and performance analytics. This evolution should favor providers able to combine process expertise with interoperable software and automation architectures while maintaining strong data integrity and regulatory controls.
Regional Manufacturing Networks Will Support Supply Resilience
Future capacity expansion is likely to become more geographically distributed as pharmaceutical companies seek shorter supply chains and greater resilience. Providers may increasingly operate regional networks that combine development laboratories with clinical and commercial manufacturing capabilities. APAC is positioned to benefit because China, South Korea, India, Singapore, and Japan are building stronger bioprocess ecosystems. Thermo Fisher's Bioprocess Design Centers in India, China, Korea, and Singapore illustrate this regionalization trend. As manufacturing becomes more distributed, customers will place greater emphasis on standardized processes, technology-transfer protocols, quality equivalence, and consistent raw-material supply. Providers capable of replicating validated workflows across multiple locations should gain an advantage when multinational sponsors seek regional production options.
Antibody Production Service Market Opportunities
Integrated Development-to-Commercial Service Contracts
An important opportunity lies in developing service models that follow an antibody program from early process development through clinical supply and commercial readiness. Such arrangements can improve continuity because the same technical architecture, analytical strategy, and process knowledge can be retained as production scales. Providers can use this model to deepen customer relationships and improve revenue visibility while reducing transition risks for sponsors. The antibody production service market Forecasts indicate that sustained outsourcing demand should favor vendors capable of managing multiple process stages under coordinated agreements. Investment priorities should include scalable bioreactors, purification platforms, filtration technologies, analytics, and technology-transfer teams. The strongest commercial propositions will combine technical breadth with transparent capacity planning and clearly defined quality milestones.
High-Growth Capacity in Emerging Biopharma Hubs
Emerging biopharmaceutical hubs offer attractive investment opportunities where local development pipelines are expanding faster than specialized manufacturing infrastructure. India, South Korea, China, and selected Southeast Asian markets provide opportunities for regional service facilities, technical centers, and hybrid development-manufacturing models. Investors can target capabilities that address bottlenecks rather than replicate mature capacity, including downstream purification, filtration, process intensification, and analytical support. The opportunity is reinforced by increasing customer demand for local technical assistance and faster scale-up. Providers establishing regional platforms can also reduce transportation complexity and improve customer responsiveness. Strategic partnerships with biotechnology companies, academic institutes, and pharmaceutical manufacturers can create early access to developing pipelines while distributing infrastructure investment across multiple customer programs.
Recent Developments
- July 2026: Sartorius AG - Sartorius highlighted new manufacturing economics from process intensification, reporting that some innovative manufacturers are achieving monoclonal antibody production costs below US$50 per gram and, in selected cases, below US$20 per gram. The company linked these gains to coordinated upstream, downstream, facility, and digital improvements, reinforcing the commercial relevance of integrated manufacturing strategies.
- August 2026: Thermo Fisher Scientific Inc. - Thermo Fisher said it expects its India customer base to increase by 15–20% over the next five years, supported by growth in biopharmaceutical research and manufacturing. The company has more than 5,000 employees in India and identified the country as one of its fastest-growing Asia Pacific markets, strengthening its regional bioprocessing positioning.
- December 2025: Merck KGaA - Merck continued expanding its life-science manufacturing footprint and reported stronger new order activity in Process Solutions during 2024. Its broader strategy includes integrated bioprocessing capabilities and regional capacity investments, supporting pharmaceutical customers across development and manufacturing workflows. The company's positioning remains centered on process technologies, filtration, and biopharmaceutical production infrastructure.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for