
Ink Solvents Market Size, Share & Forecast by 2034
Coverage: By Type (Alcohols, Acetates, Hydrocarbons); Product Type (Conventional, Bio-based); Process (Flexographic, Gravure, Others); Application (Packaging, Corrugated, Publication, Others) , and Geography (North America, Europe, Asia Pacific, South and Central America)
- Status : Data Released
- Report Code : TIPRE00020910
- Category : Chemicals and Materials
- No. of Pages : 150
- Available Report Formats :


- Last update date : August 21, 2026


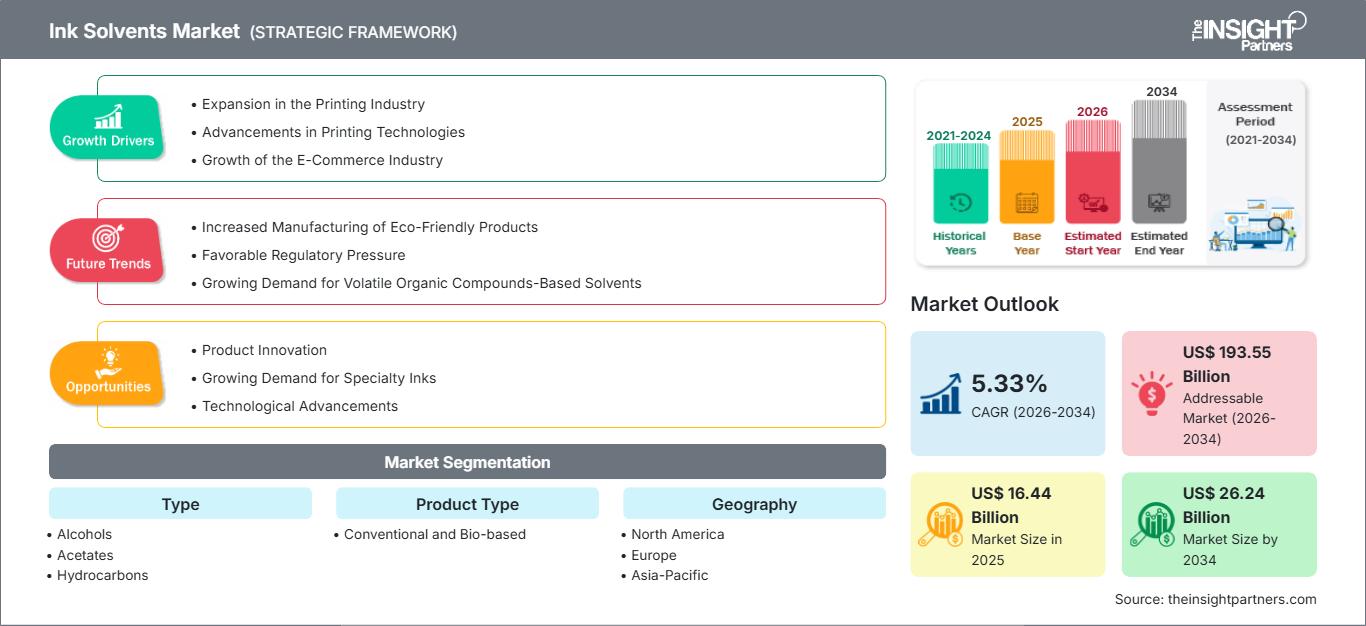
2025 Market Size
US$ 16.44 Bn
Base year value
2034 Forecast
US$ 26.24 Bn
Projected by 2034
CAGR 2026-2034
5.33 %
Growth rate
Addressable Market
US$ 193.55 Bn
(2026-2034)
The ink solvents market size is valued at US$ 16.44 Billion in 2025 and is expected to rise up to US$ 26.24 Billion by 2034, growing at a CAGR of 5.33% from 2026 to 2034. The demand is driven by solvent-based printing needs for flexible packaging, labels, commercial printing, and industrial applications. The selection of solvents is driven by their evaporation characteristics, compatibility with resin systems, adhesion to substrates, VOCs concerns, and cost efficiency.
North America is one of the most attractive markets due to advanced packaging conversion technologies, well-developed printing industry, and enhanced formulation capabilities. The growth will be driven by low-VOC formulations, bio-based solvents, and substitution of more impactful solvents. The region has highly developed technological capabilities of chemical companies and ink formulators.
Ink Solvents Market Assessment and Insights
- North America: The region is estimated to account for 26–30% ink solvents market share in 2025, supported by advanced packaging and printing infrastructure, and is expected to grow at a 6.0–6.6% CAGR between 2026–2034 as formulators prioritize compliant solvent systems.
- US: The US represents approximately 82–86% of North America's 2025 market, with sophisticated flexible packaging, labeling, and industrial printing supporting a 6.1–6.7% CAGR between 2026–2034.
- Europe: Europe is estimated at 22–25% share in 2025, with Germany, Italy, France, the UK, and Spain forming important demand centers. The region is expected to expand at a 4.4–4.9% CAGR between 2026–2034.
- Asia Pacific: Asia Pacific represents approximately 39–43% share in 2025, led by China, Japan, South Korea, and India. Expanding packaging production and industrial printing support a 5.6–6.1% CAGR between 2026–2034.
- Largest Segment: Alcohols hold an estimated 36–40% market share in 2025, supported by evaporation characteristics, solvency, and broad compatibility, with a 4.9–5.4% CAGR between 2026–2034.
- High Growth Segment: Bio-based solvents represent approximately 12–16% market share in 2025 and are expected to expand at an 8.0–8.8% CAGR between 2026–2034, driven by sustainability-oriented formulation strategies.
- Key companies analyzed in detail: BASF SE, Eastman Chemical Company, Dow Inc., Arkema S.A., Celanese Corporation, Evonik Industries AG, Ashland Inc., Solvay SA, Shell plc, Vertec Biosolvents Inc.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The industry has moved away from using relatively standardized petrochemical solvents to application-specific blends designed with drying time, solvency, odor, substrate compatibility, and regulatory considerations in mind. Alcohol and acetate-based solvents still find use in high-speed printing applications, while hydrocarbon systems are still used in applications which require specific solvency and evaporation characteristics. Cost of production remains tightly linked to feedstock availability and chemical processing capacity.
In the future, growth in packaging hubs in Asia and some parts of Latin America and the Middle East should contribute to incremental demand. The focus of investment is shifting towards renewable feedstocks, low-emission formulations, solvent recovery, and technical services. Regulation of volatile organic compounds and hazardous chemicals is also prompting companies to introduce alternative products which maintain printability while reducing environmental and occupational impacts.
Ink Solvents Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 16.44 Billion |
| Market Size by 2034 | US$ 26.24 Billion |
| Global CAGR (2026 - 2034) | 5.33% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Ink Solvents Market Analysis
Demand is highly dependent on the larger printing environment, especially flexible packaging, labeling, films, and commercial graphics. Solvents act as solvents or dispersing agents for resins and additives, help in determining viscosity and evaporate during the drying process. As such, packaging converters select solvent mixtures based on press speed, substrate, drying temperature, ink technology, and migration needs. There is, therefore, an ongoing demand for reliable grades beyond commodity replacement.
According to the Ink Solvents Market report, the value chain involves the raw materials suppliers (petroleum and bio-based), solvent manufacturers, ink manufacturers, converters, printers, and packaging companies. The supply dynamics depend on crude oil-based raw materials, availability of alcohols and acetates, energy prices, transportation costs, and regional production capabilities. Raw material suppliers with production facilities as well as diverse sources of raw materials will be able to cope with the volatility in feedstocks.
The rivalry comprises diversified chemical firms and solvent suppliers who distinguish themselves through product variety, technical assistance, sustainability, and supply reliability. Companies such as BASF SE, Eastman Chemical Company, Dow Inc., Arkema S.A., Celanese Corporation, and Evonik Industries AG have extensive chemistry portfolio capabilities that can aid in formulating customer products. Ashland Inc., Solvay SA, Shell plc, and Vertec Biosolvents Inc. add to the rivalry within specialty, hydrocarbon, oxygenated, and renewable solvents.
The Ink Solvents Market trends indicate that strategic investments are being made in the direction of low emission chemistry and bio-based feedstock along with regional supply chain resiliency. Eastman Chemical Company continues its focus on solvent-based solutions for coatings and inks, and Evonik Industries AG has come up with new technologies that provide for solventborne and digital ink formulations. Shell plc offers specialty hydrocarbon and glycol-ether solvents, and Arkema S.A. is focusing on lower VOC and bio-based solutions.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Ink Solvents Market: Strategic Insights
Regional Insights
North America ink solvents market
The North American region is forecast to have a market share of 26-30% in 2025 and is expected to grow at a 6.0-6.6% CAGR until 2034. The United States is the major contributor to demand in the region, driven by flexible packaging, label, commercial graphics, and industrial printing sectors. Canada’s demand is from packaging and specialty printing sectors. Advanced converting technology enables formulators to tailor solvent blends based on press speed, substrate type, and emission levels.
Stricter regulations on volatile organic compound emissions and hazardous air pollutants are driving replacement and recovery of solvents, and reformulation. Bio-based and low-impact solvents are being considered where they retain drying and adhesion properties. Established logistics and technical support services are the advantages of chemical producers in the region. The demand will remain robust because solvent blends still serve formulation functions despite the advancement of water-based, UV, and other technologies.
U.S. ink solvents market
The US represents about 82–86% of North America’s 2025 market and is projected to register 6.1–6.7% CAGR growth till 2034. The demand for replacement solvents is focused on flexible packaging, labeling, industrial graphics, and specialty printing. The country’s existing facilities for chemical manufacturing and formulation facilitate easy acceptance of replacement solvents and their blends.
The company presence in the ink solvents market is widespread, and BASF SE, Eastman Chemical Company, Dow Inc., Ashland Inc., and Shell plc are active in relevant solvent and formulation value chains. Packaging converters now consider VOC content, drying ability, substrate suitability, and food packaging demands in combination. Biochemistry is becoming strategically important in cases where customers require lower impact formulations without affecting press productivity.
Europe ink solvents market
Europe is estimated at 22–25% share in 2025 and is expected to register a 4.4–4.9% CAGR through 2034. Germany is the leading national market, supported by industrial printing and packaging, while Italy has a strong converting base. France and Spain provide additional packaging and commercial printing demand. The UK remains an important specialty and packaging market.
The ink solvents market forecast indicates that Germany benefits from sophisticated industrial manufacturing and high-value packaging applications, creating demand for reliable solvent systems with controlled evaporation and formulation consistency. Italy's flexible packaging and printing ecosystem supports continued consumption, particularly where gravure and flexographic processes require precise solvent selection. France and Spain are supported by food, beverage, consumer goods, and pharmaceutical packaging. European regulatory requirements encourage lower-impact formulations and greater use of bio-based or reduced-emission alternatives.
APAC ink solvents market
APAC is estimated to hold 39–43% share in 2025, making it the leading regional market, and is projected to grow at a 5.6–6.1% CAGR. China leads regional consumption, followed by Japan, South Korea, India, and Australia. High packaging volumes and expanding consumer-goods manufacturing sustain demand.
China benefits from extensive printing and converting capacity, while India is supported by expanding packaged-food, pharmaceutical, and consumer-product industries. Japan and South Korea emphasize technically advanced formulations and high-quality printing. Australia represents a smaller but established market. Industrial expansion, packaging localization, sustainability policies, and investments in modern printing equipment should maintain regional momentum.
Middle East & Africa ink solvents market
Middle East & Africa is expected to expand at a 4.8–5.3% CAGR in the ink solvents market through 2034. Saudi Arabia leads regional demand, followed by the UAE and South Africa, while the rest of MEA contributes through smaller packaging, commercial printing, and industrial applications. Growing domestic manufacturing and packaging localization support solvent consumption.
Saudi Arabia and the UAE benefit from petrochemical integration, infrastructure investment, and diversification programs, while South Africa has a comparatively developed packaging and printing ecosystem. Regional demand remains sensitive to imported raw materials, logistics costs, and currency movements. Increasing local production of consumer goods and packaged products should create opportunities for solvent suppliers offering reliable supply and application-specific grades.
Segmentation Analysis
Type
Type segmentation comprises Alcohols, Acetates, and Hydrocarbons. The segment is expected to grow at a 5.0–5.5% CAGR from 2026–2034. Alcohols remain strategically important because of their favorable evaporation characteristics and broad use in solvent-based formulations. Acetates support rapid drying and strong solvency, while hydrocarbons remain relevant where controlled evaporation, compatibility, and cost performance are important. Formulators increasingly combine different chemistries to achieve precise drying and rheological behavior.
- Alcohols: Alcohol-based solvents maintain a strong market position because they support rapid evaporation and effective resin interaction. Their established use in printing formulations provides predictable processing behavior across high-speed packaging applications.
- Acetates: Acetates are important where fast drying, solvency, and substrate compatibility must be balanced. Ethyl acetate and related grades remain particularly relevant for packaging inks and flexible-film printing systems.
- Hydrocarbons: Hydrocarbon solvents retain strategic importance in formulations requiring controlled evaporation, low odor options, or specific resin compatibility. Dearomatized grades can address applications where performance and regulatory considerations must be balanced.
Product Type
Product Type consists of Conventional and Bio-based products and is expected to expand at a 5.3–5.9% CAGR from 2026–2034. Conventional solvents retain the largest installed base because of established supply chains, cost structures, and proven formulation performance. Bio-based products are gaining momentum as printers, converters, and consumer brands seek lower-impact inputs. Adoption depends on availability, price competitiveness, technical equivalence, certification, and compatibility with existing equipment.
- Conventional: Conventional solvents remain the core supply category because of extensive manufacturing capacity, established technical specifications, and competitive economics. They will continue supporting high-volume printing applications where performance and cost remain primary purchasing criteria.
- Bio-based: Bio-based solvents are strategically important for sustainability-oriented formulations. Their adoption is strongest where renewable content, lower environmental impact, and compatibility with customer sustainability objectives justify potential formulation and procurement changes.
Opportunity Snapshot
| End Users | Revenue Contribution (High/Medium/Low) | Trend Tag | Adoption Stage |
|---|---|---|---|
| Packaging Printers | High | Flexible Packaging | Mature |
| Commercial Printers | Medium | Short Runs | Mature |
| Industrial Printers | Medium | Specialty Graphics | Scaling |
| Label Printers | High | Smart Labels | Scaling |
| Publication Printers | Low | Premium Print | Mature |
Ink Solvents Market Growth Drivers and Impact Analysis
Expansion of Flexible Packaging and Label Printing
Flexible packaging and labels provide a durable demand base because solvent-based systems can deliver fast drying, strong adhesion, and consistent print quality across films and other nonporous substrates. Growth in packaged food, beverages, personal care, pharmaceuticals, and household products increases the number of printed surfaces requiring formulation-specific solvents. For suppliers, this creates opportunities to sell differentiated solvent blends rather than individual commodity chemicals. Converters increasingly value predictable drying windows and stable viscosity because production interruptions can generate significant material waste. Demand is consequently moving toward grades supported by technical service, consistent purity, and dependable regional availability. Suppliers capable of optimizing solvent systems for high-speed presses can gain customer retention, particularly where packaging producers operate multiple production lines with standardized formulation requirements.
Regulatory Pressure on VOC and Hazardous Solvent Exposure
Environmental and occupational requirements are reshaping solvent selection across mature printing markets. Regulatory attention to volatile organic compounds, hazardous air pollutants, worker exposure, and product safety encourages formulators to reconsider traditional solvent combinations. The resulting market impact is not limited to substitution because customers also require equivalent drying, solvency, adhesion, and press performance. Suppliers therefore have an opportunity to develop lower-impact blends, higher-efficiency solvent systems, and products designed around specific regulatory thresholds. This transition can increase technical barriers to entry because successful substitution requires formulation testing rather than simple chemical replacement. Producers with application laboratories and regulatory expertise can therefore strengthen customer relationships while capturing value from specialty grades. The shift also supports greater adoption of bio-based and lower-aromatic products where performance requirements can be met.
Growth of Bio-based Chemistry in Printing Formulations
Bio-based solvents are moving from niche sustainability offerings toward a more strategic product category as brand owners and converters introduce measurable environmental objectives. Their adoption is strongest when renewable feedstock content can be combined with familiar solvency and evaporation performance. Market participants increasingly evaluate lifecycle considerations, feedstock traceability, certifications, and supply reliability alongside price. This changes competitive dynamics because chemical suppliers must establish credible renewable sourcing while maintaining consistent product quality. Bio-based products can command stronger strategic value in applications serving consumer packaging and brands with public sustainability commitments. However, broad substitution will depend on cost parity, technical equivalence, sufficient production scale, and customer willingness to reformulate. Suppliers that address these barriers through drop-in solutions and formulation support should be positioned to accelerate adoption.
Ink Solvents Market Future Trends
Precision Solvent Blending for High-Speed Printing
Future formulation development is expected to emphasize precision blending rather than reliance on single-solvent systems. High-speed presses require carefully controlled evaporation to prevent defects, retain print quality, and match increasingly diverse substrates. Digital process monitoring and improved formulation software can help manufacturers adjust solvent ratios to changing production conditions. This will increase demand for solvent portfolios offering predictable physical properties and narrow specification ranges. Suppliers may increasingly provide application-specific blends rather than only standard grades, particularly for flexible packaging and specialty labels. The trend also creates opportunities to reduce solvent consumption per printed area through optimized drying profiles. As printing equipment becomes faster and more automated, solvent suppliers will need stronger technical collaboration with ink manufacturers and converters to maintain formulation stability.
Renewable Feedstocks and Circular Formulation Strategies
The next phase of sustainability will extend beyond replacing individual petrochemical solvents with renewable alternatives. Manufacturers are likely to evaluate feedstock origin, carbon intensity, recyclability, process efficiency, and end-of-life considerations together. Bio-based solvent systems can therefore become part of broader circular packaging strategies rather than isolated product substitutions. Demand should increase for products supported by transparent sourcing and credible environmental documentation. At the same time, customers will remain sensitive to cost and technical performance, limiting adoption where renewable chemistry requires substantial process changes. Suppliers with integrated feedstock access and established formulation expertise can reduce these barriers. The competitive advantage will increasingly come from combining renewable content with reliable drying, solvency, regulatory compliance, and compatibility across existing printing equipment.
Ink Solvents Market Opportunities
Regional Manufacturing and Supply Localization
Regionalization creates opportunities for solvent suppliers to establish production, blending, warehousing, and technical-support capabilities closer to major packaging centers. Asia Pacific is particularly attractive because of its extensive printing and converting base, while North America and Europe offer opportunities for specialty and compliance-oriented grades. Localized supply can reduce transportation exposure, improve inventory responsiveness, and help customers manage feedstock disruptions. Producers can also use regional technical centers to customize blends for local substrates, printing equipment, and regulatory requirements. Investment decisions should prioritize locations with strong chemical infrastructure, reliable utilities, established logistics, and access to packaging clusters. Companies that combine regional availability with application expertise can differentiate themselves from suppliers competing primarily on commodity pricing.
Bio-based Solvent Portfolio Expansion
Bio-based solvent development offers an investment opportunity across renewable feedstocks, fermentation-derived intermediates, and lower-carbon chemical pathways. The strongest commercial prospects are products that function as practical replacements within established ink formulations without requiring extensive equipment modification. Investors and manufacturers should prioritize solvent chemistries with broad resin compatibility, predictable evaporation, and competitive economics. Partnerships between feedstock producers, chemical companies, ink manufacturers, and packaging converters can accelerate validation and commercialization. Certification, traceability, and lifecycle documentation will also become important purchasing criteria for multinational customers. Portfolio expansion should therefore combine chemistry development with supply-chain planning and customer trials. Companies that reach commercial scale while maintaining consistent quality may capture premium opportunities as sustainability commitments increasingly influence procurement decisions.
Recent Developments
- June 2026: Siegwerk, a global company in printing inks and coatings for packaging applications, announced the successful completion of its acquisition of Hi-Tech Inks, one of India’s leading manufacturers of flexographic and gravure printing inks.
- March 2026: Eastman Chemical Company announced price increases in NAR and LAR for products including Eastman DB Solvent, Eastman DTB Solvent, Eastman EB Solvent, and Eastman EP Solvent, effective March 26, 2026.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for