
Irrigation Automation Market Demand, Trends & Forecast by 2034
Coverage: By Automation Type (Time-Based Systems, Volume-Based Systems, Real-Time Feedback Systems, and Computer-Based Irrigation Control Systems); Irrigation Type (Drip Irrigation, Sprinkler Irrigation, and Surface Irrigation); Component (Controllers, Sensors, Valves, Sprinklers, and Others); System (Automatic and Semiautomatic); End-user (Agricultural and Non-Agricultural); and Geography
- Status : Data Released
- Report Code : TIPRE00011988
- Category : Electronics and Semiconductor
- No. of Pages : 150
- Available Report Formats :


- Last update date : September 22, 2026


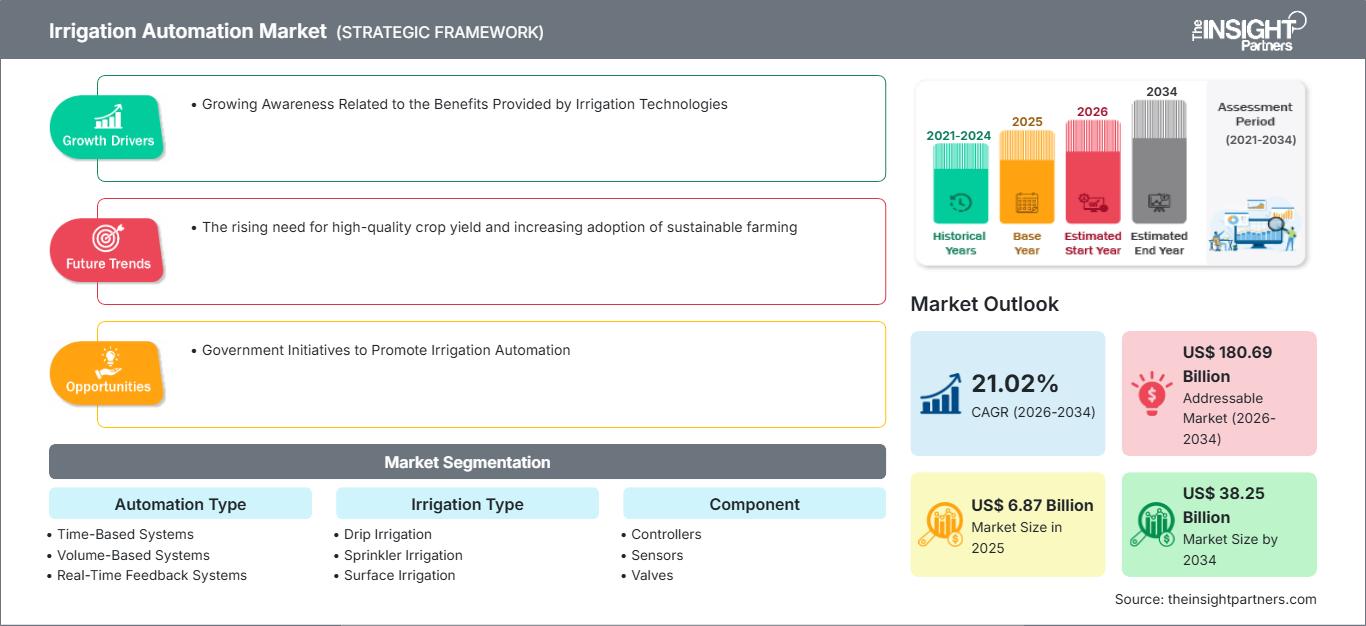
2025 Market Size
US$ 6.87 Bn
Base year value
2034 Forecast
US$ 38.25 Bn
Projected by 2034
CAGR 2026-2034
21.02 %
Growth rate
Addressable Market
US$ 180.69 Bn
(2026-2034)
Irrigation Automation Market is expanding as farms, irrigation districts, and controlled-environment operations adopt connected controllers, sensors, valves, and software to improve water application precision. The market is valued at US$ 6.87 Billion in 2025 and is projected to reach US$ 38.25 Billion by 2034, registering a CAGR of 21.02% during 2026–2034. Adoption is increasingly linked with water scarcity, labor constraints, climate variability, and the digitization of agricultural infrastructure.
North America Irrigation Automation Market Size remains a technologically advanced regional market, with an estimated CAGR of 18–21% during 2026–2034. Precision agriculture adoption, large-scale mechanized farming, and water-management regulations are strengthening demand. Increasing integration of remote monitoring, soil-moisture sensing, variable-rate application, and cloud-based irrigation management is also improving the economics of automation for commercial growers and irrigation districts.
Irrigation Automation Market Assessment and Insights
- North America is expected to command a 2025 share of 28–32% and grow at a CAGR of 18–21% between 2026–2034, supported by precision agriculture, mechanized irrigation, water-management programs, and established digital farming infrastructure.
- US accounts for approximately 75–80% of North America's 2025 demand and is projected to expand at a CAGR of 18–21% during 2026–2034, led by commercial farming and irrigation modernization.
- Europe is estimated at a 2025 share of 18–22%, with a CAGR of 19–22% during 2026–2034, led by Spain, Italy, France, Germany, and the UK, where water efficiency and digital agriculture are strategic priorities.
- Asia Pacific represents an estimated 2025 share of 31–35% and is forecast to grow at a CAGR of 23–26% during 2026–2034, led by China, India, Japan, Australia, and South Korea.
- Largest Segment: Drip Irrigation holds an estimated Irrigation Automation Market share of 39–43% in 2025, with a CAGR of 21–23% during 2026–2034, reflecting precision water delivery and fertigation compatibility.
- High Growth Segment: Real-Time Feedback Systems account for approximately 12–16% market share in 2025, advancing at a CAGR of 25–28% during 2026–2034, supported by sensor-driven control.
- Key companies analyzed in detail: Galcon Ltd.; Hunter Industries, Inc.; Irritec S.p.A.; Jain Irrigation Systems Limited; Lindsay Corporation; Nelson Irrigation Corporation; Rubicon Water; The Toro Company; Valmont Industries, Inc.; WaterBit, Inc.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The technology for the irrigation of farmland is evolving from being time-dependent to being based on sensors and remote management of water applications. While the former is prevalent, the latter involves pressure sensors, flow meters, soil moisture sensors, weather data and connected valves. Agricultural production systems have become modular, which allows farmers to integrate their on-ground technology with cloud-based software solutions. This results in lower manual efforts and more consistent water application on diversified farms.
Going forward, adoption of these solutions will likely be driven by countries with stressed water resources in agricultural production systems. This includes Asia, Middle East, Africa and Southern Europe among others. Public investments in irrigation modernization, digital agriculture initiatives and other efficiency programs may contribute to adoption of these technologies. Subscription-based business models covering technology, software, maintenance and advisory services might lower entry barriers.
Irrigation Automation Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 6.87 Billion |
| Market Size by 2034 | US$ 38.25 Billion |
| Global CAGR (2026 - 2034) | 21.02% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Irrigation Automation Market Analysis
The Irrigation Automation Market growth is driven by the demand for higher water productivity without compromising agricultural yield. According to FAO, the agriculture industry constitutes 72% of global fresh water abstractions, which implies that irrigation efficiency becomes a key aspect of resource management. Ecosystem players include pump manufacturers, irrigation equipment manufacturers, controller vendors, sensor developers, software providers, system integrators, agricultural distributors, and irrigation districts. Thus, the demand is going beyond standalone controllers and expanding to integrated water management solutions.
Supply trends are shifting to modular controllers, wireless sensors, automated valves, variable-frequency drives, and cloud-based management systems. Increasingly, hardware suppliers have to be compatible with a range of irrigation systems and communication protocols. System integrators are crucial for the industry as proper installation, hydraulic engineering, sensors placement, and calibration have a significant effect on product performance. This gives an advantage to suppliers capable of combining equipment with analytics and remote management solutions.
In the Irrigation Automation Market Report, there is competition for irrigation equipment, automation controls, precision agriculture, and digital farm-management systems. Galcon Ltd. and Hunter Industries, Inc. have competitive controller and irrigation technology products, whereas Irritec S.p.A. and Jain Irrigation Systems Limited have competitive irrigation infrastructure along with automation solutions. Lindsay Corporation, Nelson Irrigation Corporation, Rubicon Water, and Valmont Industries, Inc. offer their solutions for mechanized and water delivery.
Positioning is gradually moving toward integrated platforms that integrate field equipment with data. The Toro Company offers irrigation technologies along with agricultural and landscape solutions whereas WaterBit, Inc. focuses on connected precision agriculture solutions. Increasingly, investment is being made in sensor integration, remote controls, predictive scheduling, and interoperable software. Established distribution networks of vendors can help with quicker deployment through automation with irrigation system modernization and installation.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Irrigation Automation Market: Strategic Insights
Regional Insights
North America Irrigation Automation Market
North America region is expected to hold a share of 28-32% of the Irrigation Automation Marketshare in 2025 and will have a CAGR of 18-21% from 2025 to 2034. In terms of regions within North America, the U.S will dominate due to commercial agriculture, mechanization of irrigation, and precision agriculture. Canada will help in driving the demand owing to specialty agriculture, greenhouse agriculture, and water management. Adoption trends in the region include remote sensing, soil moisture sensing, weather-based scheduling, and valve automation.
A case in point is California and its Department of Water Resources, which has the CIMIS – a system of more than 145 automated weather stations for irrigation planning. Commercial farmers have increasing preference for connecting such environmental data with controllers and sensors in fields. Big farms have preference for scalable platforms that can manage multiple fields, while irrigation districts increasingly test automated gates, flow control, and scheduling systems.
U.S. Irrigation Automation Market
The United States makes up 75–80% of the 2025 North American market share and is expected to have a CAGR of 18–21% during 2026-2034. Agricultural farms, orchards, vineyards, row crops, and irrigation districts are the primary demand sources. Labor costs, drought vulnerability, farm mechanization, and existing infrastructure for precision agriculture contribute to adoption.
Some companies involved include Lindsay Corporation, Hunter Industries, Inc., The Toro Company, Valmont Industries, Inc., and WaterBit, Inc. Applications include remote scheduling, variable-rate irrigation, pump optimization, soil moisture monitoring, and equipment diagnostics. More farmers are looking for irrigation systems that can automate their irrigation decision-making process using sensor data than those that offer a dashboard view only. Existing pivots, drip irrigation, and farm management software compatibility have become an important purchase criteria for buyers.
Europe Irrigation Automation Market
Europe is expected to be in the 18-22% market share in 2025 and have growth at a 19-22% CAGR until 2034; with Spain as the key player. The UK, Germany, France, Italy, and Spain offer different markets due to the demands of water efficiency, precision agriculture, and agricultural digitization.
The UK market benefits from protected cultivation, horticulture, and technology-driven farms that require accuracy in watering. Irrigation controllers and environment sensors could lessen the requirement for manual irrigation decision-making and incorporate weather data. The demands in the region are also due to labor availability and consistency in water distribution in intensive production environments.
In Germany, there is a highly developed industrial and technology base for agricultural automation. The demands in the region are in the form of high-value crops, controlled environments, and digitally-enabled farms. The requirements of the market include reliable sensors, controllers, and interfaces to farm management software systems.
The three countries that look promising include Spain, Italy, and France. The main advantage in Spain is that there is an abundance of irrigation and also shortage of water in the country, thus making it the perfect destination for automation. In Italy, the areas of specialty farming and greenhouses stand out, whereas in France, it is extensive farming using precision farming.
APAC Irrigation Automation Market
The APAC region is projected to have a share of 31-35% in 2025 and register a growth of 23-26% CAGR, with China being the front-runner. Other countries that will contribute to the demand are India, Japan, South Korea, and Australia, which have demands across commercial agriculture, horticulture, and controlled environments.
Factors such as industrialization of agriculture, water scarcity, agriculture modernization, and digital agriculture initiatives by governments are crucial catalysts for growth. China and India have high deployment potential due to the size of their agriculture, whereas Australia is focusing on water efficiency.
Middle East & Africa Irrigation Automation Market
The Middle East and Africa region is expected to have a CAGR of 17-20% till 2034 due to the efforts made in Saudi Arabia and UAE. South Africa offers a great deal in terms of the technological base of agricultural technologies whereas the Rest of MEA region comprises emerging demands from water-scarce agricultural landscapes.
The UAE and Saudi Arabia are implementing controlled agriculture systems and food security initiatives along with water usage efficiency, which brings about the need for automated irrigation such as automated drip and sprinkler irrigation. Commercial farming and precision agriculture help South Africa. Overall, energy prices, groundwater management, infrastructure modernization, and freshwater scarcity justify automation.
Segmentation Analysis
Automation Type
Automation Type is expected to expand at a 22–25% CAGR during 2026–2034. The Irrigation Automation Market scope increasingly favors systems that connect scheduling with real-time field conditions. Time-based solutions remain accessible, while feedback-driven and computer-based systems are gaining importance as farms adopt sensors, connectivity, and decision-support software.
- Time-Based Systems remain widely used because they provide simple, predictable scheduling and can automate recurring irrigation cycles without requiring extensive sensing infrastructure or sophisticated farm-management software.
- Volume-Based Systems improve control by regulating water according to measured delivery volumes, supporting applications where consistent application quantities are more important than fixed operating durations.
- Real-Time Feedback Systems use field and environmental measurements to modify irrigation decisions, making them strategically important for water-constrained farms seeking responsive and data-driven application.
- Computer-Based Irrigation Control Systems integrate controllers, software, sensors, and communication networks, supporting centralized management of complex farms and multi-zone irrigation infrastructure.
Irrigation Type
Irrigation Type is projected to register a 20–23% CAGR during 2026–2034. Drip systems remain highly compatible with automation because emitters, valves, fertigation equipment, and sensors can be coordinated precisely. Sprinkler automation is also expanding, while surface systems present modernization opportunities where water-delivery infrastructure is upgraded.
- Drip Irrigation holds the largest position because localized application supports precise scheduling, fertigation, sensor integration, and efficient water delivery across orchards, vineyards, horticulture, and row crops.
- Sprinkler Irrigation benefits from automation across field crops, turf, specialty agriculture, and mechanized systems where pressure, timing, weather conditions, and application uniformity require coordinated control.
- Surface Irrigation represents a modernization opportunity as automated gates, flow controls, level sensors, and scheduling technologies improve management of traditionally manual water-distribution systems.
Component
Component is forecast to grow at a 21–24% CAGR during 2026–2034 as automation deployments require coordinated hardware. Controllers provide system intelligence, sensors supply field information, valves execute irrigation commands, and sprinklers deliver water. Increasing integration is shifting procurement toward interoperable component ecosystems rather than isolated devices.
- Controllers serve as the operational intelligence layer, coordinating schedules, sensor inputs, valves, pumps, and communication interfaces while enabling centralized or remote irrigation management.
- Sensors provide soil, weather, flow, pressure, and environmental information, strengthening the transition from predetermined irrigation toward responsive application based on measurable field conditions.
- Valves translate digital instructions into hydraulic actions and are strategically important for zone-level control, flow management, fertigation coordination, and automated response to field conditions.
- Sprinklers remain essential application hardware in automated systems, with digitally managed pressure, timing, and movement improving consistency across large agricultural and landscape irrigation areas.
System
System is expected to advance at a 21–24% CAGR during 2026–2034. Automatic systems are gaining preference where continuous monitoring and large-scale operations justify comprehensive controls. Semiautomatic systems remain relevant where operators require flexibility or where farms are progressively upgrading legacy irrigation infrastructure.
- Automatic systems provide end-to-end control with limited manual intervention, supporting large farms and complex irrigation networks where scheduling, sensing, and hydraulic execution must operate continuously.
- Semiautomatic systems combine automated functions with operator intervention, offering a practical transition path for farms seeking incremental modernization without replacing existing irrigation infrastructure.
Opportunity Snapshot
| Application | Revenue Contribution (High/Medium/Low) | Trend Tag (MAX 2 words) | Adoption Stage (Emerging/Scaling/Mature) |
|---|---|---|---|
| Manufacturing | Low | N/A | Emerging |
| Automotive | Low | N/A | Emerging |
Irrigation Automation Market Growth Drivers and Impact Analysis
Escalating pressure on agricultural water productivity
Water scarcity is converting irrigation efficiency from an environmental objective into an operational priority. FAO identifies agriculture as responsible for 72% of global freshwater withdrawals, while 1.2 billion people live in agricultural areas facing severe water constraints. These conditions strengthen the economic case for technologies that measure application, identify field requirements, and automate delivery. The market impact extends across equipment replacement, irrigation modernization, and software adoption. Growers can increasingly justify automation through improved control rather than relying solely on potential yield gains. Irrigation districts also gain incentives to automate water distribution and reduce avoidable conveyance losses. Consequently, demand is shifting toward systems that combine hydraulic control with measurable field information and centralized management capabilities.
Labor constraints are accelerating automated irrigation operations
Agricultural labor availability directly affects the practicality of manual irrigation scheduling, valve operation, equipment inspection, and field visits. Automation can transfer repetitive activities from workers to controllers, sensors, and remote platforms, allowing operators to supervise larger cultivated areas with fewer physical interventions. This changes investment priorities because farms increasingly evaluate technology through labor productivity as well as water savings. The impact is particularly relevant for orchards, vineyards, greenhouse operations, and geographically dispersed farms where irrigation activities can consume substantial management time. Remote alerts also allow operators to respond to equipment faults without continuously inspecting every field. As agricultural enterprises consolidate and professionalize, centralized control becomes more valuable, strengthening demand for scalable automation architectures.
Climate variability is increasing the value of responsive scheduling
More variable rainfall, temperature, evaporation, and drought conditions make fixed irrigation calendars less suitable for many crops. Responsive systems can incorporate soil moisture, weather observations, flow measurements, and crop requirements to modify irrigation timing. California's CIMIS network demonstrates how automated weather information can support irrigation decisions, with more than 145 stations collecting field-relevant meteorological data. The commercial impact is an expanding role for sensor-linked controllers that translate environmental information into operational actions. Instead of treating irrigation as a predetermined schedule, growers can manage it as a dynamic process. This supports investment in feedback systems, weather integration, remote communications, and analytics, while increasing the value of platforms that can interpret multiple data sources simultaneously.
Irrigation Automation Market Future Trends
AI-assisted irrigation decisions will become more operationally embedded
AI-assisted irrigation in the Irrigation Automation Market Trends is likely to progress from advisory recommendations toward partially autonomous water-management decisions. Future platforms can combine historical irrigation records, soil characteristics, weather forecasts, crop stages, evapotranspiration estimates, and equipment performance to recommend or automatically execute schedules. The key shift will be from displaying information to continuously optimizing actions against water availability and crop requirements. Model explainability will remain important because growers need confidence when automated decisions affect production. Vendors may increasingly offer configurable decision policies, allowing users to define water limits, crop priorities, and operational constraints. Integration with farm-management software should further reduce fragmented workflows, making irrigation intelligence an embedded function within broader digital agriculture environments.
Digital twins will improve irrigation-system commissioning and optimization
Digital representations of irrigation networks could become increasingly useful for designing, commissioning, and optimizing automated systems. A digital twin can connect hydraulic characteristics, field zones, equipment states, flow behavior, and sensor information, allowing operators to identify pressure anomalies or inefficient operating conditions before they become costly failures. For large farms and irrigation districts, such models could support scenario testing when water allocations, crop patterns, or infrastructure configurations change. The technology may also improve system expansion because new valves, pumps, sensors, and zones can be evaluated within an existing digital architecture. As connectivity improves, continuous data synchronization can transform digital twins from engineering tools into operational management layers supporting maintenance, planning, and resource allocation.
Irrigation Automation Market Opportunities
Integrated water-management platforms for irrigation districts
The Irrigation Automation Market Forecasts indicate an opportunity to extend automation beyond individual farms into district-scale water delivery. Irrigation districts can combine automated gates, flow measurement, online water ordering, scheduling software, and field-level information to coordinate supply with actual demand. Such projects require larger capital commitments but can generate value across entire distribution networks. Investors and technology providers should target platforms capable of integrating legacy infrastructure with new digital controls rather than requiring complete system replacement. Modular modernization can reduce implementation risk and improve adoption. District-scale projects also create recurring opportunities for software, maintenance, telemetry, analytics, and remote support. Partnerships with engineering firms and public water agencies could accelerate project development.
Subscription models can lower adoption barriers for growers
Automation suppliers can expand addressable demand through equipment-as-a-service, software subscriptions, and bundled monitoring contracts. These models can reduce upfront expenditure while providing growers with controllers, sensors, connectivity, analytics, maintenance, and technical support through predictable payments. The approach is particularly relevant for smaller commercial farms that may lack dedicated automation specialists. Vendors can also structure packages according to acreage, irrigation zones, or connected devices, allowing customers to scale gradually. Strategic investment should prioritize platforms with recurring software revenue and hardware interoperability because such architectures can support expansion across multiple irrigation methods. Distributor networks can strengthen this model by providing local installation, calibration, training, and service while central platforms manage software and analytics.
Recent Developments
- February 2026: R M Drip & Sprinklers Systems entered the IoT-based smart irrigation and digital agriculture segment through a strategic technology partnership with an advanced farm-automation technology company, marking a shift from a hardware-led business toward an integrated hardware + software platform. The initiative, commencing in March 2026, is expected to generate new revenue streams from smart irrigation hardware, mobile applications, analytics and subscriptions, while leveraging the company’s 1,000+ dealer and retail touchpoints for nationwide distribution.
- June 2026: Rivulis Europe entered into a strategic partnership with Spanish agri-tech company Spherag to expand its smart irrigation portfolio across European agricultural markets. Under the agreement, Spherag’s digital irrigation automation and fertigation solutions will be made available through Rivulis’ commercial network, giving growers access to connected tools for more efficient irrigation management. A key solution is the Atlas X controller, which connects to a cloud-based platform to collect and process data from field sensors, enabling remote monitoring and automated irrigation control.
- August 2026: Netafim, part of Orbia’s Precision Agriculture business, launched GrowSphere FLEX, a smart irrigation and fertigation controller designed to make connected farm automation more accessible to smallholder and mid-sized farms. The system features built-in cellular connectivity and can be configured for different crops, field layouts and farm sizes, while GrowSphere Workspace enables remote management of irrigation and fertigation, along with access to sensors, reports and alerts.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for