
Metal Forming Market Demand, Size & Forecast by 2034
Coverage: by Forming Type (Cold Forming, Hot Forming); Application (BIW, Chassis, Closures); Material Type (Steel, Aluminum); Vehicle Type (Passenger Car, Light Commercial Vehicle, Truck, Bus); Techniques (Roll Forming, Stretch Forming, Deep Drawing, Stamping, Hydroforming) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00004346
- Category : Electronics and Semiconductor
- No. of Pages : 150
- Available Report Formats :


- Last update date : October 13, 2026


2025 Market Size
US$ 250.84 Bn
Base year value
2034 Forecast
US$ 333.33 Bn
Projected by 2034
CAGR 2026-2034
3.62 %
Growth rate
Addressable Market
US$ 2,708.23 Bn
(2026-2034)
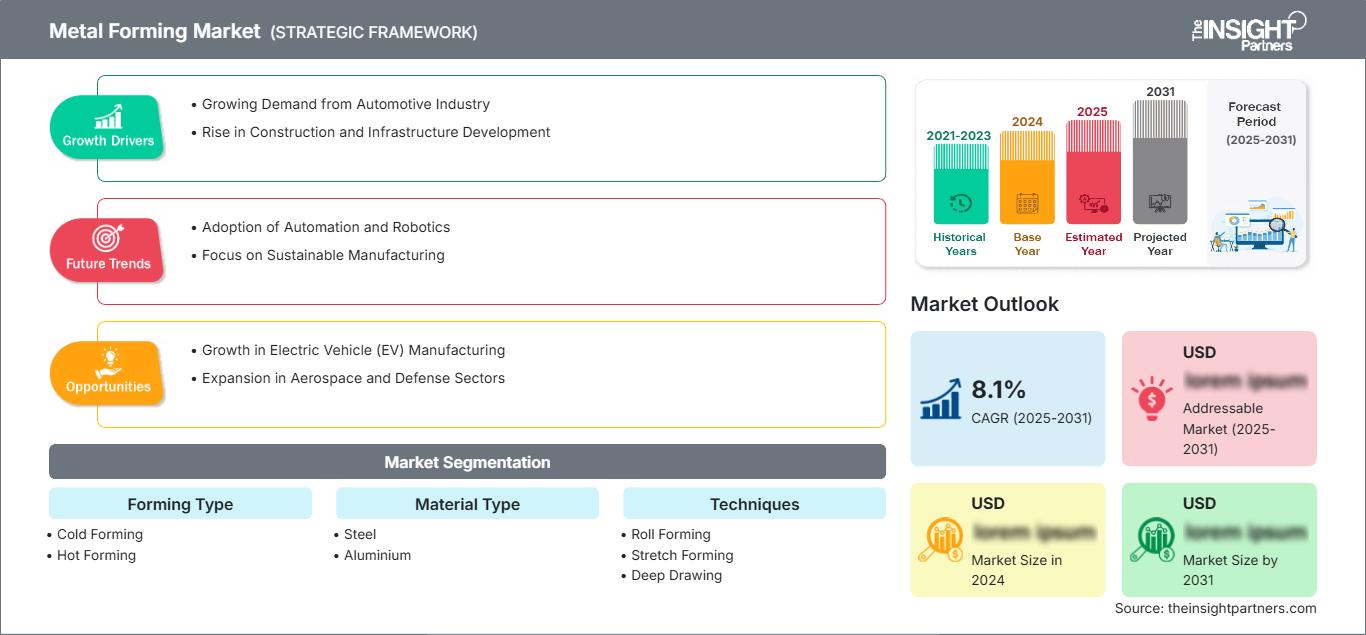
The metal forming market was valued at US$ 250.84 Billion in 2025 and is projected to reach US$ 333.33 Billion by 2034, registering a CAGR of 3.62% during 2026–2034. The market continues to benefit from steady industrial production, expanding automotive manufacturing, infrastructure investments, and increasing adoption of precision-engineered components across transportation, construction, aerospace, and heavy equipment industries. Manufacturers are also emphasizing process efficiency, material optimization, and digital production technologies to improve product quality and operational competitiveness.
Across North America, manufacturers continue to strengthen production capabilities through automation, lightweight material adoption, and modernization of industrial facilities. The metal forming market size in the region is supported by growing investments in automotive electrification, aerospace manufacturing, and advanced industrial machinery. Regional demand is expected to expand at a CAGR ranging between 3.1% and 3.8% during 2026–2034, supported by reshoring initiatives, favorable manufacturing policies, and increasing deployment of digitally integrated production systems.
Metal Forming Market Assessment and Insights
- North America: Accounted for 30–34% share in 2025 and is anticipated to expand at a CAGR of 3.1%–3.8% during 2026–2034. Demand remains supported by advanced manufacturing, aerospace production, automotive innovation, and continued investments in industrial automation.
- U.S.: Represented 72–76% of the North American market in 2025 and is projected to grow at a CAGR of 3.2%–3.9% during 2026–2034, driven by strong automotive, defense, and heavy industrial manufacturing activities.
- Europe: Held 25–29% share in 2025 and is expected to register a CAGR of 2.9%–3.6% during 2026–2034. Germany, Italy, France, and the UK continue to lead regional demand through advanced automotive, machinery, and industrial equipment manufacturing.
- Asia Pacific: Captured 33–37% share in 2025 and is forecast to record the highest regional CAGR of 4.2%–4.9% during 2026–2034, supported by expanding manufacturing capacity across China, India, Japan, and South Korea.
- Largest Segment: Steel accounted for approximately 56–60% market share in 2025 and is anticipated to grow at a CAGR of 3.2%–3.8% during 2026–2034, reflecting its extensive use across automotive, construction, and industrial manufacturing.
- High Growth Segment: Hydroforming represented approximately 10–14% market share in 2025 and is projected to register a CAGR of 5.2%–5.9% during 2026–2034, supported by increasing production of lightweight and high-strength structural components.
- Key companies analyzed in detail: AISIN SEIKI Co., Ltd., BENTELER International AG, CIE Automotive S.A., Hirotec Corporation, Magna International Inc., Mills Products Inc., Superform Aluminum Limited, Tower International, Inc., TOYOTA BOSHOKU CORPORATION, VNT Automotive GmbH.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The constant improvements in the field of manufacturing technology have brought a revolution in the manufacturing methods used by the entire metal forming industry through increasing accuracy, decreasing wastage of materials, and increasing speed. There is increased usage of automation, robotic manipulation, press operations, and process control within the manufacturing lines for consistency and cost reduction. The use of more advanced steel and light aluminum materials in manufacturing has brought many changes, especially for industries like the automobile and aviation industries.
In the future, investments will see a rise in Southeast Asia, India, Mexico, and manufacturing locations in the Middle East. Sustainable regulations and the use of energy-saving technologies in production and smart factories will foster sustainable growth. In addition, localization of component production and capacity building will enhance the competitiveness of the industry and bring more opportunities in developing and developed countries.
Metal Forming Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 250.84 Billion |
| Market Size by 2034 | US$ 333.33 Billion |
| Global CAGR (2026 - 2034) | 3.62% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Metal Forming Market Analysis
Rising demand from transportation, construction, and industrial manufacturing continues to strengthen metal forming market growth across both mature and developing economies. The increase in production of electric cars, infrastructure development, and the need for lightweight but robust components is enhancing the investment in forming technologies. Companies are increasingly using digital inspection methods, predictive maintenance systems, and automation in order to enhance efficiency and cut down on waste at every stage of the manufacturing process.
The industry's supply chain network is evolving through improved cooperation between raw material suppliers, machinery suppliers, parts suppliers, and OEMs. The presence of advanced steels, aluminum alloys, and accurate tooling ensures flexible production, while investing in local manufacturing facilities improves customer satisfaction and reduces supply chain risks.
A competitive metal forming market analysis indicates that manufacturers are increasingly differentiating themselves through technological innovation, customized engineering solutions, and expanded global production networks. Magna International Inc., AISIN SEIKI Co., Ltd., BENTELER International AG, CIE Automotive S.A., and TOYOTA BOSHOKU CORPORATION are among those still investing in lightweight structure design and automation technology for better positioning in the market.
Strategic partnerships, plant upgrading, and investment in digital manufacturing are still the major competitive focus areas. Hirotec Corporation, Superform Aluminum Limited, Mills Products Inc., Tower International, Inc., and VNT Automotive GmbH are still focusing on the ability to produce high-end formed products and efficiency in order to meet new needs in the automotive, industrial machinery, and aerospace industries.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Metal Forming Market: Strategic Insights
Regional Insights
North America Metal Forming Market
North America accounted for 30–34% of the metal forming market share in 2025 and is projected to expand at a CAGR of 3.1%–3.8% during 2026–2034. The area enjoys an existing industrial ecosystem, a high level of manufacturing, and ongoing investment in automation technology. Automotive manufacturing, aerospace engineering, and heavy machinery continue to be the leading users of precision metal components, and reshoring programs have been boosting local manufacturing capacity.
Servo presses, robotic material handling solutions, and digital process control are becoming more common tools used by manufacturers to boost productivity and quality. Infrastructure modernization, electric vehicles, and defense manufacturing remain areas of public and private spending that help to drive the demand for the future. Energy efficiency and sustainability requirements serve as additional motivation for implementing new forming technologies. It allows companies to remain competitive, minimize waste, and lower their cost structure.
U.S. Metal Forming Market
The U.S. represented 72–76% of the North American market in 2025 and is expected to register a CAGR of 3.2%–3.9% during 2026–2034. Robust manufacturing capacity within the automobile industry, aerospace sector, defense industry, construction equipment, and industrial equipment segments drives the demand for premium metal-formed components. Top players remain busy expanding their manufacturing capacities, along with adopting digital manufacturing methods for increased production.
Investment in the manufacture of electric vehicles, batteries, and reshoring projects keeps creating favorable market conditions. Domestic players remain engaged in collaborating with original equipment manufacturers for improving supply chain robustness and reducing lead times in production. Manufacturing plants are getting updated with the help of robotic technology, artificial intelligence-based inspection technology, and automation in forming machines.
Europe Metal Forming Market
Europe captured 25–29% of the global market in 2025 and is anticipated to grow at a CAGR of 2.9%–3.6% during 2026–2034. Germany continues to dominate the region because of the automotive industry, heavy machinery production, and the precision engineering industry. Investments in lightweight manufacturing processes and Industry 4.0 strategies continue to make production processes more efficient and boost the manufacturing competitiveness of the region internationally.
The UK continues increasing manufacturing operations of high-value-added aerospace manufacturing and engineering and automotive engineering. Germany is advantaged by advanced industrial automation, automotive manufacturing, and engineering, which continue to enable continued investments in new forming machines. France, Italy, and Spain as a whole help boost regional demand through transportation projects, industrial machinery production, renewable energy facilities, and sustainable manufacturing technology.
APAC Metal Forming Market
Asia Pacific accounted for 33–37% of the market in 2025 and is forecast to register the highest regional CAGR of 4.2%–4.9% during 2026–2034. China remains the leading contributor, while Japan, South Korea, and India continue expanding advanced manufacturing capabilities supported by favorable industrial policies and export-oriented production.
Growing investments in automotive manufacturing, consumer electronics, renewable energy equipment, and industrial machinery continue to accelerate demand throughout the region. Australia contributes through mining equipment and infrastructure-related manufacturing, while India's expanding industrial base and government-led manufacturing initiatives strengthen long-term regional growth prospects.
Middle East & Africa Metal Forming Market
The Middle East & Africa market is projected to expand at a CAGR of 3.4%–4.1% during 2026–2034. Saudi Arabia remains the largest regional market, supported by industrial diversification initiatives, infrastructure development, and expanding manufacturing investments. The United Arab Emirates continues to strengthen precision manufacturing capabilities through industrial modernization programs.
South Africa maintains an important position through its established automotive manufacturing industry and mining equipment production. The remaining Middle Eastern and African countries are witnessing gradual industrial expansion supported by energy investments, transportation infrastructure projects, and increasing localization of manufacturing activities, creating additional opportunities for advanced metal forming technologies.
Segmentation Analysis
Forming Type
The Forming Type segment is expected to expand at a CAGR of 3.6%–4.1% during 2026–2034. The metal forming market scope continues to broaden as manufacturers adopt both cold and hot forming processes according to component complexity, material characteristics, and end-use requirements. Advancements in automation and process control improve production precision while reducing manufacturing costs across automotive, aerospace, and industrial equipment applications.
- Cold Forming: Widely adopted for producing high-precision components with superior dimensional accuracy and excellent surface finish. Manufacturers prefer this process for high-volume production because it minimizes material waste while improving mechanical properties.
- Hot Forming: Extensively utilized for manufacturing complex, high-strength structural components requiring enhanced ductility. Rising adoption in automotive safety components and heavy industrial applications continues to support long-term demand for hot forming technologies.
Material Type
The Material Type segment is projected to register a CAGR of 3.3%–3.9% during 2026–2034. Material selection remains a critical factor influencing manufacturing efficiency, product performance, and lifecycle cost. Increasing emphasis on lightweight designs, sustainability, and improved structural performance continues to encourage innovation in both steel and aluminum forming applications.
- Steel: Maintains the dominant market position owing to its high strength, durability, cost-effectiveness, and extensive application across automotive, construction, industrial machinery, and heavy engineering sectors.
- Aluminium: Experiences increasing adoption because of its lightweight characteristics, corrosion resistance, and recyclability. Demand continues to rise across electric vehicles, aerospace structures, transportation equipment, and energy-efficient manufacturing applications.
Techniques
The Techniques segment is anticipated to grow at a CAGR of 4.0%–4.6% during 2026–2034. Continuous innovation in forming technologies enables manufacturers to produce increasingly complex components while improving productivity and reducing material utilization. Advanced simulation software and automated production systems further strengthen manufacturing precision and process reliability.
- Roll Forming: Preferred for continuous production of uniform profiles used extensively in construction materials, transportation equipment, storage systems, and industrial infrastructure requiring high production efficiency.
- Stretch Forming: Supports production of large curved metal components with excellent dimensional consistency, making it particularly valuable in aerospace structures, transportation systems, and architectural applications.
- Deep Drawing: Enables efficient manufacturing of seamless hollow components widely used in automotive assemblies, industrial containers, kitchen equipment, and consumer durable products requiring high structural integrity.
- Stamping: Represents one of the most widely adopted manufacturing techniques for mass production of precision components, supporting automotive body structures, electronics, appliances, and industrial machinery.
- Hydroforming: Increasingly utilized for manufacturing lightweight, high-strength components with complex geometries, supporting vehicle weight reduction strategies and advanced structural applications across automotive and aerospace industries.
Opportunity Snapshot
| Techniques | Revenue Contribution | Trend Tag | Adoption Stage |
| Roll Forming | High | Structural Profiles | Mature |
| Stretch Forming | Medium | Aerospace Frames | Scaling |
| Deep Drawing | High | Lightweight Parts | Mature |
| Stamping | High | EV Components | Mature |
| Hydroforming | Medium | Chassis Lightening | Scaling |
Metal Forming Market Growth Drivers and Impact Analysis
Expanding Automotive Production and Vehicle Lightweighting
Automotive producers across the world keep investing in lightweight automotive platforms in order to ensure efficient use of fuel, increased mileage of electric vehicles, and strict adherence to emission norms. These factors have resulted in the growing requirement for high-technology metal forming technology, which ensures the production of complex structures without any wastage of materials. The partnership between automotive original equipment manufacturers and component suppliers helps in achieving efficiency in the process and quickening production. With the increase in production of passenger cars, commercial vehicles, and electric mobility platforms in the Asia Pacific and North America, the need for high-tech precision forming machines is likely to be witnessed in the coming years.
Industrial Automation Transforming Manufacturing Productivity
Forming machines around the world have started adopting robotics, artificial intelligence, the industrial Internet of Things, and quality monitoring solutions in their operations. This technology is geared toward increasing consistency in the manufacturing process, making the operations less labor-intensive, and increasing the efficiency of equipment use while producing minimal scrap. The use of predictive maintenance has enabled companies to cut down on unplanned downtimes and maintain high efficiency. This technology also makes it possible to manufacture highly flexible customized products in various sectors like the automotive industry, aerospace sector, heavy equipment sector, and industrial equipment. As labor shortage and production costs affect manufacturers, digitally connected forming machines will play a big role.
Infrastructure Development Supporting Industrial Metal Consumption
Large-scale investments in transportation networks, renewable energy facilities, commercial construction, and public infrastructure continue to strengthen global demand for formed metal products. Bridges, rail systems, industrial buildings, transmission towers, and heavy engineering projects require precision-engineered structural components manufactured through efficient forming processes. Governments across developing economies are encouraging domestic manufacturing through industrial policies and infrastructure spending, creating favorable conditions for capacity expansion. Rising demand from construction equipment manufacturers, agricultural machinery producers, and energy infrastructure developers also strengthens equipment utilization rates for forming companies. These investments collectively improve long-term production visibility while supporting stable demand across multiple industrial end-use sectors.
Metal Forming Market Future Trends
Digital Twin Integration Across Smart Manufacturing Facilities
Digital manufacturing technologies are expected to become increasingly important as producers seek greater operational visibility and process optimization. One of the most significant metal forming market trends is the adoption of digital twins that simulate forming operations before physical production begins. These virtual production environments improve tooling design, optimize process parameters, reduce material waste, and shorten product development cycles. Integration with artificial intelligence and industrial sensors will further improve predictive maintenance capabilities, enabling manufacturers to enhance production quality while lowering operating costs and improving overall equipment effectiveness across modern manufacturing facilities.
Growing Adoption of Multi-Material Manufacturing Solutions
Manufacturers are increasingly combining steel, aluminum, and advanced alloys within a single structural assembly to balance strength, weight, and production efficiency. Future forming technologies will focus on accommodating increasingly complex material combinations while maintaining dimensional accuracy and product integrity. Growing demand from electric vehicles, aerospace structures, and renewable energy equipment is expected to accelerate investment in flexible manufacturing systems capable of processing diverse materials. These developments will encourage equipment modernization and support higher-value production across global manufacturing industries.
Metal Forming Market Opportunities
Capacity Expansion Across Emerging Manufacturing Economies
Industrial expansion across Southeast Asia, India, Eastern Europe, and parts of the Middle East presents attractive investment opportunities for equipment manufacturers and component suppliers. Government incentives, competitive labor costs, and improving industrial infrastructure continue attracting multinational manufacturers seeking supply chain diversification. Metal forming market forecasts indicate sustained investment in advanced manufacturing facilities capable of serving automotive, industrial equipment, and renewable energy sectors. Companies establishing localized production capabilities can improve customer responsiveness, reduce logistics costs, and strengthen long-term competitiveness while benefiting from expanding domestic industrial demand and export-oriented manufacturing strategies.
Advanced Lightweight Components for Electric Mobility
Electric vehicle manufacturers continue increasing demand for lightweight structural assemblies that improve battery efficiency and vehicle performance. This transition creates significant opportunities for producers specializing in hydroforming, precision stamping, and advanced aluminum processing technologies. Strategic investments in research, tooling development, and automated production systems enable suppliers to manufacture increasingly complex components meeting stringent quality and safety requirements. Long-term collaboration between material suppliers, forming specialists, and vehicle manufacturers is expected to accelerate commercialization of innovative lightweight solutions while expanding revenue opportunities across global transportation and advanced manufacturing industries.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners provided valuable market intelligence that supported our global go-to-market strategy. Their team was professional, responsive, and attentive to our feedback, providing thoughtful analysis and helpful methodological clarifications throughout the project.
Junmo Kim Chief Financial Officer (CFO), Enertech Co., Ltd.
The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for