
Micro Brushless DC Motors Market Trends, Share & Demand by 2034
Coverage: By Product (12V, 24V, Other); Application (HDD (Hard Disk Drives Spindle Motor), ODD (Optical Disk Driver Motor), Home Appliance, Other) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00023395
- Category : Electronics and Semiconductor
- No. of Pages : 150
- Available Report Formats :


- Last update date : October 13, 2026


2025 Market Size
US$ 8.37 Bn
Base year value
2034 Forecast
US$ 13.81 Bn
Projected by 2034
CAGR 2026-2034
5.72 %
Growth rate
Addressable Market
US$ 100.51 Bn
(2026-2034)
Global demand for compact, high-efficiency drive components is reshaping the Micro Brushless DC Motors Market, which stood at US$ 8.37 Billion in 2025 and is projected to reach US$ 13.81 Billion by 2034, expanding at a CAGR of 5.72% between 2026 and 2034. This trajectory reflects sustained miniaturization across consumer electronics, precision appliances, and computing peripherals, positioning brushless micro-motor technology as a critical enabler of next-generation compact device architectures worldwide.
Within this landscape, the Micro Brushless DC Motors Market size across North America is advancing steadily, supported by an estimated regional CAGR of 5.4-5.8% through 2034. Robust data infrastructure investment, growing appliance automation, and a mature electronics manufacturing base are reinforcing demand, while reshoring initiatives and stringent energy-efficiency mandates continue to encourage OEMs to adopt compact brushless motor platforms across storage devices and household equipment.
Micro Brushless DC Motors Market Assessment and Insights
- North America: The region holds an estimated 24-27% share in 2025 and is set to grow at a CAGR of 5.4-5.8% between 2026 and 2034, driven by data-center storage upgrades, appliance automation, and precision manufacturing demand across the United States and Canada.
- US: The United States accounts for roughly 80-84% of North America's revenue in 2025, expanding at a CAGR of 5.3-5.7% through 2034 on strong HDD, ODD, and smart-appliance manufacturing activity.
- Europe: Europe commands an estimated 19-22% share in 2025 and is projected to advance at a CAGR of 5.0-5.4% between 2026 and 2034, led by Germany, the UK, and France through industrial automation and precision appliance manufacturing investments.
- Asia Pacific: Asia Pacific dominates with an estimated 42-45% share in 2025, growing at a CAGR of 6.2-6.6% through 2034, led by China, Japan, and South Korea on the back of dense electronics and appliance manufacturing ecosystems.
- Largest Segment: The Home Appliance application segment leads with an estimated 43-47% market share in 2025, growing at a CAGR of 5.6-6.0% between 2026 and 2034, reflecting widespread motor integration.
- High Growth Segment: The 24V product segment is the fastest-growing category, holding an estimated 27-30% share in 2025 and advancing at a CAGR of 6.4-6.8% through 2034 amid rising power-density requirements.
- Key companies analyzed in detail: AMETEK Advanced Motion Solutions, Allied Motion Technologies Inc., NIDEC CORPORATION, Portescap, Moog Inc., Telco, MinebeaMitsumi Inc., maxon, Constar Micromotor Co., Ltd, and ORIENTAL MOTOR USA CORP.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The use of brushless micro-motor technology has seen rapid uptake following adoption of electronic commutation over brushed motors due to longer life cycle, lower maintenance and enhanced heat performance. The Micro Brushless DC Motors Market has experienced growth due to continued miniaturization in the hard disk drive, optical disc drive and home appliances where efficient torque generation and speed regulation are critical. Manufacturing dynamics have evolved from manual windings to automated winding and driver electronics, thus allowing manufacturers to increase production volume with tight tolerances for 12V and 24V micro motors.
In terms of future outlook, manufacturing investments have diversified from the East Asia region to South-East Asia and India as a result of favorable trading policies and increased capabilities in electronics assembling. Regulatory measures on energy efficiency in appliance specifications within the European Union and North America are pushing out older motor categories. Increased capital deployment towards automation, robots and intelligent appliance platforms will drive component demand going forward.
Micro Brushless DC Motors Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 8.37 Billion |
| Market Size by 2034 | US$ 13.81 Billion |
| Global CAGR (2026 - 2034) | 5.72% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Micro Brushless DC Motors Market Analysis
The factors that are driving demand in the Micro Brushless DC Motors market include growing adoption of smart home appliances, dependence on HDDs in business storage systems irrespective of competition from SSDs, and increased deployment of miniature motors in medical equipment, drones, and industrial sensors. Both consumers and Original Equipment Manufacturers (OEMs) prefer brushless motors due to their robustness, low electromagnetic interference, and longer maintenance intervals than brushed motors.
The supply chain involves suppliers of rare earth magnets and copper winding materials, makers of components, assemblers of motors, and original equipment makers of the end-device. The supply dynamics for the Micro Brushless DC Motors market can be influenced by the price of magnets used in the manufacture and the availability of semiconductors required for the integrated drive electronics, prompting some companies to adopt multiple sources and manufacture in close proximity to the market.
Nevertheless, competition is still intense with NIDEC CORPORATION and MinebeaMitsumi Inc. benefitting from economies of scale in precision small-motor production, whereas maxon and Portescap focusing on precision applications for medical and instrumentation devices. AMETEK Advanced Motion Solutions and Moog Inc. focus on customized solutions for engineered motion systems for niche markets of industrial and aerospace industries. This market for Micro Brushless DC Motors shows that differentiation in terms of pricing is being substituted by the differentiation based on winding density, electronics, and customized solutions for particular applications.
In turn, Allied Motion Technologies Inc. and Constar Micromotor Co., Ltd keep increasing their capacities in the field of production of compact motors for appliances and computer peripherals, Telco and ORIENTAL MOTOR USA CORP are intensively developing their distribution network and application engineering capabilities. In terms of investments in the Micro Brushless DC Motors Market, there is an increasing trend in automated production lines and vertically integrated magnet-to-motor manufacturing facilities.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
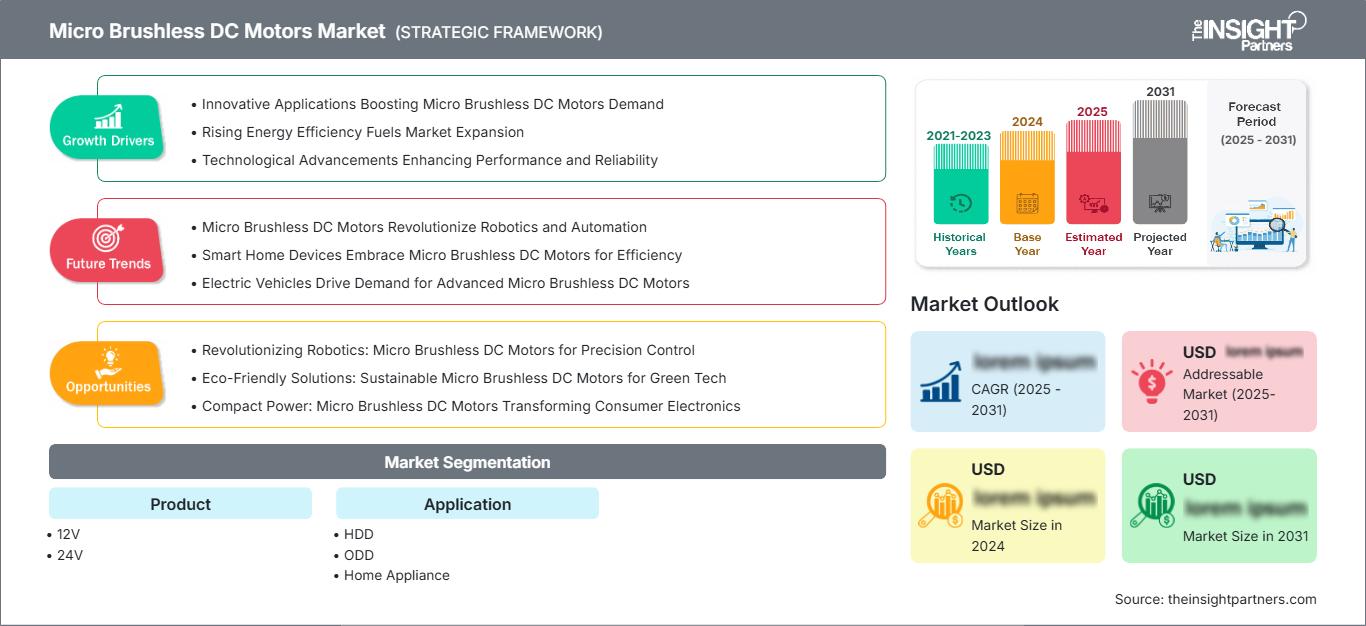
Micro Brushless DC Motors Market: Strategic Insights
Regional Insights
North America Micro Brushless DC Motors Market
North America held an estimated 24-27% Micro Brushless DC Motors Market share in 2025 and is projected to expand at a CAGR of 5.4-5.8% between 2026 and 2034. Expansion is driven by the advanced data-storage framework in place within the region, the established use of enterprise HDDs, as well as the robust appliance manufacturing base in the United States, Canada, and Mexico, which is continuing to incorporate brushless drive systems into their new product lines.
The major underlying factors are increasing automation in home appliances, high demand for precise motors in healthcare equipment and robotics, and the reshoring of electronics assembly operations owing to federal incentives in the manufacturing sector. Energy-saving regulations in various home and industrial appliance segments are driving the adoption of brushless systems by OEMs, while proximity to advanced technology developers facilitates faster customization of products.
U.S. Micro Brushless DC Motors Market
The United States represents an estimated 80-84% share of North America's compact brushless motor revenue in 2025, expanding at a CAGR of 5.3-5.7% through 2034. With the large base of enterprise data center installations, computing peripherals, and home appliance manufacturing plants within the country, there is a sustained component demand due to a strong engineering and precision motor manufacturing capability in the industrial centers located in the Midwest and Northeast.
There are several major players such as AMETEK Advanced Motion Solutions, Allied Motion Technologies Inc., and Moog Inc. that have domestic engineering centers serving medical, aerospace, and automation industries. Application trends point towards sustained HDD demand in enterprise storage along with increasing demand for smart appliance motors and robot actuators, due to preference for localization and faster product customization by U.S. OEMs.
Europe Micro Brushless DC Motors Market
Europe accounted for an estimated 19-22% share in 2025, with the market expanding at a CAGR of 5.0-5.4% between 2026 and 2034. Germany dominates regional demand, driven by its well-developed automation sector, precision engineering, and appliance manufacturing industries, whereas EU’s stringent energy-efficiency regulations on old brushed motors have only served to increase their replacements among household appliances and computing peripherals.
Stability of the UK market is provided by its strength in the manufacture of medical devices and instruments, which ensures consistent demand for precision brushless motors. Germany’s proximity to the automotive industry and automation sector serves as a base for regional production, while France, Italy, and Spain support through the manufacture of appliances and automation of packaging and robotics, all of which help position Europe as an advanced manufacturing region for brushless motors.
APAC Micro Brushless DC Motors Market
Asia Pacific led globally with an estimated 42-45% share in 2025, advancing at a CAGR of 6.2-6.6% between 2026 and 2034. China remains the leading country, supported by its expansive electronics manufacturing ecosystem, dense component supply chains, and large-scale production of HDDs, ODDs, and household appliances.
Japan and South Korea contribute advanced precision-motor engineering capabilities, while India and Australia are emerging as growing consumption markets. National industrial policies promoting electronics manufacturing localization, coupled with rising appliance penetration and data-infrastructure investment, continue to reinforce the region's dominant manufacturing and demand position.
Middle East & Africa Micro Brushless DC Motors Market
The Middle East and Africa region is advancing at an estimated CAGR of 4.6-5.0% between 2026 and 2034, with the UAE emerging as the leading market, supported by data-center expansion, smart-infrastructure investment, and growing electronics assembly activity within regional free-zone manufacturing hubs.
Saudi Arabia is scaling appliance and industrial automation investment under national diversification programs, while South Africa maintains steady demand through appliance manufacturing and mining-sector automation. The Rest of MEA region shows gradual uptake as infrastructure development and electronics import substitution initiatives expand access to compact motor technologies.
Segmentation Analysis
Product
The Product segment is projected to expand at a CAGR of 5.6-6.0% between 2026 and 2034. Within the Micro Brushless DC Motors Market scope, 12V configurations continue to dominate due to widespread compatibility with computing peripherals and household appliances, while 24V variants are gaining traction in higher-torque applications requiring greater power density, reflecting a gradual shift in end-user voltage preferences across emerging device categories.
- 12V: Widely deployed across HDDs, ODDs, and compact appliances, 12V motors remain the preferred configuration for cost-sensitive, space-constrained applications requiring reliable low-voltage torque and speed control.
- 24V: Increasingly adopted in higher-power appliance and industrial applications, 24V motors offer improved torque density and efficiency, supporting compact designs in demanding, continuous-duty operating environments.
Application
The Application segment is expected to grow at a CAGR of 5.7-6.1% between 2026 and 2034. Home Appliance applications lead demand given rising adoption of automated kitchen, cleaning, and personal-care devices, while HDD and ODD applications sustain steady volumes within enterprise storage and legacy computing peripheral markets despite gradual technology substitution pressures across certain device categories.
- HDD: Enterprise and data-center storage continue relying on brushless spindle motors for reliability and precision, sustaining stable demand despite increasing competition from solid-state storage alternatives.
- ODD: Optical disc drive applications maintain niche demand in legacy computing, archival, and specific industrial systems, with steady but gradually moderating volumes across mature device categories.
- Home Appliance: Rising automation across kitchen appliances, personal-care devices, and cleaning equipment continues to drive strong adoption of compact brushless motors for quiet, efficient, long-life operation.
Opportunity Snapshot
| Application | Revenue Contribution | Trend Tag | Adoption Stage |
|---|---|---|---|
| HDD | Medium | Enterprise Storage | Mature |
| ODD | Low | Legacy Computing | Mature |
| Home Appliance | High | Smart Appliances | Scaling |
Micro Brushless DC Motors Market Growth Drivers and Impact Analysis
Rising Adoption of Smart and Automated Home Appliances
The growing consumer acceptance of automation in kitchen appliances, cleaning equipment, and personal care appliances is generating substantial demand for miniature brushless motors in the appliances industry. The main reason behind the demand is that brushless motors are quieter, lower on maintenance, and have a higher life cycle than their brushed counterparts, which make them ideal for constant duty home appliances. Appliance companies are moving towards the use of brushless designs in order to meet the efficiency labels demanded by consumers. Such trend is becoming more common especially in regions where disposable incomes are rising, and where middle class populations are growing.
Sustained Enterprise Storage Demand Supporting HDD Motor Volumes
While there is an ongoing rise in solid-state storage solutions, data center environments remain dependent on hard disk drives (HDDs), which use cost-effective and large capacity bulk storage to ensure constant demand for accurate spindle and actuator motors. In addition, the increase in the number of data that arises from cloud computing services, videos, and enterprise analytics exceeds the economics of fully migrating to SSD storage for archival and nearline storage layers. This situation ensures steady purchases of brushless micro-motors that have high precision in their rotation and long operating lives.
Expansion of Precision Motor Applications in Medical and Industrial Devices
Beyond traditional computing and appliance uses, micro brushless motors are increasingly specified in medical devices, industrial sensors, robotics, and instrumentation systems requiring compact size, precise speed regulation, and minimal maintenance. Growing investment in portable diagnostic equipment, surgical tools, and laboratory automation is expanding addressable demand beyond conventional end markets. Industrial automation trends, including collaborative robotics and precision material handling, further broaden application scope for compact brushless drive components. This diversification reduces dependence on any single end-use category and provides manufacturers with more resilient revenue streams, as specialized applications typically command premium pricing relative to standard computing-peripheral or appliance-grade variants.
Micro Brushless DC Motors Market Future Trends
Integration of Smart Sensing and Onboard Electronics
Emerging Micro Brushless DC Motors Market trends point toward deeper integration of onboard sensors, driver electronics, and communication interfaces directly within motor housings. This convergence enables real-time diagnostics, predictive maintenance, and adaptive speed control without requiring external control modules, reducing system complexity for OEMs. As appliance and device manufacturers pursue smaller form factors and connected functionality, motors embedded with intelligent electronics are expected to command increasing design-in preference across premium appliance and precision-instrumentation categories. This trajectory is likely to reshape supplier competitiveness, favoring manufacturers that combine mechanical precision with embedded electronics expertise.
Advancement of High-Efficiency Magnet and Winding Technologies
Future product development is expected to prioritize advanced magnet formulations and optimized winding geometries that improve torque density while reducing rare-earth material intensity. Manufacturers are exploring alternative magnet compositions and refined stator designs to balance performance with material-cost volatility and supply-chain risk. This trend is likely to accelerate as sustainability expectations and material-sourcing regulations tighten across major manufacturing regions. Over the coming years, motors combining higher efficiency with reduced environmental footprint are expected to gain preference among OEMs pursuing performance differentiation and compliance with evolving material regulations.
Micro Brushless DC Motors Market Opportunities
Localization of Manufacturing Across Emerging Production Hubs
According to current Micro Brushless DC Motors Market Forecasts, manufacturers expanding production capacity across Southeast Asia and India stand to benefit from favorable labor costs, improving component supply-chain maturity, and government incentives supporting electronics manufacturing localization. Establishing regional assembly and winding facilities closer to end-device OEMs can reduce logistics costs, shorten lead times, and mitigate exposure to trade-policy volatility affecting cross-border component shipments. Companies that invest early in these emerging hubs are positioned to secure preferential OEM partnerships and long-term supply agreements as production footprints diversify away from traditional single-region concentration.
Development of Application-Specific Motor Platforms for Medical and Robotics Use
Investment in application-specific brushless motor platforms tailored for medical devices, surgical robotics, and precision instrumentation presents a meaningful opportunity for manufacturers seeking higher-margin diversification beyond commoditized computing-peripheral segments. These specialized applications demand rigorous certification, sterilization compatibility, and tight tolerance control, creating higher barriers to entry and stronger customer retention once qualified. Manufacturers investing in dedicated engineering teams and application-specific testing infrastructure can capture premium pricing and long-term design-in relationships with medical device and robotics OEMs as these end markets expand.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners provided valuable market intelligence that supported our global go-to-market strategy. Their team was professional, responsive, and attentive to our feedback, providing thoughtful analysis and helpful methodological clarifications throughout the project.
Junmo Kim Chief Financial Officer (CFO), Enertech Co., Ltd.
The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for