
Aerospace Plates Market Growth, Share & Trends by 2034
Coverage: By Material Type (Titanium, Aluminum, Steel, Others); Aircraft Type (Fixed Wing, Rotary); End User (Commercial, Military) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00024483
- Category : Aerospace and Defense
- No. of Pages : 150
- Available Report Formats :


- Last update date : October 13, 2026


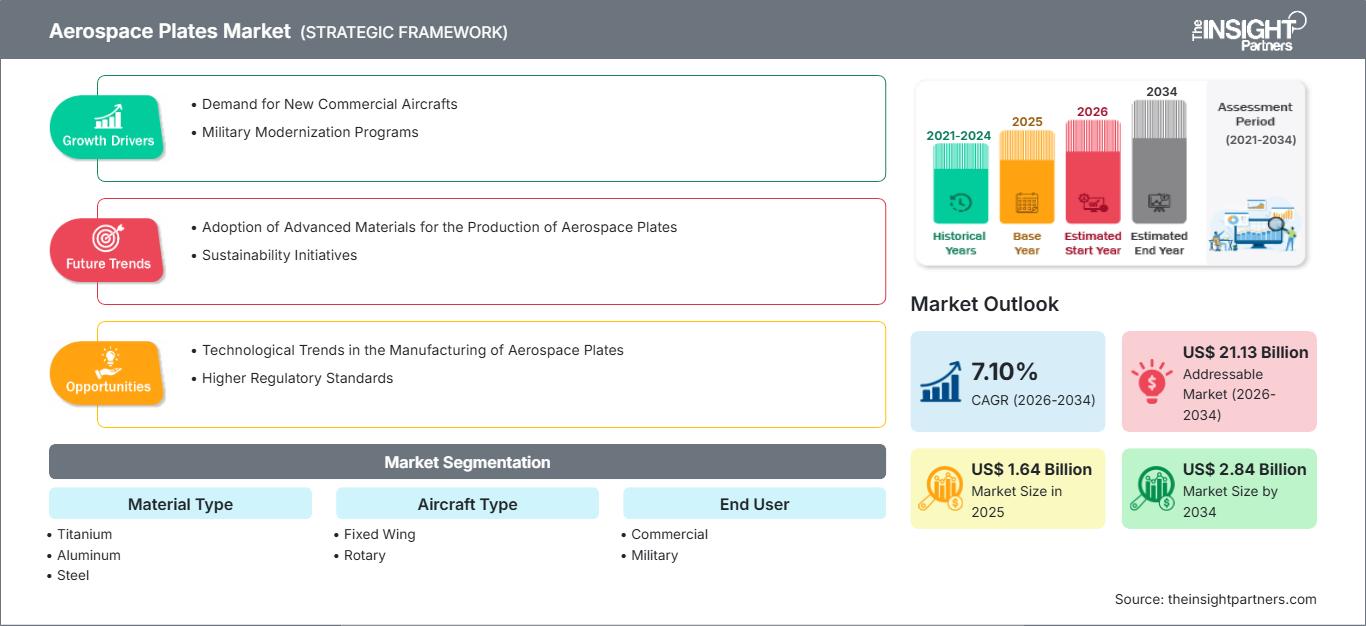
2025 Market Size
US$ 1.64 Bn
Base year value
2034 Forecast
US$ 2.84 Bn
Projected by 2034
CAGR 2026-2034
6.29 %
Growth rate
Addressable Market
US$ 20.27 Bn
(2026-2034)
The Aerospace Plates Market is accelerating due to the demand for lightweight, corrosion-resistant, and high-strength structural materials increasing across commercial and military aircraft programs. The market was valued at US$ 1.64 billion in 2025 and is projected to reach US$ 2.84 billion by 2034, expanding at a corrected CAGR of 6.29% during 2026–2034. Aerospace plates are used across airframe structures, aircraft skins, bulkheads, wing components, armor applications, and other structural assemblies where material strength, fatigue performance, machinability, and weight efficiency directly influence aircraft design and operating economics.
In North America, the aerospace plates market size is supported by established aircraft manufacturing, defense procurement, aftermarket activity, and domestic metal-processing capacity. The region is expected to expand at approximately ~5% CAGR through 2034, with demand reinforced by commercial aircraft production, military modernization, titanium supply agreements, and investments in domestic aluminum and specialty-alloy capacity. Long-term OEM contracts are also encouraging suppliers to align melting, rolling, finishing, qualification, and delivery capabilities with aircraft production schedules.
Aerospace Plates Market Assessment and Insights
Regional Outlook
- North America: ~34% of the global market in 2025 | ~5% CAGR through 2034. Market position: North America maintains the largest regional position, supported by the United States aerospace manufacturing base, defense procurement, established titanium and aluminum processing infrastructure, and long-term supply arrangements between material producers and aircraft OEMs.
- US: ~82% of North American market revenue in 2025 | ~5% CAGR through 2034. Market position: The US accounts for most North American demand because commercial aircraft production, military platforms, engine programs, and domestic specialty-metal processing create a broad requirement for qualified titanium, aluminum, and steel plate products.
- Europe: ~27% of the global market in 2025 | ~5% CAGR through 2034. Market position: Europe represents a mature aerospace manufacturing base led by France, with Germany, the UK, Italy, and Spain contributing through aircraft assembly, structural manufacturing, defense programs, and specialized metal-processing capabilities.
- Asia Pacific: ~25% of the global market in 2025 | ~8% CAGR through 2034. Market position: Asia Pacific is the fastest-growing region as aircraft fleets expand, aerospace manufacturing localizes, and China, Japan, South Korea, India, and Australia increase participation in commercial and defense aerospace supply chains.
Segment Outlook
- Aluminum: ~52% Share in 2025 | ~6% CAGR through 2034. Market position: Aluminum leads because its established aerospace qualification base, favorable strength-to-weight characteristics, corrosion resistance, machinability, and recycling potential make plate products suitable for high-volume structural aircraft applications.
- Titanium: ~25% Share in 2025 | ~8% CAGR through 2034. Market position: Titanium is the high-growth material segment as airframers increase usage in high-stress structural areas, engine-adjacent applications, and components requiring high strength, temperature resistance, fatigue performance, and corrosion resistance.
Competitive Coverage
ATI, Arconic Corporation, CRS Holdings, LLC, Constellium SE, Kaiser Aluminum Corporation, Hadco Metal Trading Co., VSMPO-AVISMA Corporation, TW Metals, LLC, Novelis Inc., Smiths Metal Centres Limited, Sandmeyer Steel Company
Methodology
The Insight Partners follows Data Collection & Secondary Research, Primary Research, Data Analysis, and Data Triangulation & Final Review to validate market estimates and insights.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The aerospace plates market has evolved from conventional aluminum and steel supply toward a more differentiated material ecosystem involving titanium alloys, aluminum-lithium products, advanced heat-treated alloys, and specialized steel grades. Platemaking operations are increasingly consolidating melting, casting, hot rolling, cold rolling, heat treating, finishing, inspection, and machining to meet aircraft certification needs. Planning is also getting coordinated better with OEM build rates. Tracing, mechanical property uniformity, surface finish, tolerances, and certification will hence be essential elements of supplier competitiveness, not merely quality control steps down the line.
In the coming years, the market will diversify geographically with aircraft production increasing in the Asia Pacific region, along with the development of aerospace manufacturing infrastructure in emerging countries. Investments in domestic strategic material production capacities will also gain importance in view of the need for robust titanium and high-performance aluminum supplies by OEMs and governments. The regulation of emissions, material efficiency, recycling, and resilience is encouraging investments in reduced environmental impact production technologies, scrap recycling facilities, and higher added value alloys. This will help demand for qualified plating in new-builds, defense platforms, and replacement programs.
Aerospace Plates Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 1.64 Billion |
| Market Size by 2034 | US$ 2.84 Billion |
| Global CAGR (2026 - 2034) | 6.29% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Aerospace Plates Market Analysis
The aerospace plates market is driven by aircraft production, fleet renewal, defense modernization, and the increasing use of lightweight materials in structural applications. Large amounts of qualified aluminum plate and other rolled product materials are required in commercial airframe production, whereas the use of titanium plate depends on high-performance structures and situations where the weight/strength ratio makes more expensive materials worthwhile. The supply chain includes alloys suppliers, melt shops, rolling mills, heat treat plants, distributors, machinists, and aircraft Original Equipment Manufacturers (OEMs). The supply process is still impacted by the lead time for qualification, alloy availability, mill capacity, aerospace certifications, and procurement contracts.
Supply concentration in qualified aerospace materials makes production expansion a strategic consideration for manufacturers. ATI’s 2025 agreement with Airbus illustrates how multi-year commitments can support capacity planning for titanium plate, sheet, and billet. Constellium combines aerospace aluminum plate, sheet, and extrusion capabilities with customer-specific alloy development, while Arconic maintains significant aluminum processing capabilities serving aerospace and defense applications. Kaiser Aluminum, VSMPO-AVISMA, TW Metals, Novelis, Smiths Metal Centers, Hadco Metal Trading, Sandmeyer Steel Company, and CRS Holdings participate across complementary material, distribution, and specialty-metal positions.
Investment trends towards vertical integration, flexibility, automation, recycling and qualification of advanced alloys. Material suppliers who operate through various processes from melting to fabricated plate increase the consistency of materials and visibility of deliveries, while distributors provide value through availability of stock, cutting, machining and regional distribution. Aerospace Plates market share will be affected by such competencies because competitive advantage does not depend solely on capacity. Also, aerospace clients look for such characteristics as qualifications, alloy types, quality systems, delivery dependability, traceability and the capability of adjusting production rates without breaching specifications.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Aerospace Plates Market: Strategic Insights
Regional Insights
North America Aerospace Plates Market
North America represented approximately ~34% of the global aerospace plates market in 2025 and is expected to register a ~5% CAGR through 2034. The region’s strengths are the presence of aircraft original equipment manufacturers (OEMs), defense OEMs, engine manufacturers, MRO companies, and metal producers. The US represents the major part of the demand in the region, where commercial aircraft structures, military aircraft, helicopters, and space programs present a wide range of demands for aluminum, titanium, and specialty steel plates.
The resilience of the domestic supply chain becomes an increasingly significant criterion for purchase decisions. Aerospace materials suppliers are making investments in capacity, processing, and long-term contracts for the sake of supporting the aircraft and defense productions. Titanium is still strategic due to its application in load-bearing constructions and engine parts, whereas advanced aluminum keeps its relevance for high-volume airframe applications. Canada makes contributions to aircraft structures, business jets, and specialized aerospace production, whereas Mexico supports some aerospace manufacturing operations.
U.S. Aerospace Plates Market
The US accounted for approximately ~82% of the North American aerospace plates market revenue in 2025 and is projected to expand at a ~5% CAGR through 2034. Demand in the country is based on commercial aircraft, fighters, helicopters, transport planes, business jets, spacecrafts, and aerospace aftermarket structures. Aerospace industry clusters lead to consistent demand for high-quality plate material, which requires strict mechanical, dimensional, and surface requirements.
Security of material supply has increasingly become associated with defense policies and aerospace production plans. ATI diversified its titanium range in South Carolina and entered into a multi-year agreement with Airbus that covers titanium plates, sheets, and billets, highlighting the significance of having the capacity for domestic processing of the material. Suppliers such as Arconic, Constellium, Kaiser Aluminum, TW Metals, and others help the market with their supply of aluminum plate, specialty alloys, processing, and distribution.
Europe Aerospace Plates Market
Europe held approximately ~27% of the global aerospace plates market in 2025 and is expected to record a ~5% CAGR through 2034. France leads Europe in the industry due to the country’s aircraft and aerospace manufacturing base, including Airbus manufacturing operations, engines and systems production, and aerospace materials supply chain. Germany is contributing to the aerospace market with aircraft structures, engine parts, defense programs, and advanced manufacturing. The UK still plays an important role due to its commercial and military aerospace manufacturing. Meanwhile, Italy and Spain have strengths in structural, aerostructures, and aircraft program competencies.
The region is developing its circularity and higher-performing alloys solutions. Constellium is offering aerospace aluminum plates and other aerospace rolled products in Europe, while aluminum-lithium technology from Constellium focuses on weight reduction and structural properties. Aerospace OEMs have very close integration with specialty materials suppliers in France, whereas Germany and Italy have diversified aerospace engineering and manufacturing ecosystems. Spain is increasing its contribution to aerostructures and aircraft program components. The UK keeps its importance for engines, defense aviation, and aerospace manufacturing. Qualification, recycling, traceability, and supply chain robustness are affecting material purchasing choices in Europe.
APAC Aerospace Plates Market
Asia Pacific represented approximately ~25% of the global aerospace plates market in 2025 and is projected to expand at a ~8% CAGR, making it the fastest-growing region. The Aerospace Plates Market Forecast indicates continued regional growth, with China leading Asia Pacific, supported by commercial aviation demand, domestic aircraft development, defense production, and expanding aerospace manufacturing capacity. Japan and South Korea contribute through aircraft components, advanced materials, defense systems, and industrial technology.
The growing significance of India can be attributed to the rising airline fleet expansion, aircraft maintenance work, and localization of aerospace manufacturing. The contribution of Australia to this sector includes its involvement in defense aerospace, MRO services, and specialty manufacturing. The growth within this region is due to the rising aviation fleets, localization activities, supply chain management, and investments in aerospace industry infrastructure. There will be an increased demand for aluminum and titanium plates.
Middle East & Africa Aerospace Plates Market
The Aerospace Plates Market Trends in the Middle East and Africa indicate increasing demand supported by aviation infrastructure development, aerospace investment, defense modernization, and expanding MRO activities. The regional market is expected to expand at approximately ~6% CAGR through 2034. The UAE represents a leading market because of its aviation hubs, large airline fleets, MRO capabilities, aerospace investment, and role as a regional center for aircraft services. The Kingdom of Saudi Arabia is investing in aerospace and defense sectors as part of its strategy to diversify industries, and South Africa continues to have the ability in defense, aviation and aerospace engineering.
Demand in the region will be driven by growth in aircraft fleets, maintenance facilities, defense purchases, and airport construction. The Gulf States have been developing aerospace industries locally, thus opening up possibilities for distributors, machining firms, and material suppliers. South Africa offers specialization in aerospace production and defense, while other parts of the region continue to rely heavily on imports for aircraft materials.
Segmentation Analysis
Material Type
The Material Type segment is structured around Titanium, Aluminum, Steel, and Others. Aluminum remains the largest material category, while titanium is the fastest-growing major material because aircraft designers increasingly balance structural performance, weight, corrosion resistance, and lifecycle requirements. The material mix also varies according to aircraft platform, structural location, operating environment, and end-user requirements.
- Titanium: Titanium plates serve demanding structural and high-temperature applications where high strength-to-weight performance, corrosion resistance, and fatigue characteristics are important. Demand is closely connected with commercial aircraft production, defense platforms, and applications requiring compatibility with advanced airframe and propulsion systems.
- Aluminum: Aluminum plates remain central to aircraft structural manufacturing because of established qualification practices, machinability, corrosion resistance, and favorable weight characteristics. Advanced alloys and aluminum-lithium products are extending aluminum's relevance in lighter and more efficient next-generation structures.
- Steel: Steel plates are used selectively where strength, wear resistance, durability, or specific mechanical properties outweigh aluminum's weight advantages. Demand is concentrated in specialized structural, landing-system, defense, tooling, and heavy-duty aerospace applications.
- Others: Others encompass specialized aerospace alloys and materials serving applications where conventional aluminum, titanium, or steel cannot fully meet performance requirements. Their strategic role is linked to niche aircraft structures, advanced manufacturing, and specialized defense applications.
Aircraft Type
The Aircraft Type segment comprises Fixed Wing and Rotary aircraft. Fixed-wing aircraft represent the broader demand base because commercial and military airplanes require extensive structural plate products across wings, fuselage structures, bulkheads, and related assemblies. The segment is expected to expand at approximately ~6% CAGR through 2034 as fleet renewal and production programs continue.
- Fixed Wing: Fixed Wing aircraft generate substantial plate consumption through large structural assemblies and repeated production programs. Commercial narrowbody, widebody, regional, business, and military aircraft create differentiated material requirements depending on aircraft size, design philosophy, production rate, and structural application.
- Rotary: Rotary aircraft require plate materials for airframe structures, transmission-related applications, military platforms, and specialized components. Demand is supported by helicopter modernization, defense procurement, utility aircraft, and replacement cycles, with titanium and specialty alloys relevant in demanding operating environments.
End User
The End User segment consists of Commercial and Military applications. Commercial aviation represents the larger established demand base because high-volume aircraft production requires recurring purchases of qualified aluminum and titanium plate products. The segment is expected to grow at approximately ~6% CAGR through 2034, supported by fleet expansion and replacement activity.
- Commercial: Commercial aerospace users require a consistent plate supply for high-volume aircraft production, structural assemblies, and aftermarket requirements. Purchasing decisions emphasize certification, dimensional consistency, delivery reliability, weight efficiency, and compatibility with established aircraft manufacturing processes.
- Military: Military users require high-performance plates for fighter aircraft, helicopters, transports, surveillance platforms, and other defense systems. The segment is expected to expand at approximately ~8% CAGR, supported by modernization programs, fleet replacement, survivability requirements, and strategic domestic sourcing.
Opportunity Snapshot
| End User | Revenue Contribution | Trend Tag | Adoption Stage |
|---|---|---|---|
| Commercial | High | Fleet Renewal | Mature |
| Military | Medium | Defense Modernization | Scaling |
Aerospace Plates Market Growth Drivers and Impact Analysis
Rising Commercial Aircraft Production and Fleet Renewal
Aircraft manufacturing is an example of a demand driver since each and every airframe requires certification of structural materials, ranging from wings, fuselage segments, frames, bulkheads, and other components. Increased aircraft utilization and fleet turnover necessitate continuous material demand. There continues to be demand for aluminum in large volume structural applications, but titanium is being chosen more often in those cases where superior strength, corrosion resistance and performance by weight are needed. Demand drivers include the entire value chain since increased OEM production rates mean that plate producers must have the capability to provide consistent and sufficient melt, rolling, heat treatment, finishing, and testing capability. Long-term agreements can help mitigate risk and encourage investment in aerospace-specific capabilities.
Defense Modernization and Strategic Material Security
Defense modernization creates a second demand channel because fighter aircraft, military transports, helicopters, surveillance platforms, and other defense systems require durable materials capable of meeting demanding mechanical and environmental specifications. Governments are increasingly attentive to domestic access to strategic materials, particularly titanium and high-performance aluminum. This encourages investment in melting, rolling, processing, and recycling infrastructure while increasing the importance of local supply-chain resilience. Military programs also have longer production and sustainment cycles than many commercial applications, providing a recurring requirement for qualified materials and replacement components. The market impact is visible in investments designed to increase domestic material availability and processing capability. Suppliers with established defense qualifications, traceability systems, and flexible production platforms are positioned to address procurement requirements across new-build and sustainment programs.
Weight Reduction and Advanced Alloy Adoption
Aircraft manufacturers continuously seek structural weight reduction without compromising fatigue life, durability, or manufacturability. This requirement is increasing interest in aluminum-lithium products, advanced aluminum alloys, titanium grades, and other specialized materials. Plate producers, therefore, compete increasingly on alloy performance and processing precision rather than commodity metal availability alone. Higher-performance alloys can support thinner structures, improved corrosion behavior, or enhanced fatigue characteristics, depending on application and design requirements. The resulting shift affects research and development, qualification, machining, recycling, and supply-chain planning. Manufacturers that can develop alloys alongside aircraft customers can shorten the transition from laboratory development to qualified production. This trend also encourages closer technical collaboration between material producers, OEM engineering teams, and downstream fabricators.
Aerospace Plates Market Future Trends
Expansion of Circular Aerospace Material Systems
The aerospace plates market is likely to see greater integration of recycled material streams into qualified production as aircraft manufacturers and material suppliers seek lower-impact manufacturing pathways. Aluminum is particularly suited to circularity because production scrap can be collected, sorted, remelted, and returned to aerospace material streams when chemistry and traceability requirements are satisfied. Closed-loop systems can reduce dependence on primary material while improving resource efficiency. Titanium recycling is also gaining strategic relevance as manufacturers seek to recover high-value machining scrap and improve material utilization. Future development will depend on alloy segregation, certification procedures, traceability, contamination control, and customer acceptance. Suppliers that build recycling into their manufacturing systems can strengthen raw-material efficiency while responding to aircraft manufacturers' sustainability requirements.
Advanced Alloy Platforms and Digital Qualification
Future material development will increasingly combine advanced alloy design with digital process control, automated inspection, and data-based qualification. Aerospace plate producers are likely to use improved modeling and manufacturing controls to optimize rolling schedules, heat treatment, surface quality, and mechanical consistency. Aluminum-lithium alloys and high-performance titanium grades will remain important where designers seek improved structural efficiency. Digital traceability can also strengthen material genealogy from melt through finished plate and downstream fabrication. Faster access to reliable process data may help reduce qualification bottlenecks for new alloys, although aerospace certification requirements will continue to impose rigorous testing. The trend creates opportunities for producers that integrate metallurgical expertise with automation, quality analytics, and customer-specific engineering support.
Aerospace Plates Market Opportunities
Localized Titanium and High-Performance Alloy Capacity
Expansion of localized titanium and advanced-alloy capacity presents an opportunity for producers seeking closer alignment with aircraft OEMs and defense customers. Demand for qualified titanium products is supported by commercial aircraft production, military modernization, and applications requiring high strength and corrosion resistance. New capacity can create value when it is paired with long-term customer commitments, integrated melting and rolling capabilities, and aerospace qualification. Producers can also improve competitiveness by offering multiple product forms and downstream processing rather than relying solely on standard plate sales. Regional capacity development is particularly relevant where governments seek stronger domestic access to strategic materials. Investment priorities include melt quality, large-format rolling, heat treatment, automated inspection, finishing, and digital traceability.
Recycling and Value-Added Plate Processing
Recycling and value-added processing provide another commercial opportunity because aerospace customers increasingly require material efficiency without sacrificing certification or performance. Suppliers can move beyond primary plate production by providing cut-to-size products, pre-machined components, surface finishing, inventory management, and closed-loop scrap recovery. Such services can reduce material waste at the customer level and strengthen supplier integration into aircraft manufacturing workflows. Aluminum is particularly attractive for circular models, while titanium scrap recovery can improve utilization of a high-value material. Companies that combine certified plate production with machining, recycling, inventory, and technical support can capture more value from each customer relationship. The opportunity is strongest where aerospace clusters support recurring production volumes and reliable reverse-logistics systems.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners provided valuable market intelligence that supported our global go-to-market strategy. Their team was professional, responsive, and attentive to our feedback, providing thoughtful analysis and helpful methodological clarifications throughout the project.
Junmo Kim Chief Financial Officer (CFO), Enertech Co., Ltd.
The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for