
Artificial Intelligence Software Market Size, Share & Trends by 2034
Coverage: By Technology (Natural Language Processing (NLP), Computer Vision, Machine Learning); End Users (Automotive, BFSI, IT and Telecom, Media and Entertainment, Healthcare, Retail, Manufacturing, Government, Others) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00005012
- Category : Technology, Media and Telecommunications
- No. of Pages : 150
- Available Report Formats :


- Last update date : September 01, 2026


2025 Market Size
US$ 160.19 Bn
Base year value
2034 Forecast
US$ 1,159.09 Bn
Projected by 2034
CAGR 2026-2034
24.59 %
Growth rate
Addressable Market
US$ 5,059.32 Bn
(2026-2034)
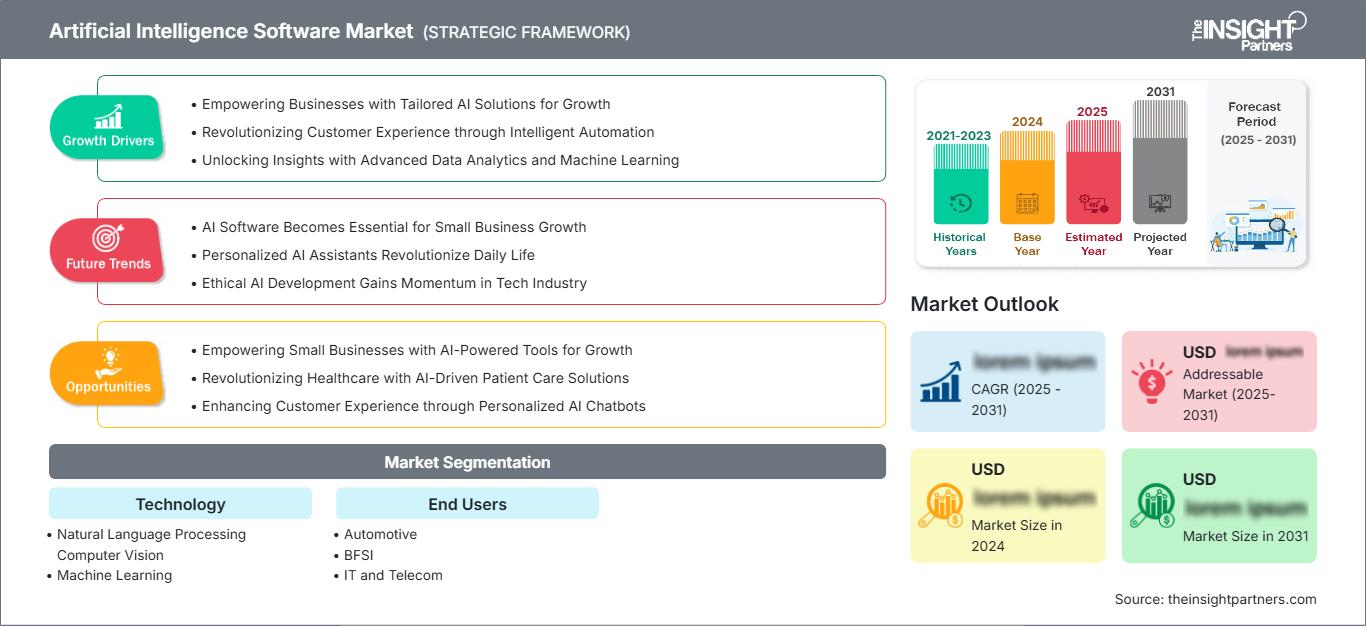
The Artificial intelligence software market was valued at US$ 160.19 Billion in 2025 and is projected to reach US$ 1,159.09 Billion by 2034, expanding at a CAGR of 24.59% during 2026–2034. Rapid enterprise digital transformation, accelerating deployment of intelligent automation platforms, and wider integration of generative artificial intelligence across business workflows continue to reshape software development priorities. Increasing investments in scalable cloud infrastructure, data-driven decision making, and AI-enabled applications across industries are strengthening long-term commercial prospects for the artificial intelligence software market.
Across North America, enterprise modernization initiatives, advanced cloud ecosystems, and substantial investments in artificial intelligence infrastructure continue to create favorable conditions for adoption. The artificial intelligence software market size in the region is supported by strong research ecosystems, early commercial deployment of foundation models, and expanding enterprise spending on automation, cybersecurity, and predictive analytics. Regional demand is expected to advance at a CAGR ranging between 23.5% and 25.5% through 2034.
Artificial Intelligence Software Market Assessment and Insights
- North America: Accounted for 36–40% share in 2025 and is projected to expand at a CAGR of 23.5–25.5% during 2026–2034, supported by hyperscale cloud infrastructure, advanced semiconductor capabilities, and widespread enterprise AI deployment across financial services, healthcare, and manufacturing.
- US: Represented 78–82% of North American revenue in 2025 and is anticipated to register a CAGR of 23.8–25.8% through 2034, driven by large-scale enterprise investments, AI research commercialization, and extensive public and private funding.
- Europe: Held 24–28% share in 2025 and is forecast to grow at a CAGR of 22.5–24.5% during 2026–2034, with Germany, the UK, and France leading adoption through industrial automation, responsible AI initiatives, and digital transformation policies.
- Asia Pacific: Captured 26–30% share in 2025 and is expected to record the fastest regional expansion at a CAGR of 26.5–28.5% during 2026–2034, supported by rapid cloud adoption across China, Japan, South Korea, and India.
- Largest Segment: Machine Learning accounted for an estimated 42–46% market share in 2025 and is projected to grow at a CAGR of 24.0–25.5%, supported by widespread deployment in predictive analytics, recommendation engines, and intelligent automation.
- High Growth Segment: Healthcare is expected to record the strongest expansion, representing 11–15% market share in 2025 while advancing at a CAGR of 27.5–29.5%, driven by diagnostic support, clinical decision intelligence, and operational optimization.
- Key companies analyzed in detail: Alphabet Inc., Cisco Systems, Inc., IBM Corporation, Intel Corporation, IPsoft Inc., Microsoft Corporation, NVIDIA Corporation, Oracle Corporation, Siemens AG, AMD, Inc. (through the Xilinx business).
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
AI software functionality keeps developing from predictive analytics to multimodal reasoning, automation of workflows, and vertical-specific intelligence. The steady progress in graphics processing hardware, cloud native AI development platforms, open-source AI development platforms, and enterprise orchestration solutions has resulted in simplifying deployment processes. Explainability, governance, and optimization are gaining more importance in addition to computing efficiency due to rising needs for generative and agentic AI applications in regulated industries.
The future growth of the market is likely to be driven by sovereign AI programs, regional semiconductor investments, enterprise governance programs, and industry-specific AI platforms. Developing economies are building up their AI ecosystems by means of digital infrastructure investments and research. Regulatory trends promote responsible AI deployment. Further cooperation between software vendors, hyperscale cloud operators, semiconductor companies, and enterprise customers will foster AI commercialization.
Artificial Intelligence Software Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 160.19 Billion |
| Market Size by 2034 | US$ 1,159.09 Billion |
| Global CAGR (2026 - 2034) | 24.59% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Artificial Intelligence Software Market Analysis
Growing enterprise demand for automation, intelligent decision support, and generative AI applications is accelerating artificial intelligence software market growth across multiple industries. The use of AI in customer interaction, software development, cybersecurity, logistics, and finance analytics is becoming a common trend that helps organizations enhance their efficiency and resilience. The expansion of digital transformation programs and the growing number of cloud migrations, as well as the availability of high-performance computing infrastructure, drive further growth in this area.
The ecosystem of the market includes semiconductor companies, hyperscale cloud service providers, AI platform developers, application software providers, system integrators, and consulting firms. Improvements in foundation models, APIs, and low-code AI development tools reduced the time-to-market of solutions and helped enterprises create scalable solutions. At the same time, regulatory emphasis on responsible AI, data governance, and cybersecurity encourages vendors to integrate explainability, monitoring, and compliance capabilities into commercial software offerings.
Competitive intensity within the artificial intelligence software market analysis reflects continuous innovation across enterprise platforms, infrastructure software, and AI services. Microsoft Corporation and Alphabet Inc. continue expanding generative AI ecosystems through cloud-native services, while NVIDIA Corporation strengthens its leadership through accelerated computing platforms supporting large language model training and inference. IBM Corporation focuses on enterprise AI governance and hybrid cloud integration, whereas Oracle Corporation continues to embed AI capabilities throughout enterprise resource planning and database platforms.
There is a growing trend for strategic investments to focus on specialized foundations, industry-specific AI solutions, edge computing, and agent-based AI systems. The network and cybersecurity AI solutions by Cisco Systems, Inc., the deployment of industrial AI in the manufacturing sector by Siemens AG, advanced AI acceleration by Intel Corporation, and enterprise conversational intelligence from IPsoft Inc. are all expected to contribute to faster commercialization.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Artificial Intelligence Software Market: Strategic Insights
Regional Insights
North America Artificial Intelligence Software Market
North America accounted for 36–40% of the artificial intelligence software market share in 2025 and is projected to expand at a CAGR of 23.5–25.5% during 2026–2034. Advantages that the region enjoys include modern digital infrastructure, enterprise cloud computing, active venture capital investment, and continuous funding of artificial intelligence studies. The demand is driven by the early adoption of generative AI, increased adoption of intelligent automation, and investments in data centers able to support AI computing.
Vendors of technology keep on building up their AI-powered software portfolio in enterprise productivity, cybersecurity, customer experience, and operations optimization areas. Government programs advocating responsible AI development, coupled with private investments in foundation models and semiconductors, help the region build up its competitive advantage. Leading adopters of AI include financial services, healthcare, manufacturing, retail, and telecommunications sectors. Collaboration among cloud providers, researchers, and enterprises keeps on advancing commercial applications of artificial intelligence software.
U.S. Artificial Intelligence Software Market
The U.S. represented 78–82% of North American revenue in 2025 and is expected to register a CAGR of 23.8–25.8% through 2034. This nation continues to be the largest in terms of innovation when it comes to AI software since there is the existence of hyperscale cloud service providers, semiconductor firms, AI startups, and renowned technology companies. Investments in generative AI technology infrastructure, software upgrades, and commercializing research continue to fuel the growth of the market in most of the industries that exist today.
Many companies in the health care, BFSI, retail, government, defense, and manufacturing industries, among others, are increasingly adopting AI platforms to perform predictive analysis, intelligent document processing, fraud detection, and software development automation. This is attributed to the presence of prominent technology companies such as Microsoft Corporation, Alphabet Inc., Oracle Corporation, NVIDIA Corporation, IBM Corporation, Cisco Systems, Inc., Intel Corporation, among others.
Europe Artificial Intelligence Software Market
Europe accounted for 24–28% of the global Artificial Intelligence Software Market in 2025 and is forecast to grow at a CAGR of 22.5–24.5% during 2026–2034. Germany continues to lead regional adoption through Industry 4.0 initiatives, industrial automation, and intelligent manufacturing software deployments. The country also benefits from extensive investment in industrial AI research, digital engineering platforms, and enterprise cloud transformation supporting automotive, machinery, and advanced manufacturing industries.
The UK continues to be a significant player due to robust fintech ecosystems, AI venture capital funding, and the rising use of generative AI in finance, healthcare, legal services, and professional consulting. The ongoing support for innovation through government-led programs and increased private investments is reinforcing the process of commercialization of these technologies, while fostering proper governance of AI technologies in regulated sectors.
France, Italy, and Spain are progressively scaling their enterprise AI adoption through smart manufacturing, healthcare IT solutions, retail IT innovations, and government digital transformations. Increased spending on national AI capabilities, cloud technology, and data governance structures is driving competitiveness in this region. The continued adoption of AI regulations further drives the responsible development of software while ensuring enterprise readiness to adopt AI-driven solutions.
APAC Artificial Intelligence Software Market
Asia Pacific captured 26–30% of the global Artificial Intelligence Software Market revenue in 2025 and is projected to register the highest regional CAGR of 26.5–28.5% during the forecast period. China leads regional deployment through extensive AI investments, followed by Japan, South Korea, and India, where enterprise automation and digital transformation programs continue expanding rapidly.
Government initiatives supporting semiconductor manufacturing, AI research, cloud infrastructure, and industrial digitization continue to strengthen regional competitiveness. Australia also records growing enterprise adoption across healthcare, mining, banking, and education, contributing to broader regional expansion driven by increasing digital infrastructure investment.
Middle East & Africa Artificial Intelligence Software Market
The Middle East & Africa market is projected to expand at a CAGR of 21.0–23.0% during 2026–2034. Saudi Arabia and the UAE continue making extensive investments in their national AI strategies, smart city projects, digital government offerings, and cloud platforms. South Africa continues to be a key technology center for the region, facilitating finance and enterprise software implementations.
Energy diversification plans, digital infrastructure upgrades, and innovation initiatives in the public sector continue to drive the adoption of AI software solutions across the region. Increasing investments in intelligent transportation, digitization of the healthcare sector, cybersecurity, and automation of industries are anticipated to drive future market growth in the Rest of the Middle East & Africa.
Segmentation Analysis
Technology
The Technology segment is projected to expand at a CAGR of 24.8–26.2% during 2026–2034. Continuous advances in computing infrastructure, foundation models, and enterprise AI platforms are accelerating technology adoption across industries. The artificial intelligence software market scope continues to broaden as organizations increasingly combine multiple AI technologies to automate workflows, improve decision-making, enhance customer experiences, and support intelligent business operations across cloud and edge environments.
- Natural Language Processing – Natural language processing remains a core technology supporting conversational AI, intelligent document processing, virtual assistants, multilingual translation, and enterprise knowledge management. Increasing deployment across customer service, banking, healthcare, and legal industries continues to strengthen commercial adoption.
- Computer Vision – Computer vision technology supports automated quality inspection, facial recognition, autonomous mobility, medical imaging, and intelligent surveillance. Expanding industrial automation and smart manufacturing initiatives continue driving implementation across automotive, healthcare, retail, logistics, and public safety applications.
- Machine Learning – Machine learning represents the largest technology category, enabling predictive analytics, fraud detection, recommendation engines, demand forecasting, and intelligent automation. Continuous improvements in model training, explainability, and cloud-based deployment platforms support sustained enterprise investment.
End Users
The End Users segment is expected to register a CAGR of 25.2–26.8% during 2026–2034 as organizations across diverse industries accelerate digital transformation initiatives. Enterprise demand for intelligent automation, predictive analytics, cybersecurity, customer engagement, and operational optimization continues to expand the adoption of AI software. Industry-specific platforms and cloud-native AI services are enabling broader commercialization while reducing implementation complexity across organizations of varying sizes.
- Automotive – Automotive companies deploy AI software for autonomous driving development, predictive maintenance, intelligent manufacturing, connected mobility, and supply chain optimization, supporting greater operational efficiency and enhanced customer experiences.
- BFSI – Financial institutions increasingly utilize AI for fraud detection, regulatory compliance, credit scoring, customer service automation, anti-money laundering, and risk management, improving operational resilience and customer engagement.
- IT and Telecom – AI software strengthens network optimization, cybersecurity, predictive maintenance, customer support automation, and intelligent resource allocation, enabling operators to improve service quality while reducing operational costs.
- Media and Entertainment – Media organizations leverage AI for personalized content recommendations, automated content creation, audience analytics, advertising optimization, and digital asset management to improve viewer engagement and operational productivity.
- Healthcare – Healthcare providers adopt AI software for medical imaging, clinical decision support, patient monitoring, drug discovery, hospital workflow optimization, and personalized treatment planning, making it the fastest-growing end-user industry.
- Retail – Retail companies implement AI solutions for demand forecasting, inventory optimization, dynamic pricing, recommendation engines, customer analytics, and omnichannel commerce management, improving operational efficiency and consumer satisfaction.
- Manufacturing – Manufacturers utilize AI software to enable predictive maintenance, quality inspection, production scheduling, industrial robotics, and intelligent supply chain management, supporting higher productivity and reduced operational downtime.
- Government – Government agencies increasingly deploy AI solutions for public administration, digital citizen services, cybersecurity, defense intelligence, infrastructure management, and smart city initiatives while emphasizing transparency and responsible AI governance.
Opportunity Snapshot
| End Users | Revenue Contribution | Trend Tag | Adoption Stage |
|---|---|---|---|
| Automotive | High | Autonomous Mobility | Scaling |
| BFSI | High | Fraud Analytics | Mature |
| IT and Telecom | High | Network AI | Mature |
| Media and Entertainment | Medium | Content Generation | Scaling |
| Healthcare | High | Clinical AI | Scaling |
| Retail | High | Smart Commerce | Mature |
| Manufacturing | High | Industrial AI | Mature |
| Government | Medium | Digital Governance | Emerging |
Artificial Intelligence Software Market Growth Drivers and Impact Analysis
Expansion of Enterprise Generative AI Deployments
There has been increased adoption of generative AI technology among enterprises as they look for ways of increasing efficiency in productivity, generating content automatically, intelligent software development, and improved customer interaction. Enterprises are implementing the use of foundational models within their enterprise applications for the purpose of automating certain processes, improving decision-making and employee efficiency. Cloud providers are continually rolling out AI infrastructure, which helps in making deployment of AI solutions easier as well as supporting inference and training of models on a large scale. With enterprises putting in place governance structures for responsible AI implementation, there is increased integration of explainability, security and compliance in vendor-based AI software solutions.
Increasing Investment in Cloud and High-Performance Computing Infrastructure
Rapid expansion of hyperscale data centers and accelerated investment in graphics processing units, AI accelerators, and cloud-native computing environments are enabling organizations to deploy increasingly sophisticated artificial intelligence applications. High-performance computing supports training of larger language models, real-time analytics, computer vision, and intelligent automation at enterprise scale. Cloud service providers continue expanding dedicated AI infrastructure while improving energy efficiency and workload optimization. Governments and private investors are simultaneously supporting semiconductor manufacturing and digital infrastructure development, reducing computational bottlenecks. These investments improve software scalability, shorten deployment timelines, and enable organizations of different sizes to commercialize AI-enabled solutions without maintaining extensive on-premise infrastructure.
Growing Adoption Across Regulated and Mission-Critical Industries
Artificial intelligence software is increasingly deployed within highly regulated industries where operational accuracy, security, and compliance are essential. Healthcare organizations use AI to improve diagnostics and patient management, while financial institutions enhance fraud detection and risk assessment through machine learning. Manufacturing companies optimize production quality and predictive maintenance using intelligent automation. Government agencies adopt AI for cybersecurity, public administration, and digital service delivery while implementing governance standards that encourage responsible deployment. As regulatory frameworks mature and explainable AI capabilities improve, enterprise confidence continues to strengthen. The combination of compliance readiness and measurable productivity gains supports sustained long-term investment across mission-critical business environments.
Artificial Intelligence Software Market Future Trends
Rise of Agentic AI and Autonomous Enterprise Workflows
The next phase of artificial intelligence software market trends will be shaped by autonomous AI agents capable of completing complex business workflows with minimal human intervention. Organizations are expected to deploy intelligent software capable of planning tasks, retrieving enterprise knowledge, coordinating applications, and executing business processes independently. These capabilities will transform customer service, software engineering, financial operations, supply chain management, and enterprise productivity while increasing demand for orchestration platforms, governance frameworks, and secure enterprise-grade AI deployment environments.
Industry-Specific Foundation Models Gain Commercial Importance
Organizations increasingly prefer specialized AI models trained for healthcare, banking, manufacturing, legal services, engineering, and scientific research rather than relying solely on general-purpose foundation models. Domain-specific intelligence improves regulatory compliance, prediction accuracy, and operational efficiency while reducing implementation risks. Software vendors are expected to introduce configurable enterprise AI platforms supporting secure proprietary data integration, explainable decision-making, and industry-specific workflows. This transition will strengthen commercial adoption among highly regulated industries requiring greater transparency, accuracy, and governance.
Artificial Intelligence Software Market Opportunities
Expansion of AI Platforms for Small and Medium Enterprises
The growing availability of low-code AI development platforms creates significant commercial opportunities beyond large enterprises. Cloud-native subscription models reduce implementation costs while enabling small and medium businesses to adopt predictive analytics, intelligent customer engagement, cybersecurity automation, and workflow optimization. Vendors introducing scalable pricing strategies, simplified deployment tools, and industry-focused solutions will strengthen competitive positioning. Artificial intelligence software market Forecasts indicate increasing adoption among resource-constrained organizations seeking measurable productivity improvements without extensive in-house AI expertise, creating substantial opportunities for platform providers, cloud vendors, and implementation partners.
Growing Investment in Sovereign AI Infrastructure
National governments continue investing in domestic AI infrastructure, semiconductor manufacturing, sovereign cloud capabilities, and research ecosystems to strengthen technological independence. These initiatives create long-term opportunities for enterprise software providers, cloud platform developers, cybersecurity vendors, and AI infrastructure companies. Organizations capable of delivering compliant, secure, and regionally governed AI platforms will benefit from increasing public-sector procurement and digital modernization initiatives. Partnerships involving governments, academic institutions, semiconductor manufacturers, and commercial software developers are expected to accelerate innovation while expanding regional artificial intelligence capabilities across multiple strategic industries.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for