
Automotive Bumpers Market Growth, Trends & Demand by 2034
Coverage: By Material (Composite Plastic, Metal, Aluminium, Fiberglass Composite); Position (Front End, Rear End); Vehicle (Passenger Vehicle, Commercial Vehicle) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00005234
- Category : Automotive and Transportation
- No. of Pages : 150
- Available Report Formats :


- Last update date : August 10, 2026


2025 Market Size
US$ 25.00 Bn
Base year value
2034 Forecast
US$ 35.36 Bn
Projected by 2034
CAGR 2026-2034
3.93 %
Growth rate
Addressable Market
US$ 274.18 Bn
(2026-2034)
The automotive bumpers market was valued at US$ 25 Billion in 2025 and is projected to reach US$ 35.36 Billion by 2034, registering a CAGR of 3.93% during 2026–2034. Market expansion is supported by rising global vehicle production, increasing emphasis on passenger safety, and continuous adoption of lightweight bumper systems that improve vehicle efficiency while complying with evolving crashworthiness and pedestrian protection regulations across major automotive manufacturing regions.
Across North America, the automotive bumpers market size continues to benefit from steady vehicle replacement cycles, increasing demand for pickup trucks and SUVs, and investments in lightweight vehicle architectures. The regional market is expected to register a CAGR of 3.6%–4.2% through 2034, supported by stringent safety regulations, expanding electric vehicle manufacturing, and continued adoption of advanced polymer and composite bumper materials by leading automotive manufacturers.
Automotive Bumpers Market Assessment and Insights
- North America: Accounted for 31%–35% share in 2025 and is anticipated to expand at a CAGR of 3.6%–4.2% during 2026–2034. Demand is supported by strong SUV and pickup production, advanced manufacturing capabilities, and stringent crash safety regulations encouraging lightweight bumper technologies.
- US: Represented approximately 79%–83% of the North American market in 2025 and is projected to register a CAGR of 3.7%–4.3%. Strong OEM presence, high replacement demand, and increasing electric vehicle production continue to support long-term market expansion.
- Europe: Held 27%–31% market share in 2025 while growing at a CAGR of 3.5%–4.1%. Germany, France, Italy, and the UK remain leading production centers supported by advanced automotive engineering and lightweight material adoption.
- Asia Pacific: Accounted for 29%–33% market share in 2025 and is forecast to expand at a CAGR of 4.3%–4.9%. China, Japan, South Korea, and India continue driving regional demand through expanding vehicle manufacturing and increasing investments in electric mobility.
- Largest Segment: Passenger Vehicle accounted for approximately 71%–75% market share in 2025 and is expected to register a CAGR of 3.8%–4.3% owing to sustained passenger vehicle production and growing demand for enhanced vehicle aesthetics and safety.
- High Growth Segment: Composite Plastic is anticipated to witness the fastest expansion with 38%–42% market share in 2025 and a CAGR of 4.8%–5.4%, driven by lightweighting initiatives and increasing adoption in electric vehicles.
- Key companies analyzed in detail: Benteler International AG, Futaba Industrial Co., Ltd., Huayu Automotive Systems Co., Ltd., Hyundai Mobis Co., Ltd., Magna International Inc., OPmobility SE (formerly Plastic Omnium SE), Samvardhana Motherson Automotive Systems Group B.V. (SMP), Tong Yang Industry Co., Ltd., Toyoda Gosei Co., Ltd.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
Automobile companies are now focusing on bumper systems that incorporate high strength, low weight, and better styling to meet the changing needs and requirements of consumers and the government. Advances in materials have driven the use of composite plastics, aluminum, and fiberglass that can increase the fuel efficiency of vehicles while not compromising their crashworthiness. At the same time, automation in manufacturing processes and sensor-friendly bumper systems are changing the manufacturing process globally.
Moving forward, the upcoming automotive manufacturing centers in Southeast Asia, Eastern Europe, and Latin America will present new avenues for expansion. Investment in the production of electric vehicles, government policies for automotive manufacturing, and regulations regarding pedestrian safety are prompting suppliers to build their manufacturing capacity, research sustainable materials, and strengthen regional supply chains.
Automotive Bumpers Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 25.00 Billion |
| Market Size by 2034 | US$ 35.36 Billion |
| Global CAGR (2026 - 2034) | 3.93% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Automotive Bumpers Market Analysis
Increasing global vehicle production, expanding electric mobility, and rising safety requirements continue supporting the automotive bumpers market growth across OEM and aftermarket channels. There is an increasing need for lightweight bumper components among carmakers because they allow the reduction of vehicle weight without reducing their strength or compromising on pedestrian safety. An increased number of consumers who are purchasing SUVs and crossover vehicles is creating more demand for efficient front and rear bumper parts that can accommodate various sensors and camera-based devices.
There is continuous evolution within the industry value chain due to closer cooperation between raw material providers, bumper component manufacturers, OEMs and their distributors. Raw material providers, molding firms, coating companies and vehicle assembly plants become more effective when producing bumper parts in terms of efficiency and minimization of production waste.
Competitive intensity remains high as the automotive bumpers market analysis increasingly focuses on technological innovation, lightweight engineering, and manufacturing efficiency. Magna International Inc., Hyundai Mobis Co., Ltd., OPmobility SE, Benteler International AG, Toyoda Gosei Co., Ltd., Futaba Industrial Co., Ltd., and Huayu Automotive Systems Co., Ltd. are committed to the development of advanced materials, bumper platforms, and exterior systems for better relationships with OEMs and competitive operations around the world.
Investments made by these companies are strategically focused on sustainable manufacturing, recyclable composites, regional facilities, and automation. These companies are constantly developing engineering capabilities that are required for developing electric vehicle platforms, along with bumper systems suitable for use with driverless cars and new design standards for exteriors.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
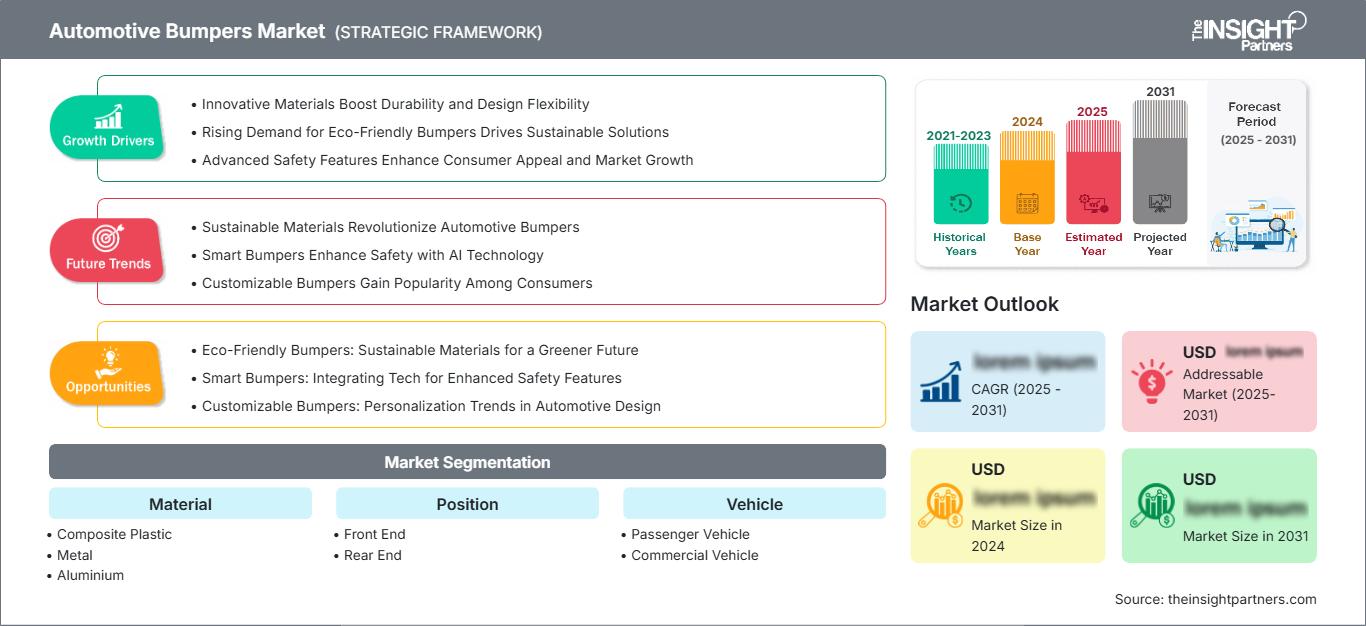
Automotive Bumpers Market: Strategic Insights
Regional Insights
North America Automotive Bumpers Market
North America accounted for 31%–35% of the global automotive bumpers market share in 2025 and is projected to register a CAGR of 3.6%–4.2% during 2026–2034. The regional market enjoys the advantages of having an established car manufacturing industry, high demand for SUVs and pickups, as well as regulatory focus on occupant and pedestrian protection. Manufacturers of Original Equipment still develop new-generation models of vehicles with lightweight composite bumpers and sensor modules to boost fuel consumption and incorporate driver assist features.
North America, comprising the United States, Canada, and Mexico, represents a highly developed supply chain in automotive manufacturing with regional manufacturing agreements and ongoing development of electric vehicle manufacturing capacities. Recycling of polymer materials, automation of the molding process, and module assembly of bumpers allow manufacturers to boost their efficiency and meet the rigorous requirements for crash protection.
U.S. Automotive Bumpers Market
The United States represented approximately 79%–83% of the North American market in 2025 and is expected to expand at a CAGR of 3.7%–4.3% through 2034. High indigenous manufacture of passenger cars, pickups, and SUVs ensures the need for innovative bumper systems. Leading manufacturers of automobiles are continually investing in lightweight designs, using more composite plastics and aluminum bumper systems in various types of vehicles.
Firms like Magna International Inc., Hyundai Mobis Co., Ltd., and OPmobility SE possess high operational capacity in the U.S. automotive industry. Integration of radar sensors, cameras, and parking aid systems in bumper assembly makes their products highly complex and value-added. The growing investments in the manufacture of electric vehicles are set to create new opportunities for bumper technologies through the forecast period.
Europe Automotive Bumpers Market
Europe held 27%–31% of the global market in 2025 and is forecast to grow at a CAGR of 3.5%–4.1%. Germany is still the major market in the region because of its rich history of manufacturing premium vehicles, efficient automotive engineering and use of lightweight materials. Continued investments in electric vehicle manufacturing spur demand for modern bumpers that enhance aerodynamics and improve vehicle safety features.
The United Kingdom keeps focusing on the manufacturing of premium vehicles and modern automotive designs, whereas France, Italy, and Spain have robust production capabilities backed up by well-established automotive suppliers and initiatives in electric mobility. European car manufacturers are increasingly using recyclable composite materials and automation in manufacturing to meet environmental regulations and increase efficiency. Continued innovation in products and sustainability efforts ensures Europe’s competitiveness in the global automotive sector.
APAC Automotive Bumpers Market
Asia Pacific accounted for 29%–33% of global market share in 2025 and is anticipated to record the fastest regional expansion with a CAGR of 4.3%–4.9%. Continued dominance in vehicle manufacturing is witnessed in China, while Japan and South Korea are still significant players in manufacturing auto parts. Automotive investments are being enhanced in India and Australia by way of increased manufacturing capabilities and favorable industrial policies in place. Growth in electric vehicle production, increased disposable income, and passenger car ownership still favor the region’s demand for advanced bumpers.
Middle East & Africa Automotive Bumpers Market
The Middle East & Africa market is expected to expand at a CAGR of 3.3%–3.9% during the forecast period. Saudi Arabia and the United Arab Emirates continue investing in automotive manufacturing diversification, while South Africa remains the region's leading vehicle production hub, supported by established automotive assembly operations.
Infrastructure development, expanding logistics activities, and gradual localization of automotive manufacturing contribute to regional demand growth. Continued investments in industrial diversification, supported by government initiatives, are expected to strengthen demand for high-quality bumper systems across passenger and commercial vehicle applications.
Segmentation Analysis
Material
The Material segment represents the technological foundation of the automotive bumpers market, with manufacturers increasingly prioritizing lightweight, impact-resistant, and recyclable materials to satisfy evolving fuel efficiency and safety requirements. The automotive bumpers market scope continues expanding as OEMs adopt advanced composites and aluminum solutions that improve crash performance while reducing vehicle weight. The segment is projected to grow at a CAGR of 4.0%–4.6% during 2026–2034.
- Composite Plastic: Widely adopted across passenger vehicles because of its lightweight characteristics, corrosion resistance, design flexibility, and compatibility with integrated sensors used in advanced driver assistance systems.
- Metal: Continues serving heavy-duty applications requiring superior structural strength, durability, and high impact resistance, particularly within commercial vehicles operating under demanding road and loading conditions.
- Aluminium: Gains increasing acceptance owing to its favorable strength-to-weight ratio, corrosion resistance, and ability to improve vehicle efficiency while supporting automotive lightweighting strategies.
- Fiberglass Composite: Used primarily in premium, sports, and specialty vehicles where superior styling flexibility, weight reduction, and improved structural performance remain key purchasing considerations.
Position
The Position segment remains an essential contributor to product innovation as manufacturers continue redesigning bumper systems to accommodate advanced safety features, aerodynamic improvements, and evolving vehicle styling requirements. Front bumper assemblies increasingly integrate radar sensors, cameras, and pedestrian safety technologies, while rear bumpers emphasize durability and collision protection. The segment is anticipated to register a CAGR of 3.7%–4.3% during 2026–2034.
- Front End: Represents the largest application due to the integration of crash absorption structures, grille assemblies, radar sensors, parking assistance systems, and pedestrian safety technologies within modern vehicle architectures.
- Rear End: Maintains strong demand across passenger and commercial vehicles by providing low-speed collision protection, supporting parking technologies, and improving overall vehicle structural integrity.
Vehicle
The Vehicle segment continues benefiting from expanding global automotive production, increasing safety regulations, and growing demand for aesthetically advanced exterior components. Passenger vehicles remain the dominant consumer of lightweight bumper systems, while commercial vehicle manufacturers increasingly adopt durable bumper solutions capable of withstanding demanding operating environments. The segment is forecast to expand at a CAGR of 3.8%–4.4% during 2026–2034.
- Passenger Vehicle: Maintains the highest market demand through large-scale global production, increasing consumer preference for attractive exterior styling, and widespread adoption of advanced safety technologies integrated into bumper assemblies.
- Commercial Vehicle: Demand continues growing steadily owing to expanding logistics operations, infrastructure investments, and increasing fleet modernization requiring durable bumper systems with enhanced operational reliability.
Opportunity Snapshot
| Vehicle | Revenue Contribution | Trend Tag | Adoption Stage |
|---|---|---|---|
| Passenger Vehicle | High | EV Production | Mature |
| Commercial Vehicle | Medium | Fleet Safety | Scaling |
Automotive Bumpers Market Growth Drivers and Impact Analysis
Increasing Vehicle Production and Global OEM Manufacturing Expansion
The growing production of vehicles within the developed and developing nations is leading to the continued growth of the demand for automotive bumpers in OEM and aftermarket segments. Vehicle ownership is gradually growing in Asia Pacific region, whereas the production of commercial vehicles is strong in North America, driven by European regions owing to the development in the logistics and infrastructure sector. The automotive companies have been expanding their manufacturing plants in close proximity to the markets and therefore, there is a growing demand for a lightweight bumper system. Moreover, the stringent safety requirements of the vehicles are further fueling the adoption of high-tech bumpers that absorb impact energy.
Growing Adoption of Lightweight Materials in Vehicle Design
Automobile producers are gradually incorporating new bumper materials such as plastic composites, aluminum, and fiberglass into the design of their products in order to decrease the overall weight of the vehicles, thereby improving their fuel efficiency. Lightweight bumpers help to achieve low emissions from internal combustion engine vehicles and extended driving distances in electric vehicles. In addition, innovative material technology facilitates better corrosion resistance, manufacturing flexibility, and the incorporation of sensors necessary for driver-assistance systems. Consistent investment in sustainable and recyclable polymers and composites helps to achieve environmental goals as well as comply with new regulations.
Expansion of Electric Vehicle Manufacturing and Smart Exterior Systems
The fast growth in production of electric vehicles is pushing the supply chain firms to redesign bumper systems, which will be able to incorporate radar, LiDAR systems, cameras, and electronic components. In contrast to the traditional bumper designs, the new designs should be compatible with technologies of autonomous driving, but without sacrificing the performance in terms of crashes and aerodynamics. The efforts of manufacturers are still focused on modular designs of the bumper systems that facilitate the assembly process and help cut down the cost of production.
Automotive Bumpers Market Future Trends
Advanced Composite Materials Becoming Industry Standard
Manufacturers increasingly prioritize sustainable lightweight materials capable of improving safety, durability, and manufacturing efficiency. The automotive bumpers market trends indicate broader adoption of recyclable composite plastics, high-strength polymers, and hybrid material structures designed to reduce vehicle weight without sacrificing structural integrity. Electric vehicle production is expected to accelerate this transition as manufacturers seek improved efficiency and extended driving range. Continuous research into bio-based polymers and recyclable composites will further reshape future product development strategies.
Integration of Smart Sensors within Bumper Assemblies
Modern bumper systems are evolving into multifunctional structural components capable of supporting advanced driver assistance technologies. Radar modules, ultrasonic sensors, parking cameras, and pedestrian detection systems are increasingly incorporated into bumper assemblies through modular engineering approaches. Future developments will emphasize seamless sensor integration, improved durability under diverse environmental conditions, and simplified maintenance procedures. These innovations are expected to enhance vehicle safety while supporting autonomous driving technologies over the coming decade.
Automotive Bumpers Market Opportunities
Growing Investments in Electric Vehicle Platforms
Global investments in electric mobility continue creating attractive opportunities for advanced bumper manufacturers. Automotive bumpers market Forecasts indicate increasing demand for lightweight exterior components compatible with electric vehicle architectures, integrated sensing technologies, and sustainable manufacturing practices. Suppliers investing in advanced composite materials, automated molding technologies, and regional production expansion are expected to strengthen relationships with leading automotive OEMs while benefiting from increasing electrification across global transportation markets.
Expansion of Premium Automotive Aftermarket Solutions
The global vehicle parc continues expanding, creating sustained demand for premium replacement bumper systems offering superior durability, aesthetics, and compatibility with modern safety technologies. Manufacturers can capitalize on growing aftermarket opportunities by expanding product portfolios, improving distribution capabilities, and offering vehicle-specific bumper solutions compatible with advanced electronic systems. Regional warehousing, digital sales platforms, and localized manufacturing will further strengthen competitive positioning across international aftermarket channels.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for