
Automotive Over The Air (OTA) Market Analysis and Forecast by Size, Share, Growth, Trends 2034
Coverage: By Technology (Firmware Over-The-Air Technology (FOTA), Software Over-The-Air Technology (SOTA)); Application (Electronic Control Unit (ECU), Infotainment, Safety and Security, Telematics Control Unit (TCU), Others); Vehicle Type (Passenger Car, Commercial Vehicle, Battery Electric Vehicle (BEV), Hybrid Electric Vehicles (HEV), Plug-In Hybrid Electric Vehicles (PHEV)) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00004326
- Category : Technology, Media and Telecommunications
- No. of Pages : 150
- Available Report Formats :


- Last update date : August 17, 2026


2025 Market Size
US$ 5.60 Bn
Base year value
2034 Forecast
US$ 33.26 Bn
Projected by 2034
CAGR 2026-2034
21.9 %
Growth rate
Addressable Market
US$ 154.09 Bn
(2026-2034)
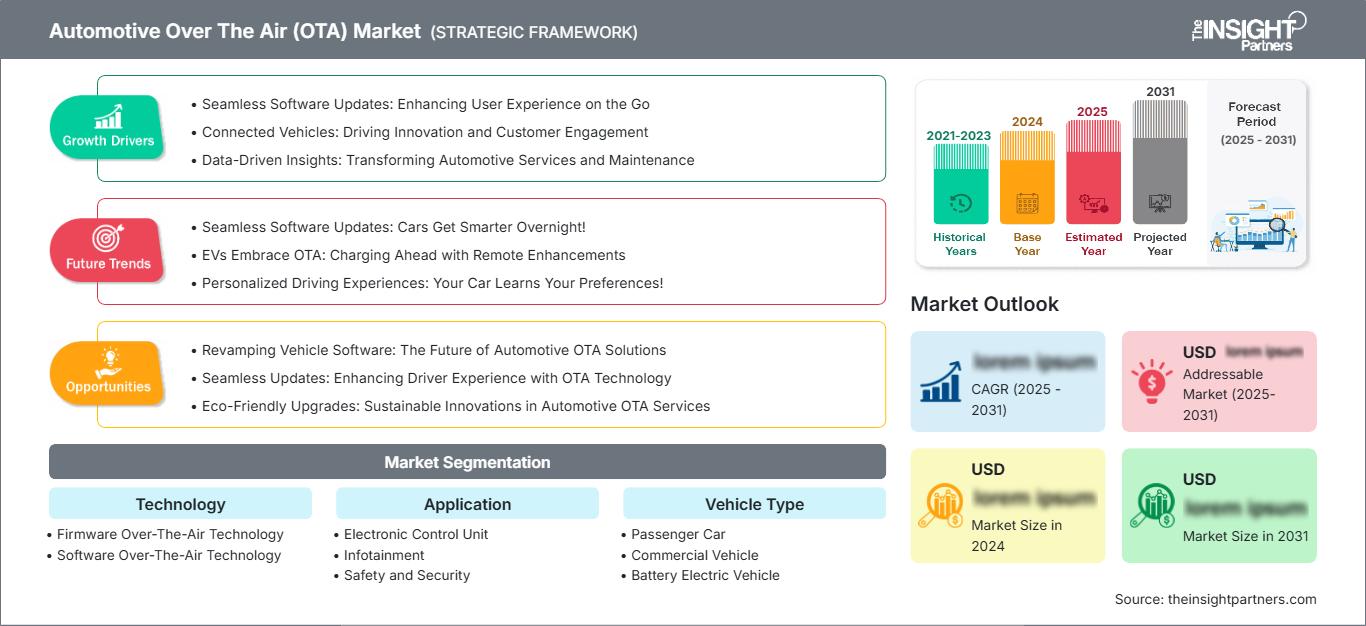
The automotive over-the-air market was valued at US$ 5.60 Billion in 2025 and is projected to reach US$ 33.26 Billion by 2034, registering a CAGR of 21.9% during 2026–2034. Market growth is being driven by increasing software-defined vehicle development, rising adoption of connected vehicles, and growing demand for remote software and firmware updates. Automotive manufacturers are leveraging over-the-air technologies to reduce recall costs, enhance cybersecurity, and continuously improve vehicle functionality throughout the ownership lifecycle.
Across North America, strong deployment of connected vehicles, expanding 5G infrastructure, and increasing software-centric vehicle architectures continue supporting the automotive over-the-air market size. The regional market is projected to expand at a CAGR of 20.6–21.4% during the forecast period, supported by growing investments in cloud-connected mobility platforms, cybersecurity frameworks, and intelligent vehicle management systems.
Automotive Over The Air (OTA) Market Assessment and Insights
- North America: Accounted for 31–34% share in 2025 and is projected to grow at a CAGR of 20.6–21.4% during 2026–2034. High connected vehicle penetration, mature telecommunications infrastructure, and strong software development capabilities continue driving regional adoption.
- US: Represented approximately 77–81% of the North American market in 2025 and is expected to register a CAGR of 20.8–21.6%. Increasing production of software-defined vehicles and investments in connected mobility platforms continue strengthening market expansion.
- Europe: Held 26–29% share in 2025 while recording a CAGR of 20.1–20.9%. Germany, the United Kingdom, France, Italy, and Sweden continue leading adoption through advanced automotive manufacturing and stringent cybersecurity regulations.
- Asia Pacific: Accounted for 34–37% share in 2025 and is projected to register the highest CAGR of 22.8–23.6% during 2026–2034. China, Japan, South Korea, and India continue expanding connected vehicle production and digital mobility ecosystems.
- Largest Segment: Software Over-The-Air Technology accounted for approximately 58–62% market share in 2025 and is expected to expand at a CAGR of 22.3–23.1%, supported by increasing software-defined vehicle deployment.
- High Growth Segment: Battery Electric Vehicle represented approximately 32–36% market share in 2025 and is projected to register a CAGR of 24.2–25.0% owing to increasing integration of cloud-based software update platforms.
- Key companies analyzed in detail: Continental AG, Fujitsu Limited, Harman International Industries, Inc., Airbiquity Inc., Infineon Technologies AG, Movimento Inc., Hitachi Automotive Systems, Ltd., NXP Semiconductors N.V., Robert Bosch GmbH, Wind River Systems, Inc.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The concept of SDV architecture has radically changed automotive product development by giving manufacturers the capability of updating their software after the vehicle has been shipped to customers. Ongoing innovations in cloud computing, connectivity in vehicles, and secured communication channels have made OTA updates more reliable and increased customer satisfaction, saving on warranty claims.
Further developments in the future markets will be driven by the adoption of technologies like autonomous driving, vehicle electrification, and centralized computing. OEMs in the automotive industry are still working with semiconductors, cloud computing companies, and cybersecurity experts in developing OTA ecosystems that can serve millions of vehicles.
Automotive Over The Air (OTA) Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 5.60 Billion |
| Market Size by 2034 | US$ 33.26 Billion |
| Global CAGR (2026 - 2034) | 21.9% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Automotive Over The Air (OTA) Market Analysis
The growing deployment of connected vehicles remains the primary contributor to automotive over-the-air market growth. Modern automotive companies are making use of OTA systems for the purpose of updating the software and other digital components in cars. With the shift towards the use of centralized architectures and software-defined vehicles, the need for scalable OTA platforms is rising.
The ecosystem of automotive OTA comprises various industries such as semiconductors, cloud infrastructure providers, cybersecurity providers, embedded software developers, vehicle manufacturers, telecom providers, and platform developers for vehicles. The use of 5G connectivity, edge computing, secure authentication, and cloud native software architectures is helping in speeding up the process of software deployment and lowering costs.
Competition within the automotive over-the-air market analysis continues to intensify as technology providers expand software platforms and cybersecurity capabilities. Companies including Robert Bosch GmbH, Continental AG, Harman International Industries, Inc., Airbiquity Inc., NXP Semiconductors N.V., and Wind River Systems, Inc. continue investing in secure cloud platforms, intelligent software management systems, and embedded vehicle operating environments that strengthen long-term competitive positioning.
Strategic investments increasingly focus on cloud-native OTA platforms, cybersecurity compliance, artificial intelligence, and digital lifecycle management. Automotive manufacturers continue forming partnerships with software companies and semiconductor suppliers to improve software deployment efficiency while supporting future autonomous driving functions, connected mobility services, and subscription-based digital vehicle features.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Automotive Over The Air (OTA) Market: Strategic Insights
Regional Insights
North America Automotive Over-the-Air Market
North America accounted for approximately 31–34% of the global automotive over-the-air market share in 2025 and is projected to register a CAGR of 20.6–21.4% during 2026–2034. The area has been supported by state-of-the-art connected vehicles infrastructure, extensive deployment of 5G communication networks, and significant funding in software-defined vehicle technology. The automotive makers are increasingly using OTA platforms to roll out software updates, cybersecurity patches, remote diagnostics, and feature improvements without necessarily visiting dealerships, thus enhancing customer satisfaction and cutting down warranty and maintenance expenses.
There has also been increasing cooperation between automotive makers, cloud service providers, semiconductor makers, and cybersecurity companies in the area. The rising use of electric vehicles and increasing demands for autonomy of driving systems have been continually driving the installation of secure OTA software management systems that are secure. The constant regulatory attention towards vehicle cybersecurity and digital safety continues to support growth in the market.
U.S. Automotive Over-the-Air Market
The US represented approximately 77–81% of the North American market in 2025 and is expected to grow at a CAGR of 20.8–21.6% during the forecast period. The robust local software development capacity, increased deployment of connected cars, and growing investment in intelligent transport systems are continuously driving market demand. More automotive players are relying on the OTA platform for deploying operating systems, security updates, battery optimization software, and ADAS features.
Increasing investment in cloud computing, artificial intelligence, and car connectivity is continuously augmenting the automotive software ecosystem in the country. Collaboration between automotive players and technology providers for managing the software life cycle, digital services, and compliance with cybersecurity standards is growing. Growth in the production of software-defined electric cars is anticipated to drive demand for OTA solutions.
Europe Automotive Over-the-Air Market
Europe accounted for approximately 26–29% of the global market in 2025 and is projected to expand at a CAGR of 20.1–20.9% during 2026–2034. Germany still maintains the largest regional market due to its strong automotive manufacturing industry, premium car dominance, and fast uptake of the software-defined vehicle approach. The automotive companies keep on adopting secure over-the-air technology to ensure compliance with regulatory frameworks and cybersecurity, as well as the remote deployment of features.
The United Kingdom continues to invest in connected mobility and intelligent transportation system infrastructure and improve its capabilities for vehicle software development. France is still promoting the deployment of over-the-air technology through the development of electric cars and other digital innovations. Italy keeps developing advanced connectivity in premium automotive manufacturing, while Sweden keeps excelling in connected vehicle safety systems.
APAC Automotive Over-the-Air Market
Asia Pacific accounted for approximately 34–37% of the global market in 2025 and is projected to register the highest CAGR of 22.8–23.6% during 2026–2034. China leads regional growth through large-scale connected vehicle production, rapid electric vehicle adoption, and significant investment in digital mobility infrastructure. Japan and South Korea continue advancing automotive software platforms and semiconductor technologies supporting OTA deployment.
India is emerging as an important market through increasing connected vehicle adoption, expanding 5G infrastructure, and government support for digital mobility. Australia contributes through the growing demand for connected passenger vehicles and advanced telematics solutions.
Middle East & Africa Automotive Over-the-Air Market
The Middle East & Africa market is projected to register a CAGR of 19.2–20.0% throughout the forecast period. Saudi Arabia and the UAE continue investing in smart mobility infrastructure, intelligent transportation systems, and connected vehicle technologies supporting OTA deployment. Increasing premium vehicle ownership also contributes to higher software update adoption.
South Africa remains the leading automotive manufacturing hub within the region while gradually expanding connected vehicle capabilities. The Rest of the Middle East & Africa is expected to witness steady growth as digital infrastructure improves and automotive manufacturers expand connected mobility offerings.
Segmentation Analysis
Technology
The Technology segment is projected to expand at a CAGR of 22.1–22.9% during 2026–2034. Increasing software-defined vehicle deployment and rising cybersecurity requirements continue to accelerate the adoption of advanced OTA technologies. The automotive over-the-air market scope continues expanding as OEMs transition toward centralized computing platforms capable of securely managing software and firmware updates throughout vehicle lifecycles.
- Firmware Over-The-Air Technology – Enables remote updating of embedded electronic controllers, improving hardware functionality, system stability, and cybersecurity while minimizing costly service campaigns and physical recalls.
- Software Over-The-Air Technology – Represents the dominant technology owing to increasing deployment of cloud-connected operating systems, infotainment software, autonomous driving functions, and subscription-based digital vehicle services.
Application
The Application segment is expected to register a CAGR of 21.5–22.3% during the forecast period. Growing software complexity within modern vehicles is increasing reliance on secure OTA platforms capable of updating multiple vehicle systems remotely while maintaining operational reliability and cybersecurity.
- Electronic Control Unit – Supports remote software calibration and firmware upgrades across critical vehicle control systems, reducing maintenance costs and improving long-term vehicle performance.
- Infotainment – Enables continuous enhancement of navigation, multimedia, voice recognition, and connected entertainment features through secure wireless software deployment.
- Safety and Security – Facilitates rapid cybersecurity patch deployment, advanced driver assistance system improvements, and functional safety updates without requiring dealership intervention.
- Telematics Control Unit – Serves as the primary communication gateway supporting cloud connectivity, remote diagnostics, software distribution, and real-time vehicle management services.
Vehicle Type
The Vehicle Type segment is projected to grow at a CAGR of 22.4–23.2% during 2026–2034. Increasing vehicle connectivity, electrification, and autonomous driving development continue to drive OTA implementation across multiple vehicle categories while improving lifecycle software management.
- Passenger Car – Represents the largest vehicle category due to high production volumes, rapid adoption of connected technologies, and increasing consumer demand for continuous software improvements.
- Commercial Vehicle – Increasingly adopts OTA platforms for fleet management, predictive maintenance, cybersecurity updates, and operational efficiency improvements.
- Battery Electric Vehicle – Demonstrates the fastest adoption owing to software-centric vehicle architectures requiring frequent battery optimization, charging management, and feature updates.
- Hybrid Electric Vehicles – Utilize OTA technology to improve powertrain optimization, energy management, and vehicle diagnostics throughout operational lifecycles.
- Plug-In Hybrid Electric Vehicles – Continue integrating advanced OTA capabilities supporting battery control, charging optimization, navigation enhancements, and remote vehicle management.
Opportunity Snapshot
| Vehicle Type | Revenue Contribution | Trend Tag | Adoption Stage |
|---|---|---|---|
| Passenger Car | High | Connected Mobility | Mature |
| Commercial Vehicle | Medium | Fleet Digitalization | Scaling |
| Battery Electric Vehicle (BEV) | High | Smart Charging | Scaling |
| Hybrid Electric Vehicles (HEV) | Medium | Powertrain Software | Scaling |
| Plug-In Hybrid Electric Vehicles (PHEV) | Medium | Energy Optimization | Emerging |
Automotive Over The Air (OTA) Market Growth Drivers and Impact Analysis
Expansion of Software-Defined Vehicle Architectures
The automotive industry is gradually moving towards software-defined vehicle platforms, where the software capability plays an important role in the determination of vehicle capability across the lifecycle of ownership. Instead of integrating new capabilities in production processes, OEMs keep adding new capabilities to vehicles through secure remote software deployments. Computing architectures have made software easier to manage and help in rolling out new performance capabilities, cybersecurity updates, navigation capabilities, and autonomous driving capabilities at a much faster pace. With the increased complexity in electronics, there has been an increased dependency on OTA capabilities that manage thousands of software modules in a vehicle platform.
Increasing Connected Vehicle Deployment Worldwide
The quick pace of production of connected vehicles further fuels the increasing adoption of OTA updates in the market segments for both passenger and commercial vehicles. Telematics-enabled vehicles that have cloud connectivity as well as fast communication facilities need regular updates in order to ensure their functionality, security, and compliance with regulations. With the increased adoption of the 5G infrastructure, there is an increase in speed in transmitting data. This allows larger software to be transmitted securely without causing much disturbance. Government bodies have also been supporting connected mobility systems by providing investment in intelligent transportation systems and digital communication networks.
Growing Importance of Automotive Cybersecurity Compliance
Cybersecurity has become a strategic priority as connected vehicles exchange increasing volumes of operational and consumer data. International cybersecurity regulations encourage manufacturers to maintain secure software environments throughout the vehicle lifecycle, creating sustained demand for OTA update platforms. Secure authentication mechanisms, encrypted communication protocols, and cloud-based software validation systems enable rapid deployment of security patches whenever new vulnerabilities emerge. OTA technology significantly reduces exposure to cyber threats by allowing manufacturers to respond immediately without requiring physical vehicle recalls. As software complexity continues increasing alongside autonomous driving capabilities, cybersecurity-focused OTA solutions are expected to remain fundamental to future automotive product development.
Automotive Over The Air (OTA) Market Future Trends
Artificial Intelligence Enhancing OTA Deployment
Artificial intelligence is increasingly being integrated into OTA software management platforms to optimize software validation, predictive diagnostics, update scheduling, and cybersecurity monitoring. AI algorithms evaluate vehicle operating conditions before initiating software deployment, reducing update failures while improving overall system reliability. Predictive maintenance capabilities further enable manufacturers to proactively identify software anomalies and deploy targeted updates before operational disruptions occur. These automotive over-the-air market trends indicate a broader transition toward intelligent software lifecycle management supporting autonomous mobility, connected ecosystems, and continuously evolving vehicle functionality.
Cloud-Native OTA Platforms Becoming Industry Standard
Cloud-native software deployment platforms are becoming central to automotive digital transformation strategies. Manufacturers increasingly utilize scalable cloud infrastructure capable of managing millions of connected vehicles simultaneously while maintaining high security standards and rapid deployment speeds. These platforms support continuous feature development, subscription-based services, personalized user experiences, and cross-platform software compatibility. Future OTA ecosystems are expected to integrate cloud computing, edge processing, artificial intelligence, and cybersecurity into unified digital vehicle management environments capable of supporting increasingly complex software-defined vehicles.
Automotive Over The Air (OTA) Market Opportunities
Expansion of Subscription-Based Digital Vehicle Services
Growing consumer acceptance of subscription-based automotive services presents a significant automotive over-the-air market Forecasts for OEMs seeking recurring revenue opportunities. Manufacturers increasingly monetize advanced driver assistance systems, premium infotainment, navigation packages, battery optimization software, and performance upgrades through OTA-enabled digital services. Flexible software activation enables customers to purchase new features throughout vehicle ownership while manufacturers generate continuous post-sale revenue. As software-defined vehicles become mainstream, subscription-based digital ecosystems are expected to represent an increasingly important component of long-term automotive profitability.
Emerging Markets Supporting Connected Mobility Expansion
Rapid digital infrastructure development across Asia-Pacific, Latin America, the Middle East, and selected African economies creates substantial opportunities for OTA platform deployment. Expanding electric vehicle production, increasing smartphone penetration, wider 5G coverage, and supportive government digitalization initiatives continue strengthening connected mobility ecosystems. Automotive manufacturers entering these high-growth regions increasingly incorporate OTA functionality into new vehicle platforms to improve customer experience, reduce maintenance costs, and enable continuous software innovation. These evolving mobility ecosystems are expected to generate long-term investment opportunities across cloud software, cybersecurity, semiconductor technologies, and connected vehicle services.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for